


Charging Orders on Property: Process and Rights


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you trying to understand what it means to put a charge on a property? You’re in the right place for answers.
This guide explains charging orders against property in England and Wales. Other UK jurisdictions and voluntarily agreed mortgage charges have different rules.
In this article, we’ll explain:
- What a legal charge on a property is.
- How a Charging Order works.
- The difference between interim and final Charging Orders.
- If creditors can see a charge on your profile.
- Possible ways to write off some of your debt.
We know you might be concerned about the impact of a Charging Order on the sale of your property, or other potential issues it might cause.
Read any court documents promptly and obtain debt or legal advice if your home or beneficial interest is affected.
What is a legal property charge?
A charge is security over property or an interest in it. A mortgage charge is usually agreed with a lender; a charging order is a court remedy that can secure a judgment debt. These are not the same type of document.
A debt does not have to be covered by the Consumer Credit Act for a charging order to be available. The legal basis, court judgment or order and debtor’s interest in the asset determine the route.
A charging order normally creates an equitable charge over the relevant property interest. Registration may involve a notice or a restriction, depending on the ownership and the order.
If only one of several beneficial owners owes the debt, the order may attach to that debtor’s interest rather than make the entire jointly owned home security for everyone’s debt.
A charging order does not itself order a sale. A creditor seeking a forced sale normally needs a separate court process, with applicable safeguards. Get urgent advice if an order for sale is threatened.
On a sale, the treatment of a charge depends on the title, priority, type of registration and conveyancing rules. Do not assume every Form K restriction operates like a mortgage or that every sale must pay all of the debt from the other owner’s share. See related guidance.
As you can probably infer, this isn’t a favourable situation for an individual who is already dealing with repayments.
The best advice we can give in this regard is to check properly if your lender can put a charge on your property and whether someone can dispute it.
» TAKE ACTION NOW: Fill out the short debt form
Is a Charging Order legal?
Charging orders under the ordinary civil procedure may secure a County Court or High Court judgment or order. Certain statutory debts have separate routes. A CCJ is therefore not the only possible legal basis. See related guidance.
We strongly suggest that you get proper legal advice about your situation and the debt associated with the charge in order to protect yourself.
The effect depends on the ownership, debt and order. The court can consider objections and the circumstances; avoid assuming that every application has the same outcome.
A charging order can affect future borrowing and sale proceeds. It is distinct from the existing mortgage, which may have priority.
What Types Are There?
A charging order can be of more than a single type. These charges do come in different shapes and sizes. Let’s discuss them one by one.
1. Interim Charging Order
An interim charging order is the first step of the charging process. It is a temporary order that can be made permanent through a final charging order.
First, your creditor informs the court that you either fully or partially own your house/property.
The creditor must follow the application requirements and identify the judgment and property interest. Proof that the debtor owns some property does not by itself guarantee a charging order.
An interim order can be made without a hearing, but the required documents must be served and affected people have an opportunity to object through the relevant procedure.
A final order is not automatically issued exactly 28 days after an interim order. The court considers the application after the applicable service and objection steps, or at a hearing.
Follow the deadline on the court papers and obtain prompt advice. For the Civil National Business Centre procedure in CPR 73.10, written objections must normally be filed and served within 28 days after service of the application notice and interim order. Other procedures use different hearing-related deadlines.
An objection under that procedure normally leads to transfer for a hearing. Set out the evidence and serve the creditor as required; a letter to your own solicitor alone is not filing an objection.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
2. Final Charging Order
After considering the case, the court may make a final order, discharge the interim order, direct a hearing or trial, or make another appropriate order. Doing nothing risks an order being made without your objections being considered. See related guidance.
The court serves the final order as required by the rules. It is not issued only because your solicitor asks for it.
A discharge, variation or appeal may be possible on appropriate grounds. The route, evidence and deadline matter; do not assume there is no meaningful remedy.
For example, you might:
- Seek advice on an application to discharge the charging order where there is a proper basis.
- Ask whether conditions or the order should be varied under the applicable procedure.
- Check whether a separate challenge to the underlying judgment or an appeal is required.
The court has specific powers to discharge or vary a charging order. Explain the actual grounds and evidence rather than relying on a vague “exceptional circumstances” test.
Can Creditors See the Charge?
Lots of people are unsure about whether things such as a deposit, a sale deed, a release deed, or a payment article show up on their credit profiles.
Similarly, many people are also unsure whether a charge shows up on their profile.
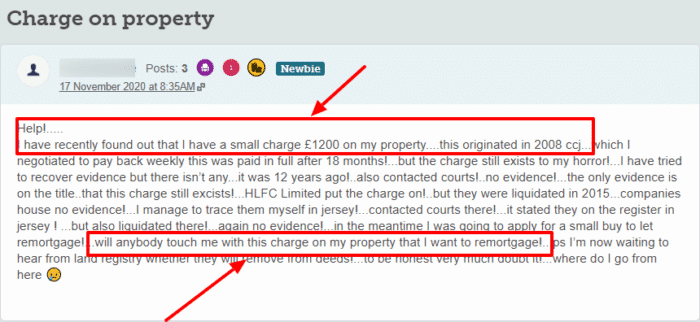
A charging order is normally reflected through land-registration arrangements rather than a separate ordinary credit-file entry. The underlying judgment may appear on the credit record, subject to its own registration and removal rules.
However, even if creditors can’t see it on your profile, that doesn’t mean it won’t impact your borrowing credibility.
Lenders, particularly with larger loans, tend to be very picky with who they lend to.
A lender may check the property title and ask about secured debts when assessing an application. Do not assume a charge is invisible simply because it is not a separate credit-report entry.
All in all, while they can’t see a charge on your credit file, there are plenty of other ways of knowing that it’s there.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.






Is Your Charging Order Legal?
Not all Charging Orders are legal. Your creditors must have fulfilled certain criteria to issue one.
If you aren’t sure your’s is legal, then it’s worth seeking professional help.
JustAnswer is an online solicitors service who have a £5 offer to chat with a solicitor for 7 days.
Try it out below.