


QDR Solicitors Debt Letters: Claims, Payments and Disputes


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
A letter from QDR Solicitors may concern a creditor’s demand or legal claim. Check the named client, account and response deadline.
In this guide, we will cover how to:
- Check if the debt is really yours.
- Distinguish an ordinary demand, Letter of Claim and court claim.
- Request appropriate contact arrangements.
- Set up a plan to pay back the debt.
- Find out if you can write off your debt.
You can obtain independent advice if the debt is disputed or unaffordable.
Don’t worry! We’re here to help you understand how to deal with QDR Solicitors.
Why are QDR Solicitors Debt Recovery contacting you?
Do not assume QDR bought your debt. Acting as a solicitor for a creditor is different from owning an assigned account.
Ask for the basis of the demand and relevant documents without assuming that the letter proves liability.
We go through the process of verifying debts below.
Do you really owe the money?
Check the creditor, balance and payments already made, and explain any specific dispute.
You can use our free letter template to help you contact QDR Solicitors to request evidence that you are liable as they claim.
It is also quite common for a debt collection agency to try and collect on a debt that is statute-barred.
For many unsecured debts in England and Wales, the usual limitation period is six years from the relevant cause of action, not simply the last phone call. A payment, qualifying written acknowledgement or court proceedings can affect the position. Scotland usually has a five-year prescription period for many ordinary debts, with different rules and exceptions. Court judgments, secured debts and some tax debts require separate advice. Get free debt advice before paying or acknowledging an old debt; do not ignore court papers.
Keep in mind that not all unsecured debts become statute-barred after 5 or 6 years.
Judgments and tax debts have separate rules. It is inaccurate to say every CCJ is enforceable forever without restrictions or further procedural requirements.
Evidence of an agreement is relevant, but does not settle every question of enforceability, balance or defence. Get advice if you still dispute the claim.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Can you just ignore QDR Solicitors?
We always recommend responding to debt collectors – even just to question the debt’s validity.
If you dispute the debt, explain why and ask for an itemised balance and evidence that you are liable. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel a debt, override an existing court order or extend a court deadline.
» TAKE ACTION NOW: Fill out the short debt form
What are your other debt options?
Debt Management Plan (DMP)
A DMP is an informal debt solution that will allow you to pay off several non-priority debts at once. Keep in mind that this is an informal debt solution as it has no legal weight behind it.
For regulated consumer credit, appropriate forbearance must be considered in light of your circumstances. An informal plan does not itself guarantee a freeze on interest or legal action. For regulated credit, if the firm has put a repayment arrangement in place as forbearance and you meet its terms, it must reduce, waive or cancel further interest and charges enough to prevent the debt increasing during that arrangement.
Individual Voluntary Arrangement (IVA) or Trust Deed
An IVA is a formal arrangement administered by an insolvency practitioner. Its approved terms govern contributions, assets and fees; only covered debts remaining on successful completion are released. It does not ban every required creditor communication.
If an IVA fails, included debts may remain payable. Read its terms and compare other options before agreeing.
There is no universal statutory minimum debt or requirement for two creditors. Suitability depends on your debts, assets, affordable contribution or lump sum and creditor approval. Compare alternatives through independent debt advice.
A protected trust deed is one possible Scottish insolvency option, normally involving four years of contributions and consideration of assets. It has different rules from an IVA. A Scottish money adviser can also consider the Debt Arrangement Scheme, bankruptcy and informal arrangements.
Debt Relief Order (DRO)
If you have debts but no real assets and little income, you may be able to qualify for a DRO.
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Continue paying essential ongoing bills and excluded debts. A DRO does not prohibit every required creditor notice. Report relevant changes; qualifying debts are normally discharged at the end if the order remains in force.
Bankruptcy or Sequestration
Bankruptcy or sequestration in Scotland is often your last option if you have lots of debts but no way of realistically paying them off.
Many of your unsecured debts can be written off using bankruptcy, but keep in mind that it is a serious financial situation that is not to be applied for without serious consideration.
Scotland’s Minimal Asset Process is a route into bankruptcy for people who meet its conditions. Its application fee has been removed. Ask an approved Scottish money adviser to compare it with the alternatives and explain the effects on assets, credit and income.
Will they send bailiffs to your house?
Here’s a quick table to help you better understand the different rights debt collectors and bailiffs have. If you want to learn more about your rights, be sure to read our specialized guide.
| Issue | Debt collector | Bailiff or enforcement agent |
|---|---|---|
| Role | Requests payment for a creditor or debt purchaser. | Acts under a legally valid enforcement power and must follow its limits. |
| Entry | No power to force entry; you can refuse entry and ask them to leave. | Usually cannot force first entry to a home for council tax or an ordinary civil debt. Limited exceptions and re-entry rules apply. |
| Goods | Cannot seize your goods. | May take non-exempt goods belonging to the debtor where the legal conditions are met; essential items and some work equipment are protected. |
| Bank accounts | A judgment alone gives no access. | Taking money from an account normally requires a separate third-party debt order obtained by the creditor, not a doorstep bailiff power. |
| Contact | Must avoid harassment; regulated firms must contact at reasonable times. | Visits are normally between 6 am and 9 pm, subject to legal exceptions. |
| Vulnerability | Tell the firm what support or communication adjustments you need. | Tell the agent and creditor about vulnerability and seek advice about additional safeguards. |
| Disputes | Ask for evidence of the debt and complain about improper conduct. | Check identification, the enforcement authority and fees; get urgent advice about an invalid notice or proposed entry. |
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
What if QDR Is Pursuing a Private Parking Charge?
Forum accounts describe individual experiences and do not establish the outcome of your own parking dispute.
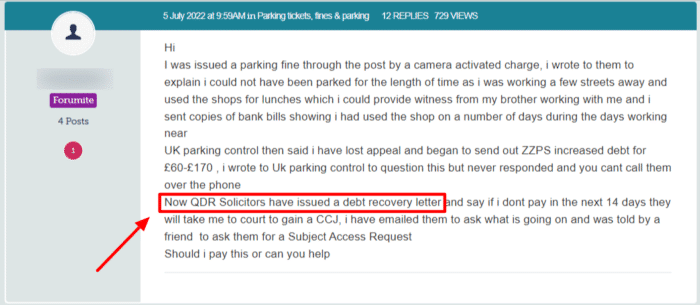
This person could do with talking to a debt charity for some advice! We have linked a few at the bottom of this page.
A general proof request does not replace a defence, stop a claim or guarantee that a court will reject it. Use the correct procedure for the stage reached.
How Can You Manage Contact?
How do you complain about QDR Solicitors?
QDR Solicitors Limited is listed by the Solicitors Regulation Authority under number 560560. The applicable financial rules and complaint route depend on the activity, so do not assume every parking claim falls within FCA consumer-credit regulation.
If you believe that they have broken these rules when dealing with you, you can make a complaint.
You should first make a complaint directly to QDR Solicitors. This will give them the opportunity to deal with the matter with their own policies.
Complain to QDR first. Serious professional misconduct can be reported to the SRA, which does not resolve the underlying debt dispute or award ordinary compensation. Financial Ombudsman eligibility depends on the activity; a private parking claim is not automatically covered. The Legal Ombudsman normally deals with eligible complaints about legal services provided to the complainant, not simply an opponent’s solicitor.
QDR Solicitors contact details
| Official website | QDR Solicitors |
| Account enquiries | 01926 758736, as listed in QDR’s official FAQs. Verify the reference and contact before sharing payment details. |
| [email protected] | |
| Office | Olympus House Olympus Avenue Leamington Spa Warwickshire CV34 6BF |
References





