Selling Home to Pay for Care – Can You Avoid It?


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Are you worried about having to sell your home to pay for care? You're not alone. Many people feel the same way. Understanding how to avoid this situation can be tricky, but don't worry; you've come to the right place.
In this article, we’ll explore:
- The risks to your home’s equity
- The costs of care homes
- How the value of your home is calculated
- Tips on getting a realistic quote
- Ways to avoid selling your home to pay for care
We know that the idea of selling your home to pay for care can be scary. You may be confused about the equity release process, but we’re here to help. We have the expertise and understanding to guide you through this.
We want to help you understand the situation better and make the best possible choice. We’ll walk you through the complexities of this important issue and answer your questions along the way.
Let’s dive in.
How many people do it?
There is no dated, verified current estimate in this article of how many people sell a home to fund care. The need to sell depends on individual funding and property circumstances. See related guidance.
Advertisement. In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
Can you be forced to sell your house to fund care fees?
A home sale is not automatically required on entering care. A needs and financial assessment, property disregards and funding alternatives should be considered; unpaid care charges can still become recoverable debts. See related guidance.
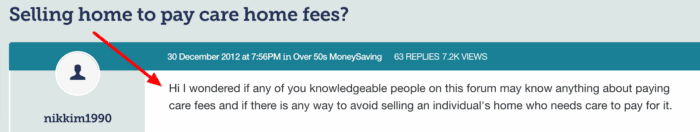
Source: https://forums.moneysavingexpert.com/discussion/4364807/selling-home-to-pay-care-home-fees
If you don’t know about another solution, you can feel like you’re being forced into selling the property to pay the care home fees.
Yet, selling your home to pay for care isn’t the only solution. There are other things you can consider, which will be explained in this guide.
Consider the costs and risks of equity release
Equity release is a long-term decision. A lifetime mortgage is secured against your home. Adding interest can substantially increase the debt and reduce your inheritance.
Consider fees, means-tested benefits, early repayment charges and future care needs. Alternatives include downsizing, other assets or a retirement interest-only mortgage where affordable.
Start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
Advertisement. MoneyNerd introduces enquiries to Age Partnership, which advises on lifetime mortgages, and may receive a referral fee.
Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply. Interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
How can it be avoided?
Depending on eligibility and circumstances, options may include:
- Deferred Payment Agreement (DPA)
- Other suitable funding, potentially including equity release for care at home. Moving the final borrower permanently into care normally triggers lifetime-mortgage repayment, so it is not a general solution for permanent residential care. See related guidance.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
What is a Deferred Payment Agreement?
In England, an eligible deferred payment agreement can let the council defer some assessed care charges using acceptable property security. Rules differ elsewhere in the UK.
Deferred charges, interest and fees remain repayable under the agreement, commonly after a sale or death. Contributions and an equity limit apply.
The property does not inevitably have to be sold after death if the estate can repay the debt from other funds. Personal representatives should confirm the deadline and settlement terms.
The proposed £86,000 cap was not introduced in October 2023; the planned charging reforms were later cancelled. It must not be presented as an available current cap.
What is an equity release plan?
An equity release plan is another option when you want to avoid selling your home and still pay care home fees. In fact, an equity release plan might provide you with enough money to pay for private care in your own home.
Most standard lifetime mortgages start at age 55, but some payment-term lifetime mortgages are available from 50 and require interest payments for an agreed period. Home-reversion minimum ages and all other eligibility rules depend on the provider. Check the youngest applicant’s age and the actual product criteria. Eligibility depends on the product, age, property, credit circumstances and any required affordability assessment. Minimum property values and borrowing limits are lender-specific. An existing mortgage normally has to be cleared at completion, often using some of the released funds.
A lifetime mortgage is a loan secured on your home; you retain ownership. Interest that is not paid is added to the balance. The loan is usually settled when the last borrower dies or moves permanently into care, subject to the contract. Required or optional repayments vary by product.
Interestingly, the lifetime mortgage company adds a charge to the property. So the council couldn’t count your property as 100% of your asset within a means test if you were to later apply to live in an aged care facility. But if you were to do this intentionally, it could be classified as deprivation of assets!
About Age Partnership
Equity release is a long-term decision. Specialist advice is needed to assess suitability and compare the costs, risks and alternatives.
Advertisement. MoneyNerd introduces enquiries to Age Partnership, which advises on lifetime mortgages, and may receive a referral fee.
Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply. Interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
How much are care home costs?
Care-home fees vary substantially by location, provider, room and level of care. Obtain current written quotes rather than budgeting from the historic £704 weekly figure. See related guidance.
In England for 2026–27, the upper capital limit is £23,250 and the lower limit is £14,250. Disregards and income contributions matter; capital below the upper limit does not mean all care is free. Other UK nations have different rules.
The proposed £100,000 upper capital limit was not introduced. Use the current rules for the relevant UK nation and an individual assessment.
There are times when your property will and won’t be included in the means test, which have been explained in detail by Age UK here.
How will they calculate the value of my property?
As part of the council’s means test, it will need to calculate the value of your home. They might do this with market data, or they could ask for an updated valuation of your home from an estate agent.
Things to consider
Equity release includes lifetime mortgages and home reversion plans. A lifetime mortgage is a loan secured on your home; a home reversion plan sells part or all of the property. Equity release reduces what may be left in your estate and can affect means-tested benefits and future care funding. A lifetime mortgage is usually repaid when the last borrower dies or moves permanently into care, subject to the plan terms. Specialist financial and independent legal advice are needed. Any existing mortgage must normally be repaid from the proceeds or other funds. Age Partnership publishes an advice fee of £1,995 payable on completion; confirm the current fee in your personalised illustration. Lender and legal fees may also apply.