Short Term Equity Release – Should You Do It?


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
"Are you keen to understand more about short-term equity release? You're at the right spot. In this article, we'll cover:
- What equity release is.
- Risks of releasing your home’s equity.
- How to get a realistic quote.
- What a lifetime mortgage and home reversion plan are.
- If short-term equity release is possible.
We know that the idea of equity release can be confusing. We get that you may have many questions about the process, but we’re here to help. We’ll offer lots of useful advice to guide you through the process as we understand your situation and aim to make things clearer step by step.
Let’s start our journey into understanding short-term equity release.”
Does it really exist?
Equity release is generally designed for long-term needs. If you expect to repay soon, consider other options and check early-repayment charges. Health-based underwriting does not turn a lifetime mortgage into a short-term loan.
Are there short term methods?
Minimum advances and costs vary by provider. For a small or short-term need, compare the total cost and repayment flexibility of suitable alternatives.
What are other ways to do it?
Compare downsizing, savings or other assets, benefits and grants, a standard mortgage or retirement interest-only mortgage where affordable, and other suitable borrowing. A specialist adviser should assess the alternatives; equity release is not the only option in later life.
- Second charge mortgages
- Remortgaging to release equity
Second charge mortgages refer to home equity loans and other loans that are secured by home equity. They are added to a property with an existing first charge mortgage and repaid separately, often to a different lender.
On the other hand, remortgaging to release equity is switching your current mortgage to a bigger mortgage, using your home equity as a way to secure more credit. The additional money beyond what needs to be repaid to the first mortgage lender is paid out as a lump sum to be spent as desired.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
What are the different types?
Home reversion terms, purchase prices and occupancy conditions vary. Compare actual offers with specialist advice.
Lifetime mortgage
Eligibility depends on the product, age, property, credit circumstances and any required affordability assessment. Minimum property values and borrowing limits are lender-specific. An existing mortgage normally has to be cleared at completion, often using some of the released funds. Many lifetime mortgages allow interest to roll up without regular payments, but some require interest payments for a set period. Optional repayments, limits and any early-repayment charges depend on the contract.
Home reversion plan
A home reversion plan is a sale of part or all of your home, usually below open-market value, in return for money and the right to remain under the plan’s occupancy terms. It is not a loan. The provider receives its agreed share when the home is sold.
What is the best type?
Rolled-up interest compounds over time. How quickly the balance grows depends on the interest rate, compounding, fees and repayments; request projections for different durations.
The most common type of equity release plan in the UK is a lifetime mortgage. This might be because voluntary interest repayments are possible, which can therefore keep the debt lower over time.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
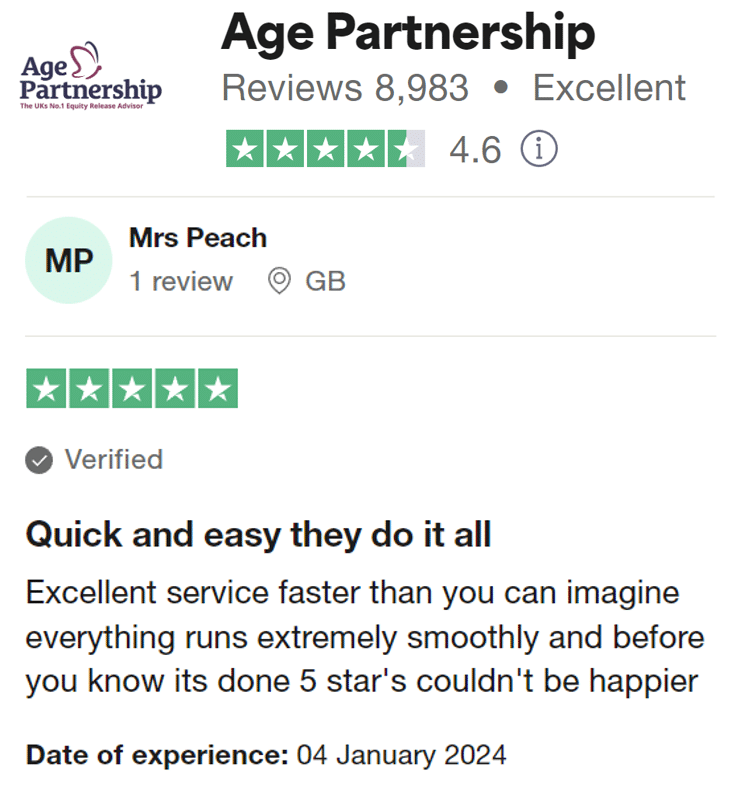
Reviews shown are for Age Partnership. Search powered by Age Partnership.
What are the pitfalls?
For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
Quick recap
Life expectancy cannot reliably determine a short repayment term. Enhanced medical underwriting does not remove early-repayment charges or make equity release appropriate for a short-term need. See related guidance.
Compare other suitable funding options with an adviser, including their affordability, term, fees and repayment conditions. A secured loan or remortgage also puts the home at risk.