


Cars and Car Finance in a Scottish Protected Trust Deed


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
This guide explains how a car or vehicle-finance agreement can be treated in a Scottish protected trust deed. Keeping a vehicle or obtaining new finance depends on ownership, value, practical need and the terms of the arrangement.
Keep a clear record of your debts, income and essential costs. Free independent debt advice can help you compare the options available where you live.
This article will help you understand:
- What a trust deed is
- How your car plays a role in a trust deed
- What you can do if you have a trust deed and need car finance
- How to handle your car during and after a trust deed
- If a trust deed can affect your chance to get car finance
A protected trust deed is a Scottish insolvency arrangement. Vehicle ownership, value, practical need and any finance agreement all affect the outcome.
Discuss the vehicle with the proposed trustee before signing, and get the agreed treatment in writing.
A protected trust deed involves trustee fees, income and asset commitments, credit effects and a public Register of Insolvencies entry. Creditors can object to protection. If the arrangement fails, remaining debts can become recoverable again and bankruptcy may follow. Some debts are not discharged. Ask the trustee to explain all fees and risks and compare other Scottish options before signing. See AiB’s protected-trust-deed information.
What happens to my car?
A trust deed transfers relevant assets or interests to the trustee under its terms; it is not simply a loan secured on your car. The vehicle’s ownership, value and any exemption must be assessed. See related guidance.
A vehicle you reasonably require and whose value does not exceed £3,000 can be exempt under the Scottish rules. Exactly £3,000 is within the threshold; need and the other conditions still matter.
When it is worth more than £3,000, the Trustee will practice some discretion concerning how they manage it.
This implies they can offer it to pay your debts.
In the event that they do place the car in a position to pay off debt, they ought to have discussed this with you before you agree on your Trust Deed.
If a different arrangement is proposed for a more valuable car, ask how it complies with the trust deed and obtain written agreement before relying on it.
Do not assume the trustee will wait for depreciation to bring the vehicle under the exemption threshold.
Any decision to retain the car, realise its value or accept a third-party payment should be explained and documented by the trustee.
Is financing possible?
Although difficult, it is possible to get car finance with a Trust Deed.
However, you should always bear in mind that entering a Trust Deed will make getting any sort of credit very troublesome, which may reduce your options for car finance.
A lender may decline an application or offer restricted terms. There is no universal rate: compare affordability and total cost, and obtain the trustee’s agreement before applying.
Because of this, it’s highly unlikely that you can get a good rate of car finance along with a Trust Deed -however, it’s not impossible.
Key Components
As we delve into the details of car finance with a Trust Deed, it’s crucial to understand the core aspects of this financial setup.
The table below explains the key components of a Trust Deed.
| Trust Deed Aspect | Details |
|---|---|
|
Average Length |
Typically 4 years; varies based on individual circumstances |
| Eligibility | Must be a resident of Scotland with unsecured debts of at least £5,000 |
| Assets | High-value assets like property and vehicles may be included in the arrangement and may have to be sold to pay off debts |
| Credit Impact | Credit score is negatively impacted and stays on your credit file for 6 years |
| Debt Types Included | Unsecured debts such as credit card balances, personal loans, overdrafts, store cards, catalog debts, and some types of tax and utility arrears |
| Debts needing separate advice | Secured creditors retain rights over their security. Some liabilities, including certain court fines, maintenance obligations and student loans, are not discharged. Ask the trustee to check each debt and any hire-purchase agreement. |
| Monthly Payments | Based on what you can afford, reviewed annually |
| Creditor contact | Once the deed is protected, creditors bound by it cannot pursue recovery of included debts, but required statements and notices may still be sent. |
| Discharge from Debts | Most remaining unsecured debts are written off at the end, assuming compliance with all terms |
| Practical effects | Essential belongings are generally protected. Your home, valuable assets and bank arrangements need individual assessment; none is guaranteed to remain unaffected. Check employment or professional rules. |
| Your obligations | Co-operate with the trustee, make agreed payments and report changes in income, employment or assets promptly. Get advice before new borrowing or dealing with assets that form part of the deed. There is no general ban on changing jobs. |
Can I keep my vehicle?
You may be able to keep an exempt or appropriately agreed vehicle, but needing transport does not guarantee you can retain any car regardless of value or finance terms.
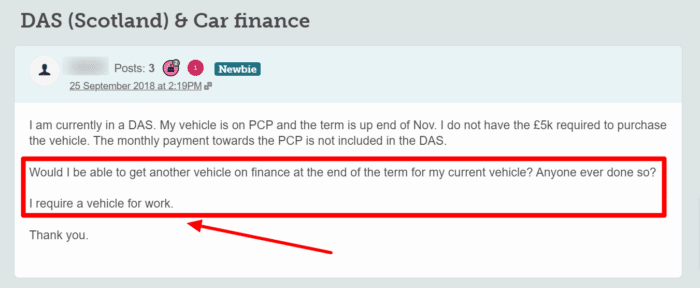
There are a number of reasonable requirements for buying a car during a Trust Deed or other debt plan – for example, you may need it in the case of a car breakdown or for an essential job change/work travel, as this forum user discusses:
Work, caring, health needs and access to public transport can be relevant when assessing reasonable need. School journeys or a rural address are not an automatic exemption for every vehicle.
This incorporates vans and motorbikes as well.
If the car is on hire purchase or another finance agreement, the lender may retain ownership or contractual rights. Check any insolvency clause and whether the lender and trustee agree that affordable payments can continue.
A necessary and reasonable finance payment may be allowed in the budget, but this is not guaranteed and does not override the lender’s contract. Ask about alternatives if the agreement cannot continue.
How do I get it?
Discuss proposed car finance with your trustee before applying and check whether your trust deed requires consent. New borrowing is not automatically included in the existing deed, and both its repayments and the trust-deed payments must remain affordable.
Failing to comply with your trust deed’s terms or to co-operate with the trustee can put the arrangement at risk. Ask what information or permission is required and obtain any agreement in writing.
Your Trustee will decide whether your request to take out car finance is sensible.
The Trustee will choose if taking out a car on account is appropriate for you, depending on your pay and consumption.
Affordability and practical need are relevant, but trustee consent does not guarantee lender approval. Do not assume new finance will be accepted.
Special consideration will be given when you require the car for work purposes.
Considering selling your car?
You should always discuss and agree on any car sale with your trustee before you sell.
There might be no issue, or your trustee may have an interest in the sale proceeds. It relies on the circumstance, so you should get the proper guidance and assistance before you sell.
Is it necessary for your trustee to sell it?
An agreed third-party contribution or other arrangement may sometimes avoid sale of a non-exempt vehicle. The amount and terms require assessment and approval; they are not automatically limited to the value above £3,000.
On the other hand, the trustee may agree that an ‘outsider’, similar to a relative or companion, can purchase out their advantage in the car by making contributions during the Protected Trust Deed.
What happens once it’s completed?
After discharge, check what obligations or asset realisations remain and review your credit reports. New borrowing still depends on affordability and lender checks.
The Register of Insolvencies entry is not removed immediately on your discharge. It normally remains until 12 months after the trustee’s discharge, which can occur later.
Unfortunately, the Trust Deed will stay on your credit file for six years from the date you took out your Trust Deed.
So, if your Trust Deed is in place for the standard time period of four years, it will stay on your credit document for an additional time period of two years.
Will completing it affect my ability to obtain financing?
Having a trust deed on your credit report will affect your credit score, which can make it harder to secure an appropriate lender (than if you had no financial disparities).
Credit recovery takes time and does not guarantee a better rate. Compare actual offers, total repayable and affordability before taking new finance.
If transport is essential, discuss affordable alternatives with an adviser before making multiple credit applications.
References
Choose how to get debt advice
Find free, impartial debt advice through MoneyHelper. An adviser can compare options using your circumstances. If you have court papers, an eviction warning or an enforcement deadline, seek help promptly rather than waiting for a callback.
Request an introduction to The Debt Advice Service
MoneyNerd provides general information and introductions. We do not give debt advice, assess suitability or recommend a debt solution.
If you complete our form and agree to an introduction, we may share your details and answers with The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, so its team can contact you. Completing the form does not mean you qualify for a solution.
Using MoneyNerd and making an enquiry are free. The Debt Advice Service’s advice is free and there is no obligation to proceed. Fees apply to some debt solutions; credit records and assets may be affected. A solution may be administered by another provider or an insolvency practitioner. Ask who would provide it and what fees and terms apply before agreeing.
MoneyNerd Limited may receive a payment if someone we introduce enters an IVA or debt management plan through The Debt Advice Service. The payment can differ between solutions. MoneyNerd does not make the recommendation.
For debt introductions, MoneyNerd Limited (FRN 978681) is an Introducer Appointed Representative of Pacific Financial Solutions Limited (FRN 688034), which is authorised and regulated by the Financial Conduct Authority.
Scottish solutions have separate rules. A DAS application needs an approved money adviser; a protected trust deed needs a licensed insolvency practitioner. This enquiry does not apply for either solution.
Request an introduction to The Debt Advice Service
Read our Privacy Policy and Complaints Procedure. Depending on the complaint, you may be eligible to refer it to the Financial Ombudsman Service.


