


What Is a CCA? – Simple Guide, FAQs & Tips


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you worried about your debt and are seeking ways to ease your stress? You’ve come to the right place for answers. This article will help you understand what the CCA is and how it can be used to manage your debt problems.
Every month, over 170,000 people approach us to find solutions for their debt issues. So remember, you’re not alone in this.
In this article, we’ll explore:
- What the Consumer Credit Act (CCA) does.
- How to request your CCA agreement.
- What happens if your creditors do not send the CCA agreement.
- Can a debt be enforced without a credit agreement.
We understand your worries about being chased for debt, as some of our team members have faced similar situations. We know how hard it is, but don’t worry; we’re here to help you understand your rights and find the best way to handle your debt.
Let’s understand more about the CCA and how it can help manage your debt.
What do they do?
The Consumer Credit Act (CCA) provides consumers with protection when taking out credit, like loans or credit cards.
Let’s look at the debt and credit regulated by the Consumer Credit Act:
- Credit cards
- Hire purchase agreements
- Payday loans
- Personal loans
- Store cards
- Catalogue credit (e.g. “buy now, pay later” agreements)
If you are borrowing money in the UK, the Act automatically provides you with a high level of credit protection laws, such as the right to a cooling-off period.
It is also used to shape the credit agreement terms and conditions.
What’s a credit agreement?
A CCA agreement is a document relating to the credit you took out from a bank or credit card company.
For example, if you took a loan, you will have signed a CCA agreement that outlines all of the details and terms of the loan under the aforementioned Act.
Remember, you have the right to withdraw from any credit agreement within 14 days of acceptance or when you receive a copy of the agreement. For credit cards, this is 14 days after you’ve been notified of your credit limit.
Also, under the CCA, you have the right to see your credit file and ensure that it is correct and accurate. You can contact the credit referencing agency that produced the report and ask them to update your details.
» TAKE ACTION NOW: Fill out the short debt form
How can I get a copy?
Anyone who has taken out credit covered by the Act can ask for a copy of their CCA agreement. This is known as a CCA request.
You may already have a copy of it, but you can ask the lender at any time to provide the CCA agreement.
You lose an automatic right to access your agreement if you have finished paying back the money you borrowed. However, you can still request a CCA after clearing the debt, although the creditor may not be obliged to provide it.
If you are part-way through your total payments, you are legally allowed to ask for this under Sections 77,78 and 79 of the Act.
How to ask for one
You can phone and ask for your agreement, but the best way to ask your creditor for a copy of your CCA agreement is to put it in writing. Send your creditor a letter requesting your CCA agreement, and they will provide it to you.
If you are unsure of how to work the letter, you could always use our free pre-written letter template to ask for your credit agreement.
Download the template, add your account info, name and address and send it off in the post. It will save you time and lots of headaches.
Be aware that to ask for your agreement, you will need to enclose a £1 (in the form of a coin, cheque, or pot order) inside the letter. This is the fee for requesting a credit agreement.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What happens if they don’t send it?
Creditors have 12 business days to respond to your CCA request letter. You may need to wait this long for them to respond. During this time, they cannot take further legal action against any debt you may have with them.
If they do not respond soon enough, you could make a complaint to the Financial Conduct Authority (FCA).
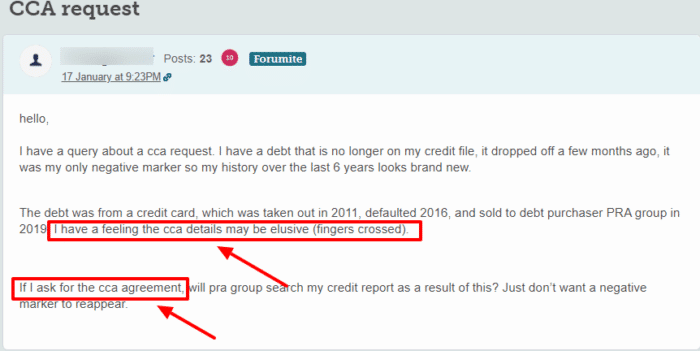
Keep in mind that if your creditor can’t produce the CCA agreement, the debt is unenforceable until they find it. Also, your credit score won’t drop simply because you requested a CCA. What actually hurts your credit rating is the unenforceable debt being recorded on your credit file.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
What if they do send a copy?
The credit card company or loan provider should reply to your letter with a true copy of the original which is clear to read. It must include all of the original terms and conditions relating to the credit agreement.
However, the true copy does not have to include a date or your signature.
You may be disheartened to learn after receiving the CCA agreement that they still have a copy, meaning the debt can still be enforced.
But you may choose to go down another avenue and ask for the business to freeze interest for a couple of months so you can get back on track.
They do not have to accept your proposal, but some bodies encourage them to do so. They are more likely to accept if you can prove financial difficulty, such as losing your job.
Can a debt be enforced without one?
Now here’s the good news!
If creditors cannot provide you with a copy of the agreement, presumably because they no longer have it, any debt relating to that agreement can no longer be legally enforced.
The debt will still exist on your account, and your credit report, but the creditor is not able to ask the court to make you pay – and subsequently cannot enforce your debts with bailiffs.





