Debt Info

What Happens If You Lose In Small Claims Court?

Scott Nelson MoneyNerd Janine Marsh MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Founder of MoneyNerd

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
&
Janine
Janine Marsh MoneyNerd

Janine Marsh

Former MoneyNerd Contributor

Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.

Learn more about Janine
· Oct 16th, 2026

Advertisement

Request a call from The Debt Advice Service

Total amount of debt?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Lose In Small Claims Court

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.

Are you having a tough time after losing in small claims court in the UK? Don’t worry; this article is here to help. Each month, we guide over 170,000 people on debt solutions, just like this.

In this article, we’ll explain:

  • What small claims are and how the court works.
  • The costs involved in going to small claims court.
  • What happens if you ignore a small claims notice.
  • How to deal with the legal fees of the winning party.

We understand how hard it can be. Sometimes, you may worry about being unable to pay for the judgement. We’ve been there, and we know what it feels like, which is why we’re here to give you the best advice possible. Let’s find out more about your options after losing in a small claims court in the UK.

Advertisement

Request a call from The Debt Advice Service

Tell us how much debt you have to continue to the enquiry form. Options depend on your circumstances.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

What if I lose?

If you lose a small claims case, you’ll be ordered to pay the money to the claimant. But this won’t be all you might have to pay.

You could also be ordered to pay some of the expenses the claimant has suffered from having to take legal action. 

Keep in mind that a County Court Judgment (CCJ) can affect your ability to secure loans, mortgages, and other forms of credit in the future. This is because a CCJ is added to your credit history for all lenders to see.

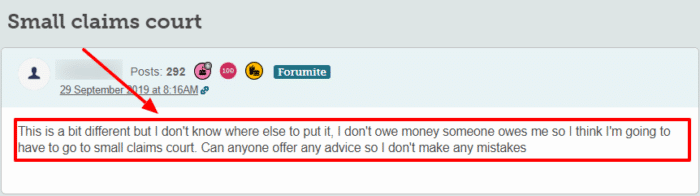
what happens if I lose in small claims court
Source: MSE Forum.

On top of having to pay the amount claimed, there are additional costs of losing in a small claims court.

You could also be liable for paying the claimant’s legal costs (except solicitor’s fees), court fees, travel expenses and even their lost wages from having to attend court. 

This means losing in a small claims court can get much more expensive than the original amount you were being chased for. 

Advertisement

How the introduction works

The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.

Options depend on your circumstances. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Remember, you can appeal the judge’s decision if you disagree with it. Appealing a small claims court decision is only possible within 21 days of the court’s decision.

There’s a fee involved, and you must also ask the court’s permission to lodge an appeal.

If you’re being threatened with small claims court, it might be wise to explore the different debt solutions and resolve the matter swiftly. 

Advertisement

Debt advice: Continue to the debt enquiry form

Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.

How much does it cost?

If you want to take someone to court over a small claim, you’ll have to pay an issue fee and a final hearing fee. These fees increase based on how much money you’re claiming, including any interest. 

For example, someone claiming £3,000 will have to pay a more expensive issue and final hearing fee than someone claiming £300. 

The issue fee is the cost of starting the small claim. It may be all that is required to convince the other party to pay.

An issue fee ranges from £35 to over £450. And the final hearing fee, which must be paid by a deadline, can cost from £27 to £346. These fees are subject to change.

If you need help with small claims court fees, you should apply for help. You may be eligible for a fee waiver if:

  • You have low or no savings.
  • You get benefits such as Jobseeker’s Allowance, Employment and Support Allowance, Income Support, Universal Credit, or Pension Credit.
  • You’re on a low income.

You may also apply to get some or all of fees back if:

  • You paid the fee in the last 3 months.
  • You were eligible for help when you paid it.

Advertisement

How the introduction works

The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.

Options depend on your circumstances. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

What happens if you win and they don’t pay?

When a small claims court orders the defendant to pay, they have 14 days to do so.

There are many cases where the defendant loses the case but doesn’t pay. This is likely because they don’t have enough money to pay the money and maintain a basic standard of living. 

Claimants can first tackle this problem by gathering financial information about the other party, to identify the reason why they are not paying.

You can do this by getting a judge to order the defendant back to court to disclose their finances. With this information, you can progress with one of many options. 

But what are these options? Claimants could use:

  1. An Attachment of Earnings Order
  2. Enforcement Officers
  3. A Charging Order

Advertisement

About The Debt Advice Service

Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

1. Attachment of Earnings Order

If the claimant finds out that the defendant isn’t paying but is in employment and receiving a wage, they could ask for an Attachment of Earnings Order.

This is a special type of court order where the court instructs the defendant’s employer to send some of their wages directly to the court, which then passes the money to the claimant. 

This guarantees the claimant will eventually be repaid, providing the defendant remains in employment. If they change jobs, the Attachment of Earnings Order will still stand.

It’s a criminal offence not to inform the court of any new employment while subject to an Attachment of Earnings Order. 

2. Enforcement Officers

Another option is for the claimant to employ enforcement officers to recover the money or seize assets equal to the value of the sum owed and sell them to pay the claimant.

The court can allow this, and the (expensive) fees charged by the bailiffs can be passed on to the debtor. 

There are strict rules on how enforcement officers must behave when enforcing the court order and what assets they can and can’t take to sell. In England and Wales, the rules in force from 1 May 2026 normally require at least 14 clear days’ notice before a bailiff takes control of goods, unless a court allows a shorter period. A qualifying request from a debt advice provider, made before the notice expires, extends the minimum to 28 clear days, except for non-eligible business debt. The changes do not affect enforcement action taken before 1 May 2026. Check the deadline on your notice and seek free debt advice promptly.

3. Charging Order

If the claimant finds out that you own your own property, they could instead make sure the money is eventually repaid by asking for a Charging Order.

This is when the money owed is attached to the property as a debt, meaning if the property is sold, some of the sale proceeds must be used to clear the debt. 

A Charging Order doesn’t necessarily mean you have to sell your home, but the claimant could ask for an Order of Sale, which could mean having to sell the property to clear the debt. 

Advertisement

Request a call from The Debt Advice Service

Tell us how much debt you have to continue to the enquiry form. Options depend on your circumstances.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine Marsh MoneyNerd
Debt Expert
Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.