


Unpaid Credit Card Debt After Seven Years: Is It Still Enforceable?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
There is no general rule that UK credit card debt disappears after seven years. Whether an old debt can be enforced depends on the law that applies, when the right to sue arose, any payments or acknowledgements, and whether court proceedings or a judgment already exist.
In simple words, we’ll answer important questions that may be on your mind:
- Does my debt become unenforceable after 7 years?
- Can I write off some of my debt?
- What can a creditor do if my debt has become statute-barred?
- How does this affect my credit score?
- Where can I get free, honest advice?
You’re not alone; loads of people have these worries. In fact, over 170,000 people visit our website each month for guidance on debt solutions.
We understand how dealing with unpaid credit card debt can be tough. But, we’re here to help you understand your situation better and find ways to manage it.
Will My Debt Become Unenforceable After 7 Years?
A credit-report retention period and the legal time limit for a court claim are separate. Do not apply a seven-year rule from another country to a UK debt.
For many credit card claims in England and Wales, the ordinary limitation period is six years. Scotland generally uses a five-year prescription period for relevant consumer debts, subject to its own conditions. Northern Ireland has separate rules.
For an England and Wales credit card debt, establish the legal cause of action rather than simply the date the account was opened or the credit-file default date. A compliant Consumer Credit Act default notice can matter to when the creditor became entitled to claim the balance. Check:
- The agreement and relevant default notice, including when the required remedial period expired.
- Any payments made before limitation expired.
- Any qualifying written, signed acknowledgement of liability.
- Whether a court claim was started in time or a judgment was already made.
The start date and effect of later events can be legally technical. Ask a debt adviser to check the records before deciding the debt is statute-barred.
A qualifying payment or acknowledgement before expiry can restart the period. A creditor’s own letter, phone call or sale of the debt does not by itself reset limitation.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
A default on a credit report is not the same as the statutory default notice required for certain action under a regulated credit agreement.
A statutory default notice sets out the breach, what must be done and a deadline to remedy it. Check the actual notice and seek advice if the amount or procedure is disputed.
For a regulated credit agreement, the notice must normally allow at least 14 days after service to remedy the breach before the specified action can be taken. Expiry does not automatically produce a CCJ: the creditor must use the court process.
An existing CCJ does not disappear because six years pass. Permission is normally required for a warrant or writ of execution after that period, while other enforcement methods have different rules. Get advice about the actual judgment and proposed enforcement.
Do not calculate limitation by adding six years to a credit-file default date. The legal start date may differ, and a timely claim or a payment or acknowledgement can affect the result.
The Debt I Owed has Become Statute-Barred. What Should I Do?
Keep records supporting your position. If court papers arrive, respond by their deadline even if you believe the debt is statute-barred.
If a creditor demands payment and you believe the debt is statute-barred, ask an adviser to help you dispute it in writing without admitting liability. State that you will not pay because the relevant time limit has expired.
If the creditor disagrees, ask for the dates and documents it relies on, including payment records, acknowledgements and any court claim or judgment.
Do not rely on a blanket statement about who must prove the case. A creditor must substantiate its claim, but you need to raise a limitation defence properly and comply with the court’s procedure if proceedings are issued.
Complain to the business first if it does not handle the dispute properly. Eligible financial-services complaints can then go to the Financial Ombudsman Service. The FCA can receive reports but does not resolve individual compensation claims.
Bank statements, account records and earlier correspondence may help establish dates. A credit report alone cannot tell you whether a debt is legally enforceable: defaults normally disappear after six years even where liability remains.
If the dates are uncertain, the next steps are:
- Get free advice from an organisation such as National Debtline or Citizens Advice before making a payment or admitting liability.
- Gather the agreement, default notice, statements and any court papers.
- Request information in wording that does not unnecessarily acknowledge the debt.
- Deal with any court deadline separately; asking the creditor for records does not extend it.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Is There Anything My Creditor can Do if My Debt has become Statute-Barred?
In England and Wales, once the right of action is already statute-barred, a later payment or acknowledgement does not revive it. The debt itself generally still exists. Scottish prescription can extinguish the obligation.
For firms and debts within scope, FCA rules restrict recovery of statute-barred debt. A firm must not continue to demand payment once you have said you will not pay because the debt is statute-barred, and it must not mislead you about its ability to take court action.
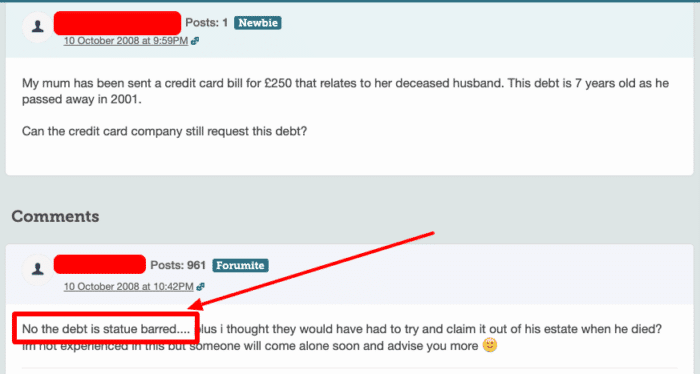
A creditor may still issue a claim, and a default CCJ can follow if you do not respond. Limitation normally needs to be raised as a defence; it is unsafe to assume the court will identify it automatically.
Other categories of debt and non-court recovery powers can have different rules. This article’s ordinary credit-card limitation explanation should not be applied automatically to tax, benefit overpayments or mortgage debt.
If the debt is enforceable but unaffordable, an adviser can help you assess repayment and insolvency options. Do not agree to payments that leave too little for essential bills.
References
FCA CONC 7.15: statute-barred debts
Limitation Act 1980, section 29: acknowledgements and part payments
National Debtline: statute-barred debts in England and Wales





