What are the Pros and Cons of Debt Consolidation


Debt consolidation is a common way to manage money troubles in the UK. It means putting all your debts into one, which could make it easier to keep track of payments. However, it might not be the best choice for everyone. This article will help you understand the good and bad points of debt consolidation.
We know that it can be hard to pay off debts and it can be worrying to think about how unpaid debt might affect you. We also understand that choosing the best debt consolidation loan can be confusing.
Here’s what we’ll cover in this article:
- How debt consolidation works.
- The types of debts that can be included.
- The benefits and drawbacks of debt consolidation.
- When debt consolidation might be a good idea.
- How debt consolidation can affect your credit score.
This guide explains the main trade-offs so you can discuss your circumstances with a free debt adviser.
Let’s dive in and talk about your options.
Advantages and Disadvantages
Debt consolidation might be the best debt management strategy for you – or it might not be.
Understanding the pros and cons of debt consolidation and considering them against your personal circumstances will help you make the right decision.
If you’re considering debt consolidation today, weigh up the potential benefits and disadvantages first. Here’s what to consider.
What are its benefits?
#1: Easier to budget and manage
If you consolidate debt, you are making it much easier to budget for your new repayment than paying off multiple debts and credit card balances each month at different times.
A single payment can simplify administration, but it does not guarantee an affordable budget or prevent missed payments.
#2: Protecting your credit score
Paying on time matters, but taking out new credit and changes to balances or accounts can also affect your credit profile. Consolidation is not guaranteed to protect or improve a score.
If you plan to apply for a mortgage, consider how the new borrowing and monthly commitment could affect affordability.
#3: Potential lower monthly payment
Compare the total amount repayable, interest, all fees, the term and early-repayment charges. A lower monthly payment can mean a longer term and a higher total cost. Securing previously unsecured debt against your home puts the property at risk if you cannot keep up repayments.
The interest rate you get will influence this, but you should always be aware of other possible additional fees.
Some people reduce total costs; others pay more. Compare the actual offers with the cost of continuing the existing debts.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
What are the disadvantages?
#1: It’s not available to everyone
Even if consolidating your debts would be the best choice for you, it may not be available to you.
People with a poor credit history might not be able to get one of these loans in the first place. A lender may be unwilling to lend further credit to you if you have a poor credit rating.
Considering consolidation does not by itself mean your credit score is poor. People use it for different reasons.
#2: You might pay back more
Debt consolidation will not guarantee that you will get a loan with lower interest.
You may have to pay back more than you are doing now. Or you may pay back less each month but have to pay back more over the life of the loan.
One payment may simplify administration, but it does not prevent default. Weigh that convenience against any increase in total cost and risk.
As you can tell by the advantages and disadvantages of debt consolidation, the financial aspect can be highly dependent on personal circumstances and the loan interest rate you qualify for.
#3: Additional fees and charges
A debt consolidation personal loan or balance transfer credit card may include additional fees and payments that you wouldn’t have to pay if you didn’t consolidate your debts.
This is more relevant to a balance transfer credit card, which typically includes a balance transfer fee.
Enquire about borrowing options through Loans Warehouse
Is it right for you?
Weighing the advantages and disadvantages of debt consolidation and considering your personal situation is the only way to know if it’s the best debt management option for you.
Unfortunately, there is no fixed answer for everyone, but the points discussed in this article should offer a fantastic place to start.
The good news is that we have lots of tips on debt consolidation here on MoneyNerd. If that’s not enough, there are other free and insightful resources online, especially by many UK debt charities.
But again, it is always best to get support from an independent debt charity or debt management company. They can guide you to a debt-free life again.
The best free debt advice organisations to contact include:
When is consolidating a good idea?
Consolidation may help when the new arrangement is affordable and offers a worthwhile improvement after all costs and risks are compared. See related guidance.
A lower monthly payment alone is not sufficient: extending the term can increase the total paid.
Check the personalised rate, fees, term and total repayment, not an attractive headline rate alone.
Compare borrowing with a budget review, creditor arrangements and other debt solutions through free advice.
Even though you might not be able to reduce monthly payments, having just one repayment can make managing your money easier.
However, there may be times when other debt management solutions (e.g. DMP, IVAs, etc.) are better. Credit counselling and debt charities should be your first point of call when needing advice.
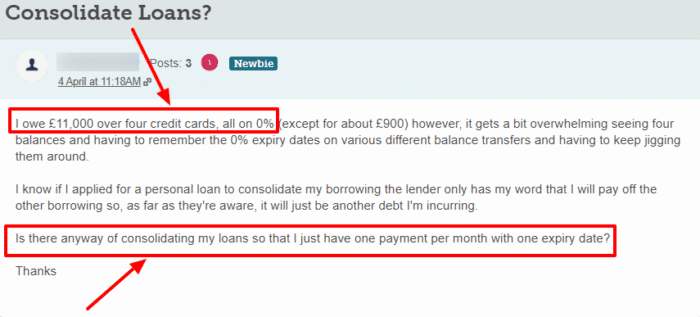
A suitable 0% balance-transfer card may reduce interest, but eligibility, transfer fees, the credit limit and the rate after the offer matter. It is not automatically the best option and the balance still has to be repaid.
Do THIS before applying!
Now that you understand the advantages and disadvantages of debt consolidation, you may have decided that this method can help you.
But, before you find a loan provider and apply, you should check your credit file for errors. Spotting an error and having it removed could be the difference between being accepted and rejected.
You can access your credit history online using a credit reference agency website (e.g. Experian or Equifax).
If you see a mistake, report it to the company that made it and ask them to remove it.
If they don’t cooperate, you can then ask the credit reference agency to remove it for you. And if the CRA you used offered you a free trial, don’t forget to unsubscribe, or you will be billed.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
When is it bad?
Debt consolidation would be a bad idea if you can only access a loan with higher interest. This will cause you to pay more each month or pay significantly more over the life of the loan.
It’s also not a good idea if there are more suitable debt management solutions available.
One of the cons of debt consolidation is that it can give the feeling to the debtor that they have immediately paid off a chunk of their debt.
It gives the illusion that they are in a far better financial position than before, even immediately after consolidating debt. In reality, at such an early stage, they are in a similar position, and they are still vulnerable to a financial emergency.
Moreover, debt consolidation does not solve underlying issues for which some people got into debt in the first place. Of course, this does not apply to everyone.
Overspending after consolidating debt is not uncommon and is one of the biggest reasons why debtors who take this strategy can get themselves into bigger debt down the line.
Even after debt consolidation you will need to monitor your finances closely and use a monthly budget.
Does it affect your credit score?
Debt consolidation can affect your credit score and report.
A hard search, new account, changes in balances and payment history can all have an effect; missed repayments are not the only factor.
Doing so causes each lender to leave a search mark on your file (hard search). Having too many of these searches in a short period can harm your file. This is because it appears like you are erratically applying for credit without giving it careful thought.
Reliable repayments may help your profile over time, but improvement is not guaranteed and an unaffordable loan can make matters worse.
Alternative Solutions
Some of the other ways that people reduce their debts and make them more manageable is using:
- The snowball method: This involves paying off the minimum payment on each debt and then using any remaining money to clear one debt at a time.
- Debt Relief Order: a formal solution for eligible people with low income and limited assets, writing off included qualifying debts after the moratorium if conditions remain met. It is not available to homeowners and excluded debts remain payable.
- Individual Voluntary Arrangement: a formal agreement supervised by an insolvency practitioner, not a new loan. Term, fees, included debts and write-off depend on the approved arrangement and successful completion.
- Full and final settlement: a creditor may agree to accept less than the balance. Obtain written acceptance and advice about credit-record and other consequences before paying.
- Bankruptcy: a formal insolvency option with significant asset, credit and other consequences. Get free debt advice to compare its suitability with alternatives.