


Average Retirement Savings UK


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
How much money should you have saved when you retire? The average retirement savings in the UK is £61,897. This article will help you understand more about this figure and what it means for your future.
You might be worried about the amount of money you need to retire. That’s okay, a lot of people feel the same. In fact, over 170,000 people visit our website each month to get advice on topics like this.
In this article, we will cover:
- How much money you really need in your retirement savings
- What is a state pension and how does it work
- What are final salary pensions
- What are pensions that are purchased with money
- How to legally write off debt
The team here at MoneyNerd knows what it’s like to worry about money; some of us have been in your shoes. We hope that this article will help you feel more confident about your retirement savings.
How much do you really need?
It is important to think about your pension income in stepping stones – first with the state pension, then with your private or workplace pension savings, and then with any other additional income you might get, whether from investments or property.
Thinking about your pension income in this way will help you plan for its future.
In 2018/2019, the average state pension was £176 a week.
State pension
When you reach the age of state retirement, which is currently 66 years old for both men and women, the government will contribute a sizable amount to your post-retirement income.
However, not everyone receives the full amount of the new state pension, which is £185.15 per week in 2022-23.
People who became eligible for the pension on or after April 6, 2016, will receive the full amount of the pension.
A man who became eligible for the state pension after April 2016 received an average of £170.36 per week, which equated to £8,859 per year, in May 2021.
A woman received an average of £164.32 per week, which equated to £8,545.00 per year.
17% of Brits aged 55 and over have no private retirement savings.
How the introduction works
Continue to the enquiry formThe Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Final salary pensions
The type of private pension you have will determine how much additional income you need to generate from your retirement savings in order to meet your financial obligations.
You will receive a predetermined amount of money on a monthly basis if you have a defined benefit or a final salary pension. The amount that you receive is determined by the amount of money that you earned while you were employed.
If you own one or more of these, you should receive annual updates that outline the amount of money you can anticipate receiving.
When you factor in your state pension, which you can determine by requesting a forecast of your state pension, you will have a better idea of how much financial flexibility you will have once you reach retirement age.
69% of pensioners have a private pension income.
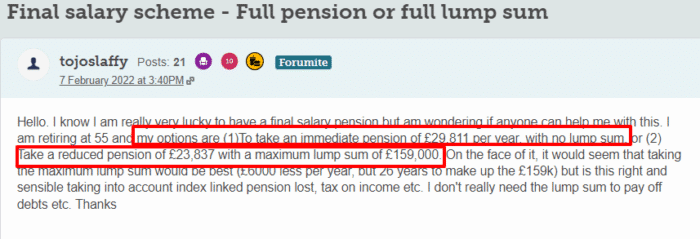
Remember, defined benefits pension at retirement may be provided as an income or as a tax-free cash lump sum and an income. You might also be able to delay taking your pension, which means you get a higher income when you do take it. Check your scheme for details.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Pensions that are purchased with money.
A money purchase pension, also known as a defined contribution pension, is one in which your pension payments are invested in a pool of money.
When the time comes for you to retire, you will need to decide how you will continue to make money.
You have the option of withdrawing the entirety of your pension pots at once. However, doing so will place the onus of ensuring that the money lasts squarely on your shoulders, and it will almost certainly result in a sizable tax bill.
When it comes to taking money out of their pensions, the majority of people who have these pensions will choose either income drawdown or an annuity, or sometimes a combination of the two.
If you want to have a pension of £28,000 a year from an annuity, you need to have pension savings of £204,750.
If you want a pension of £45, 000 a year from an annuity, you need savings of £664, 450.
The graph below shows the annual pension you need to live on for essentials, to be comfortable, or to live in luxury.
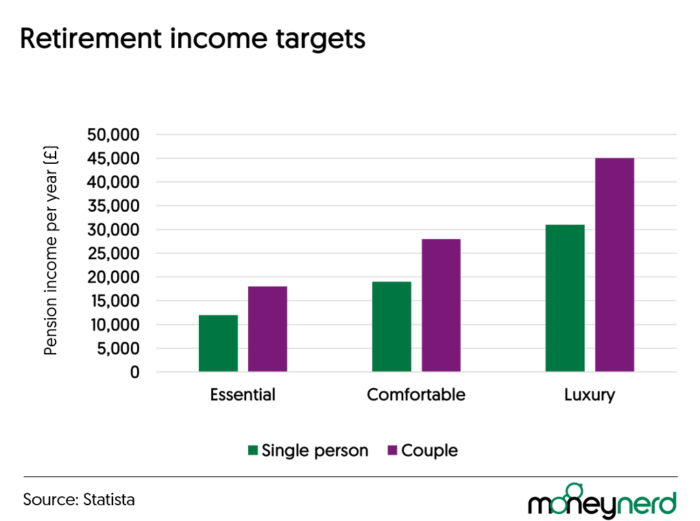
Source: Statista showing the target pension income to live for essentials, comfortably and to live in luxury for both single people and couples.
It can be difficult to think about how much money you need to put aside for a comfortable retirement, especially in your younger years when you have other costs such as childcare to think about.
However, it is never too early to start thinking about your retirement and planning ahead – especially as the earlier you start saving, the smaller the monthly contribution you need to make. Tax-efficient savings products like the best UK ISAs can also play a role here.”
As you get older, you should see an increase in the amount of money you bring in each month, and if you participate in a company pension plan, your employer will likely make a contribution to help you reach your goal amount.
A minimum of 8% must be paid into your pension each month in accordance with the rules of pension auto-enrolment. Of this amount, 5% must come from you, and 3% must come from your employer.
If you earn the average salary in the UK of £28,000, you will have savings of £186 every single month.
Women’s annual pension incomes are, on average, £7,000 less than men’s.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.
Continue to the enquiry form
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Tax relief
The government likes to give you a bonus as a way of rewarding you for saving for your future by contributing to a pension during your working life.
This is done in order to encourage people to save for their retirement. This is accomplished through the provision of tax relief.
If you are eligible for tax relief on your pension, a portion of the money that you would have paid in tax on your earnings is instead deposited into your pension account.
If you were not eligible for this relief, the money would have gone to the government.
Your pension contributions are eligible for tax relief equal to the highest rate of income tax that you currently owe. So:
Taxpayers who pay the basic rate will receive a 20% reduction in the pension tax.
Pension tax relief of up to 40 percent is available to taxpayers who pay the higher rates.
Pension tax relief in the amount of 45% can be claimed by additional-rate taxpayers.





