Alternatives to an IVA: Debt Repayment and Insolvency Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
An Individual Voluntary Arrangement (IVA) is one way to deal with debt, but it may not be suitable or the least costly option. This guide compares alternatives using the rules for England and Wales. Different procedures and eligibility rules apply elsewhere in the UK.
In this article, we’ll explain:
- What an IVA is and how it works
- Other ways to manage your debt that could be better
- How to start using these other options
- What happens if you can’t pay your debts
- Steps to take if you’re struggling with debt
Our team is made up of people who have been in your shoes; they’ve faced debt challenges, too. We’re here to help make things a bit easier for you.
Let’s start learning about your options together.
Are IVAs the Best Option?
On successful completion, an IVA releases the debts covered by its terms. It also involves fees, credit consequences and obligations that can last several years. Failure can leave debts payable again.
There’s no lower limit on how much debt an IVA can deal with, and there’s no upper limit either. But IVAs aren’t free.
Compare the proposed fees and outcome with free repayment plans, a DRO and bankruptcy where eligible. A fixed debt amount such as £10,000 does not by itself determine whether an IVA is suitable.
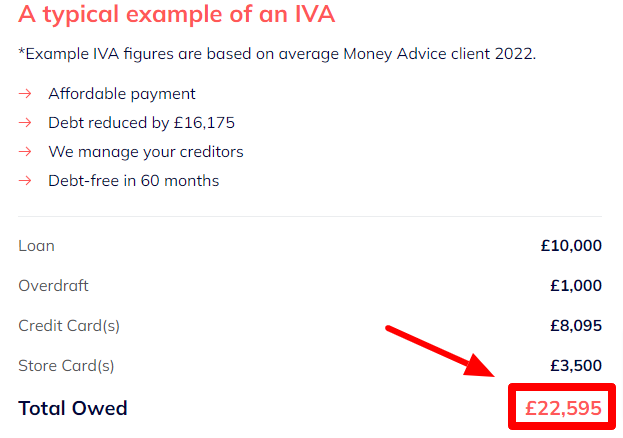
An example from a provider’s marketing material is not a quotation for your circumstances. Ask for a personalised written breakdown of contributions, fees, creditor payments and what happens if the arrangement fails.
Keep in mind that if you choose an IVA, an annual review will be conducted at the end of each year. The IVA annual review ensures that you are effectively managing IVA payments.
And of course, even if you do get an IVA, some restrictions come with it. These can ultimately affect your ability to get and secure certain things outside your IVA, like a mortgage.
So, if you don’t want an IVA, what other options are available to you?
Explore your debt options
Some formal debt solutions can write off eligible debts, but suitability depends on where you live, your debts, income and assets. Fees, restrictions and effects on your credit record may apply. Free, impartial debt advice is available from MoneyHelper. The enquiry form introduces you to our commercial partner; submitting it does not confirm that you qualify for any solution.
The First Step You Should Take
Start with an affordable budget and free debt advice. An adviser can help you decide which debts need priority, assess any disputed or old debts and prepare a suitable approach to creditors.
If you do this, you may find that you’re able to come up with an agreement to pay them back, or you can get an extension of time without ever having to go through all the hassle, stress and complications that come with finding a debt solution.
An informal agreement may be enough for a temporary problem, but it does not replace the legal protections of an appropriate formal solution.
If you need time to obtain advice, ask whether you qualify for Breathing Space.
In England and Wales, a standard Breathing Space can provide up to 60 days of protection from most enforcement, contact and added interest or charges on qualifying debts. A debt adviser must arrange it. It is not a payment holiday: ongoing liabilities and payments that remain due still need attention. A separate mental-health-crisis scheme has different rules.
Debt Management Plans
One of the alternatives to an IVA could be a Debt Management Plan.
Quite simply, this is an informal arrangement that you have with your creditors about paying off your debts. Crucially, though, you cannot pay off priority debts with a DMP.
DMPs normally cover non-priority unsecured debts such as credit cards, overdrafts and personal loans. Budget separately for rent, council tax and other priority commitments. Income-contingent student loans do not normally belong in a DMP; old mortgage-style loans need individual advice.
Administration Orders
Like an IVA, and unlike DMP, Administration Orders (AOs) are legally binding, which immediately means that they tick a box that DMPs don’t.
On the other hand, there must be certain boxes ticked in the first place before you can get an AO.
A personal administration order requires an unpaid County Court or High Court judgment, at least two creditors and the ability to make regular payments. The total debt must be within the £5,000 limit. The court decides the terms and deducts fees from payments.
Debt Relief Orders
A DRO can help people with limited assets and little spare income who cannot repay their debts. An approved intermediary must check eligibility and submit the application; it is free in England and Wales.
DROs can be used if you:
- The debts counted for DRO eligibility must total no more than £50,000.
- You cannot own your home.
- Counted assets must be within the £2,000 limit, with a separate £4,000 vehicle limit and other exclusions.
- You must have no more than £75 monthly spare income after reasonable household costs.
- You need the required England and Wales connection, no current IVA or bankruptcy, and no DRO within the previous six years. Other conditions also apply.
A DRO normally lasts 12 months. If it is not revoked, qualifying debts are usually discharged at the end. Report relevant changes in income or assets throughout the period; some liabilities, including fraud debts, can survive.
Criminal fines, most student loans and Social Fund loans are among the excluded debts. Listed qualifying debts are protected, but ongoing rent, bills and other excluded commitments remain payable. A DRO does not automatically prevent eviction for rent arrears. Ask the intermediary before changing payments connected to your home or essential goods.
Bankruptcy
Finally, you can declare yourself bankrupt if you can’t pay your debts.
Bankruptcy restricts recovery of debts covered by it, but secured creditors and excluded debts require separate attention. It can put a home or other assets at risk and affect some jobs.
Applying for your own bankruptcy in England and Wales costs £680. Instalments are possible, but the full application fee must be paid before submission. Different fees and procedures apply in Scotland and Northern Ireland.
Discharge is usually after 12 months. If you have income beyond reasonable living costs, an income payments agreement or order may run for three years; the amount is not necessarily small. Benefits-only income is not normally used for these payments. Asset administration can continue after discharge.
Compare the options with a qualified adviser before committing. A solution should cover the debts that need attention, fit a realistic budget and account for housing, assets and expected changes.
MoneyHelper’s debt advice locator can help you find free, independent advice.