Bailiffs and mental health: vulnerability and support


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
When dealing with bailiffs, it’s normal to feel worried, especially if you have mental health issues. It’s important to know that rules are in place to protect you. This guide will help you understand these rules better.
This guide covers bailiff enforcement in England and Wales and the support available if mental health problems make it harder to deal with debt. It explains:
- What bailiffs can and cannot do when dealing with someone who has mental health problems.
- How to notify enforcement agents about your mental health issues.
- Understanding bailiff fees and how they can affect your debt.
- Steps you can take if you believe a bailiff has not treated you fairly.
- How to manage overwhelming debt and the possibility of getting some of it written off due to mental health.
Our team knows how hard it can be to deal with debt and bailiffs. We understand what you’re going through and can provide useful advice based on real-life experiences. So please read on, and start taking control of your situation today.
The Link Between Mental and Financial Health
If enforcement is affecting your health, ask a free debt adviser to help you contact the creditor and enforcement company. Avoid taking out unaffordable credit simply to meet an immediate demand.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
How a vulnerable person must be treated
The rules on taking control of goods, discrimination and reasonable adjustments may be relevant. A mental health diagnosis does not by itself prohibit enforcement under the Mental Health Act.
Where a mental health condition amounts to a disability under the Equality Act 2010, reasonable adjustments may be required. Explain what change would help, such as accessible communication or contact through a representative. See related guidance.
Bailiff conduct with vulnerable individuals must follow the law. Plus, they must take into account the rights of vulnerable people with debt.
» TAKE ACTION NOW: Fill out the short debt form
Tell the enforcement company about your circumstances
See this post that someone placed on a popular online forum.
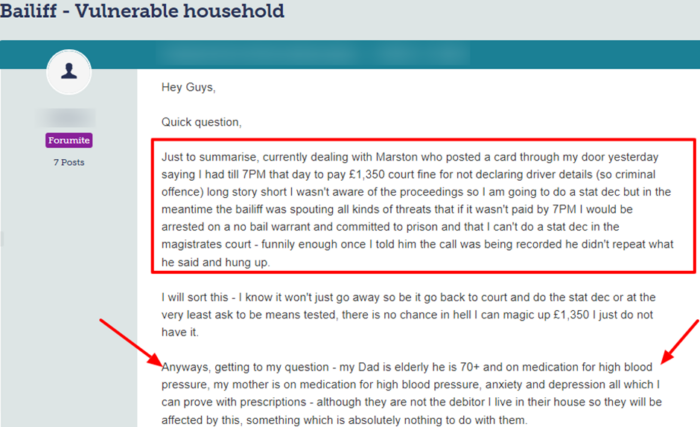
Source: Moneysavingexpert
Can you complain about them?
| Bailiffs may | Important limits |
|---|---|
| Visit under a valid enforcement power | Normally at least 14 clear days’ notice is required before taking control of goods; courts can shorten notice. An eligible debt-advice request can extend it to 28 clear days. |
| Take non-exempt goods belonging to the debtor | They cannot take ordinary essential household items or someone else’s property. Some jointly owned goods may be affected. |
| Take a vehicle where legally permitted | Ownership, finance, disability and other exemptions must be checked. ANPR does not remove those limits. |
| Enter through a door when lawful | For ordinary civil debts they usually cannot force first entry to a home. A CCJ by itself is not a power to break in. |
| Enter into a controlled goods agreement | Ask for a clear inventory and terms; breaking an agreement can have serious consequences. |
| Sell goods under the enforcement rules | Notice and sale requirements apply. Get advice if you dispute ownership, exemption, entry or fees. |
England and Wales only. Tools and equipment needed personally for work, study or education have a combined exemption limit of £1,350. The rules differ elsewhere in the UK.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Can you get debt written off?
In short, mental health and debt forgiveness are not written in stone.
References