


Central Debt Recovery Unit Letters: Check the Creditor


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Received a letter using the name Central Debt Recovery Unit? Check who currently owns the account and whether the sender is genuine before making a payment.
We understand that you may be confused about this debt, questioning whether it’s legitimate, or worried if you can’t afford to pay. We’ve got your back.
In this guide, we’re going to share:
- Who Central Debt Recovery are and why they might contact you.
- How to find out if the debt is really yours.
- Ways to manage contact and seek support.
- How Central Debt Recovery might affect your credit score.
- What to do if you can’t afford to pay back the debt.
If the letter worries you, ask for written account information and obtain free debt advice.
Let’s get started on understanding your next steps.
What are the reasons for contact?
A letter may concern an old account, mistaken identity or an unverified demand. It does not itself prove that you owe money.
Check the full legal name, company number and creditor on the letter. Contact the original creditor through independently verified details.
Older information associated this name with Metropolitan Collection Services. Companies House records Metropolitan Collection Services Limited, number 01475006, as dissolved on 18 August 2015. Do not treat its old address or phone details as current.
A company’s dissolution does not automatically cancel an underlying debt: a creditor or assignee may still have a valid claim. Establish the current creditor and legal position.
Typical Collection Process
The collection process depends on the debt and jurisdiction. A demand is not a County Court Judgment, and understanding the stages does not guarantee that a claim will be avoided.
| Possible stage | What can happen | What to do |
|---|---|---|
| Missed payments | The creditor or collector may contact you, apply contractual charges or issue required notices. There is no single timetable for every debt. | Check the debt and contact the creditor early. Prioritise essential bills and seek free debt advice. |
| Collection activity | Letters, calls or a proposed visit may follow. A collection agent has no power to seize your belongings. | Ask for identification and evidence of the debt. You do not have to let a debt collector into your home. |
| Letter of claim | A creditor may send a formal pre-action letter before making a claim. | Follow the response deadline and get advice; do not ignore it. |
| Court claim | In England and Wales, a creditor may apply for a county court judgment. A judgment and later enforcement are separate stages. | Respond to the claim by the court deadline, whether admitting it, disputing it or asking for time to pay. Attend if the court requires a hearing. |
| Enforcement after judgment | Where legally permitted, a creditor may seek enforcement such as an attachment of earnings, charging order or warrant of control. | Get advice promptly about the specific notice, available objections and affordable payment options. |
Is it yours?
You should clarify whether this is your debt before you start making payments to Central Debt Recovery Unit Debt Collectors.
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
Follow our ‘prove it’ guide with letter templates and get them to prove that you owe the money.
The required evidence depends on the type of account. A missing original agreement does not automatically establish that nothing is payable.
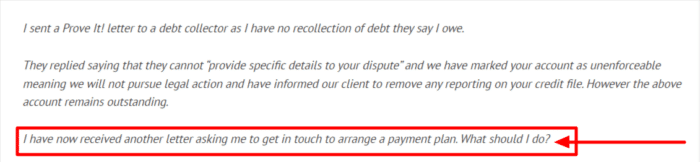
The forum example cannot determine whether another person’s debt is valid. If a letter appears to concern someone else, tell the verified creditor and request an investigation.
If you are in a similar situation, stay vigilant and check your correspondents. This is actually why we think that communicating via letter as much as possible is important – you can easily check to see what has been said.
Is my debt statute-barred?
Before paying an old debt, check both the evidence of liability and whether limitation or prescription affects it.
Many ordinary unsecured debts may become statute-barred after six years in England and Wales, or prescribed after five years in Scotland. The start date, debt type, payments, legally relevant acknowledgments and any court claim all matter. A creditor’s letter alone does not restart the period. Ask a debt adviser to check the facts before paying or admitting liability, and respond to any court papers on time.
In England and Wales, limitation can provide a defence to court recovery; it must be raised if proceedings arrive. Scottish prescription can extinguish an obligation, so the rules should not be described as identical.
Keep in mind that not all debts become statute-barred!
Court judgments and tax debts have separate rules. A CCJ does not expire merely because its credit-file entry disappears, but later enforcement can require permission or be subject to other restrictions.
If an adviser confirms that the relevant limitation rules apply, you can use an appropriate letter to explain the position to the current verified creditor. It is not a substitute for a court response.
If you are unsure about the status of your debt, you can contact a debt charity for some advice. Their advisors will be able to look at the debt in question, determine its status, and advise you on your next steps.
» TAKE ACTION NOW: Fill out the short debt form
How to deal with them
For regulated consumer-credit collection, a firm must treat customers in arrears with appropriate forbearance and consideration.
You can explain financial difficulty and ask for suitable contact arrangements. This does not guarantee that all correspondence stops.
Keep calm
It is important to have some perspective when dealing with your debt issues. Although it’s a difficult situation to deal with, debt problems can be resolved and it is best to stay as calm and composed as possible.
Check affordability before paying
If the debt is valid and enforceable, consider a sustainable arrangement with the verified creditor after allowing for essentials and priority bills. Do not pay an unverified recipient.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What if you can’t pay?
Tell the current verified creditor if you cannot afford payment, and ask a free debt adviser to assess the available options.
Ask whether recovery can be paused while you obtain advice. Get advice before paying or acknowledging an old debt, even by a small amount, because that can affect limitation.
Why are they continuing to contact you?
Ask whether the firm owns the debt or acts for someone else. Its role affects who can answer account questions and agree an arrangement.
Identify the purpose of the contact
Do not assume that repeated contact proves the debt or reveals how an employee is paid.
Keep correspondence so that you can identify the account, check previous replies and raise a specific dispute.
It’s their job
A collector can pursue a valid debt using lawful methods. Excessive, threatening or unreasonably timed contact may breach applicable rules.
Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
You can contact the Financial Ombudsman by phone on 0800 023 4567 or 0300 123 9123
Request suitable contact
For regulated consumer credit collection, FCA rules require firms to give due regard to reasonable requests about when, where and how they contact you. You can ask for letters or emails instead of calls and explain any health or accessibility needs. This is not an automatic ban on every call or required notice. Keep a record of unreasonable contact and complain if your request is not properly considered.
Keep evidence of unreasonable contact, including dates, times and what was said. Complain to the verified firm first.
Speaking to other people
A collector must protect your privacy and must not disclose a debt to an unrelated person without a lawful basis. Contact with someone you have authorised, such as a debt adviser, is different. Keep evidence of any improper disclosure and complain.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
When you can’t afford to pay it back
An IVA is a formal arrangement administered by an insolvency practitioner. Its approved terms govern contributions, assets and fees; only covered debts remaining on successful completion are released. It does not ban every required creditor communication.
An IVA can restrict borrowing, affect credit and involve fees and assets. Check its approved terms and compare alternatives with an independent adviser.
Will It Affect My Credit Score?
A collection letter alone does not create a new credit-file default. Credit effects depend on the underlying account and how it is reported.
Where a debt is sold, the reporting can change to show the new owner. It must not misleadingly present the same debt as two separate outstanding liabilities.
Check both the original creditor’s and any purchaser’s entries for accurate balances and dates.
The amount alone does not determine whether an account is reported.
A default normally remains for six years from its original default date. Sale or collection should not restart that period; non-defaulted closed accounts follow different timing.
A CCJ is a separate court record. Payment in full within one month can allow its removal from the register; later payment normally marks it satisfied while it remains for the usual six-year period.
Lenders make their own decisions using credit information and other checks.
Removal of an entry does not guarantee acceptance for credit and does not itself cancel an outstanding debt.
Debt solutions can affect your credit record, but the reporting rules depend on the solution and the dates of defaults or completion. Some insolvency entries can remain beyond six years if the arrangement is still active. Check your credit reports and ask your adviser which dates apply.
What else do you need to know
Use current regulatory guidance and the verified firm’s complaints process if you believe collection conduct is improper.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
How do I make a complaint?
An ordinary debt collector has no right to force entry or seize goods. A visit must comply with applicable contact and privacy rules; there is no blanket ban on every doorstep visit. FCA rules prohibit workplace visits without prior consent for regulated consumer-credit collection.
Complain to the current verified firm or creditor responsible for the conduct. Do not send personal information to an obsolete address merely because an old company name appears online.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
How to Find the Current Contact
| Historic company | Metropolitan Collection Services Limited, company number 01475006, was dissolved on 18 August 2015. |
| Current creditor | Check the creditor and any assignment or agency details on genuine correspondence; verify them independently. |
| If the account is with HSBC | Use HSBC’s official support and contact routes to check the account and collection instruction. |
| Payment or complaint | Use current details confirmed by the creditor, not an unverified number, link or historic collection address. |
References





