


Chandlers Bailiffs: Your Rights, Fees and Payment Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
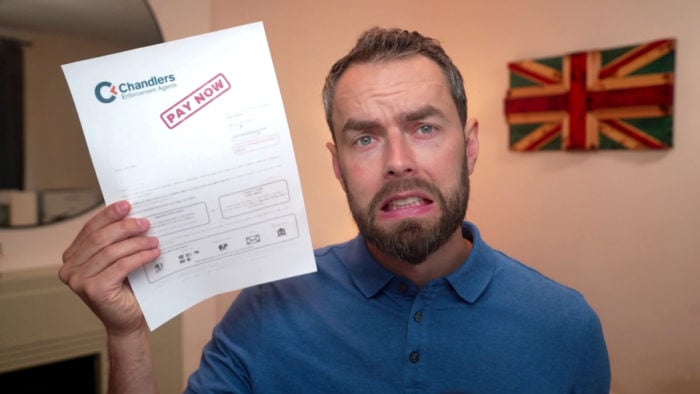
Are you feeling worried due to a letter or a visit from Chandlers Enforcement Agents? We understand your concerns. You may be stressed about your belongings being taken away or unsure about dealing with bailiffs. We’re here to help.
This guide explains enforcement in England and Wales. If you have received a notice, check its deadline promptly and obtain free debt advice if you are unsure what to do. The guide covers:
- Who Chandlers Limited are and why they are getting in touch.
- How to check if the debt they claim is really yours.
- What to do if the debt is disputed or you need an affordable payment arrangement.
- Your rights if Chandlers Limited have taken your goods.
- Steps you can take if you’ve been contacted by Chandlers Limited.
Dealing with enforcement can be stressful. Use this guide to check the notice and understand when to obtain individual advice.
Let’s get started on finding a way to make the situation easier for you.
Why Are They Getting in Touch?
» TAKE ACTION NOW: Fill out the short debt form
What Actions Should You Take?
Speak to them
An agent must not misrepresent their powers or threaten action they cannot lawfully take. Council tax and penalty enforcement are governed by enforcement legislation; FCA consumer-credit rules do not apply universally to all bailiff activity.
Get confirmation of the debt
A prove it letter can help request information, but does not itself stop enforcement or extend a deadline. Council tax and statutory penalty debts do not depend on a signed consumer credit agreement. Failure to produce such an agreement does not cancel a liability order or warrant. Check the actual legal basis of the debt and the available review or court procedure.
Statute-barred debt
Some unsecured contractual debts in England and Wales have a six-year time limit for starting court proceedings, normally measured from when the creditor could sue. A payment or qualifying signed written acknowledgment before expiry can restart the period. A conversation alone does not restart it, and court proceedings begun in time can change the position.
Scotland has different prescription rules: certain debts are extinguished after five years without a relevant claim or acknowledgment, subject to the applicable rules. This is not the same as the England and Wales limitation defence. Ask an adviser to check the debt type, dates and any court action.
Keep in mind that not all debts become statute-barred!
A debt with an existing judgment, council tax liability order or enforcement warrant cannot be assessed using a simple six-years-since-last-payment rule. Tax debts also have special rules. A judgment does not disappear when its six-year credit-file entry ends, although later enforcement may require court permission.
Get advice before using a statute-barred letter, making a payment or acknowledging an old debt. The adviser needs to check the debt type, relevant dates and any court action. See statute-barred debt letter template.
If you are unsure about the status of your debt, you can contact a debt charity for some advice. Their advisors will be able to look at the debt in question, determine its status, and advise you on your next steps.
Clearing the debt
How Do You Deal with a Visit from them?
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What Rights Do You Have if They Have Taken Your Goods?
The table below summarises bailiff rights. Apply it alongside the specific debt, enforcement authority and any protections relevant to your situation.
| Bailiffs may | Important limits |
|---|---|
| Visit under a valid enforcement power | Normally at least 14 clear days’ notice is required before taking control of goods; courts can shorten notice. An eligible debt-advice request can extend it to 28 clear days. |
| Take non-exempt goods belonging to the debtor | They cannot take ordinary essential household items or someone else’s property. Some jointly owned goods may be affected. |
| Take a vehicle where legally permitted | Ownership, finance, disability and other exemptions must be checked. ANPR does not remove those limits. |
| Enter through a door when lawful | For ordinary civil debts they usually cannot force first entry to a home. A CCJ by itself is not a power to break in. |
| Enter into a controlled goods agreement | Ask for a clear inventory and terms; breaking an agreement can have serious consequences. |
| Sell goods under the enforcement rules | Notice and sale requirements apply. Get advice if you dispute ownership, exemption, entry or fees. |
England and Wales only. Tools and equipment needed personally for work, study or education have a combined exemption limit of £1,350. The rules differ elsewhere in the UK.
How to Stop Them From Getting in Touch
Can I Get a Debt Solution?
If you have unsecured debts and are worried about paying them or a visit from Chandlers Enforcement, you might benefit from a debt solution.
There are several different debt solutions available in the UK, so I recommend speaking to a debt charity as soon as possible. Their advisors will be able to look at your finances in detail and help you work out which debt solution will work best for you.
I have linked a few charities that offer these advisory services for free below.
Debt Management Plan (DMP)
A Debt Management Plan can organise affordable payments towards suitable unsecured debts, but is informal and does not automatically stop interest, court action or bailiff enforcement. Priority debts need separate attention.
A DMP is informal and creditors are not bound by it in the same way as by a formal insolvency arrangement. Priority debts and existing enforcement require separate advice.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement with creditors. It can include agreed payments or other contributions and binds creditors covered by the arrangement once approved. Fees, effects on assets and credit, and the risk of failure need to be considered with an authorised insolvency practitioner.
An IVA can write off the unpaid balance of included debts on successful completion, subject to its terms. Excluded debts remain payable, and failure can leave you liable for remaining debt and further action.
There is no universal statutory requirement to owe several thousand pounds or have more than one creditor. Suitability depends on the debts, available income or assets, alternatives and the provider’s criteria.
Trust Deed
Scotland has different debt remedies, including protected trust deeds, the Debt Arrangement Scheme and bankruptcy. A trust deed is one option, not a compulsory replacement for an IVA; ask a Scottish debt adviser which options fit your situation. See trust deed guide.
A protected trust deed is a formal Scottish insolvency arrangement with conditions, costs and risks to assets and credit. Protection and discharge depend on its status and successful completion; it does not automatically cover every debt or prevent every type of contact.
Debt Relief Order (DRO)
In England and Wales, a Debt Relief Order may be available if qualifying debts are no more than £50,000, spare monthly income is no more than £75, assets are no more than £2,000 and any qualifying vehicle is worth no more than £4,000. Other conditions apply, including not owning your home. An approved adviser must assess eligibility. See Debt Relief Order guide.
A DRO normally gives 12 months of protection for the debts included in it. Ongoing bills and excluded debts still need to be paid. Follow your adviser’s guidance, especially where rent arrears or eviction are involved.
Included debts are normally discharged at the end of the DRO period if the order remains in force. Changes in circumstances must be reported and can affect the order; excluded debts are not written off.
Bankruptcy
Bankruptcy is a formal insolvency option with eligibility rules and serious consequences for assets, housing, credit and sometimes employment. It does not cover every debt. Get independent advice on all available options before applying.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish version of bankruptcy.
Scotland’s Minimal Asset Process is a form of bankruptcy for people meeting specific debt, income and asset conditions. It has consequences for credit and finances and should be assessed with an approved money adviser. See Minimal Asset Process guide.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How do I Complain?
Complain to the enforcement company and the creditor, identifying the conduct or charge you dispute. For a County Court bailiff employed by HMCTS, complain to the court. A complaint does not itself suspend enforcement or extend a court deadline. See CIVEA code of practice.
Follow Chandlers’ current complaints procedure and raise the matter with the instructing creditor where appropriate. Keep evidence and request a written response. A complaint alone does not stop enforcement.
CIVEA means the Civil Enforcement Association. Check the current complaints arrangements for the firm and any applicable independent scheme; membership and eligibility matter. Court complaints about certification are a separate process and can carry costs risks. The Financial Ombudsman Service is not a general appeal body for bailiff enforcement and does not fine bailiffs. The correct escalation route depends on the agent and creditor: it may involve an eligible enforcement complaints scheme, a council ombudsman complaint or an application to court. Obtain advice on the route and any deadline. See CIVEA complaints information.
Chandlers Limited Contact Details
| Website: | https://www.chandlers.ltd.uk/ |
| Post | Chandlers Limited, Office 7, 35–37 Ludgate Hill, London, EC4M 7JN. Check the official contact page before sending documents. |
| Phone number: | 0208 290 0866 |
| Contact information | Check the official website for current contact methods. |
| Email address: | [email protected] |
| Opening hours | Monday to Friday, 9.00 am–5.00 pm, excluding bank holidays, according to the official contact page checked on 4 October 2026. |
References
Schedule 12, Tribunals, Courts and Enforcements Act, 2007
Part 1, Regulation 10, Certification of enforcement agents, 2014.





