


Clydesdale Financial Services Debt: Barclays Partner Finance


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Clydesdale Financial Services Limited is the legal company behind the Barclays Partner Finance trading name. Check the account and contact independently if you receive an unexpected demand.
In this article, we will help you understand:
- Who Clydesdale Financial Services are.
- Why they might be contacting you.
- How to check if the debt is really yours.
- What to do if you can’t pay the debt.
- Ways to handle or even write off your debt.
This is a lender identity, not simply a generic debt collection agency. It should not be confused with Clydesdale Bank or Virgin Money.
The finance may relate to a retail or other purchase rather than an ordinary Barclays current account or credit card.
Use the agreement and account reference to establish what the correspondence concerns.
Why is Clydesdale Financial Services Contacting Me?
Do not assume the firm bought a discounted debt just because its legal name is unfamiliar.
Typical Debt Collection Process
Check whether the letter is a routine statement, arrears notice, complaint response or legal notice. These have different purposes and deadlines.
Here’s a table that explains each stage and action involved in this process. For more information, be sure to check out our specialized guide.
| Possible stage | What can happen | What to do |
|---|---|---|
| Missed payments | The creditor or collector may contact you, apply contractual charges or issue required notices. There is no single timetable for every debt. | Check the debt and contact the creditor early. Prioritise essential bills and seek free debt advice. |
| Collection activity | Letters, calls or a proposed visit may follow. A collection agent has no power to seize your belongings. | Ask for identification and evidence of the debt. You do not have to let a debt collector into your home. |
| Letter of claim | A creditor may send a formal pre-action letter before making a claim. | Follow the response deadline and get advice; do not ignore it. |
| Court claim | In England and Wales, a creditor may apply for a county court judgment. A judgment and later enforcement are separate stages. | Respond to the claim by the court deadline, whether admitting it, disputing it or asking for time to pay. Attend if the court requires a hearing. |
| Enforcement after judgment | Where legally permitted, a creditor may seek enforcement such as an attachment of earnings, charging order or warrant of control. | Get advice promptly about the specific notice, available objections and affordable payment options. |
Is it Wise to Ignore a Debt Collector?
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
» TAKE ACTION NOW: Fill out the short debt form
What if I Don’t Believe the Debt is Legitimate?
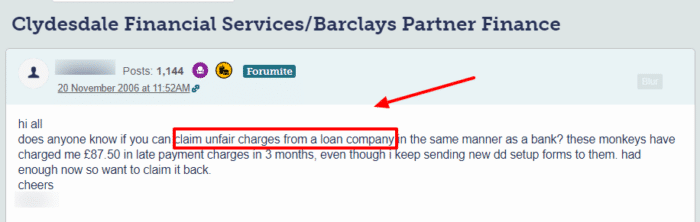
Query unexplained fees and interest. A charge needs a proper contractual or legal basis and must comply with applicable rules; it is not valid merely because it appears on a demand.
If you are in a similar situation, I recommend speaking to a debt charity. They will be able to take a thorough look at your circumstances and advise you on your next steps.
Free debt advice can help you check liability, deadlines and affordable next steps.
What Legal Action Can Clydesdale Financial Services Take if I Don’t Pay Back the Loan?
Will I Have to Go to Court?
Attachment of Earnings Order
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What if I Can’t Afford to Pay Clydesdale Financial Services Debt?
1. Talk through your options with Clydesdale
Different Debt Management Options
Snowball Method
Write-off debts
Get a refund on your Loan
Follow my free letter template to write to your creditor and express your concerns.
Debt Solutions
If you have tried the above options but got nowhere, or if you are experiencing significant issues repaying your unsecured debts, you may wish to consider a more formal debt solution.
There are several different debt solution options available in the UK, so I recommend speaking to a debt charity for some free debt advice. Their advisors will be able to walk you through your options in detail and help you find the best solution for you.
Credit-reporting effects vary by solution and account history. A DMP is not recorded in the same way as an IVA, DRO or bankruptcy, and default dates have their own rules.
The end of a reporting period does not guarantee new credit or mean all obligations have ended. Check the particular solution and entry.
Debt Management Plan (DMP)
A DMP is an informal debt solution that lets you pay off your debts via a single monthly payment.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is a formal arrangement administered by an insolvency practitioner. Its approved terms govern contributions, assets, fees and the creditors bound by it.
Many contribution IVAs run for five or six years, but terms vary. Only included remaining debts are released on successful completion; not every contact from a creditor is prohibited.
There is no universal statutory minimum amount or two-creditor requirement. An adviser should assess suitability against your circumstances and alternatives.
Trust Deed
IVAs are unavailable in Scotland. A protected trust deed is one possible option, alongside the Debt Arrangement Scheme and bankruptcy.
A protected trust deed follows Scottish rules, normally involving four years of contributions and consideration of assets. Release depends on completion and the debts covered.
Debt Relief Order (DRO)
A DRO may suit someone within the relevant debt, asset and surplus-income limits. England and Wales and Northern Ireland have different criteria.
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted. Keep paying essential ongoing bills and excluded debts; not every creditor notice is prohibited.
Report relevant changes during the DRO. Qualifying debts are normally discharged at the end if the order remains in force.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is Scottish bankruptcy. The Minimal Asset Process is a route for people meeting its conditions; its application fee has been removed. Seek approved Scottish money advice.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How do I Complain About Clydesdale Financial Services?
If you think that Clydesdale Financial has been unreasonable or behaved inappropriately, you can make a complaint. You can also make a complaint if you feel that they have broken any of the Financial Conduct Authority’s (FCA) guidelines.
Make your first complaint to Clydesdale Financial directly so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Use Barclays Partner Finance’s official complaint route and quote the finance reference. For motor-finance commission complaints, check the current FCA scheme and timetable because special rules may affect the normal process.
Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
Barclays Partner Finance Contact Details
| Telephone | 0800 152 2888 |
| Official website | Barclays Partner Finance |
| Before sending documents | Check the current postal or secure complaint route on the official website or verified account correspondence. The FCA lender list also provides contact details; a PO Box is not necessarily the registered office. |
Still Not Sure How to Deal with Clydesdale Financial Services Debt?
References




