Bailiffs

County Courts Act section 69: interest on debts and damages

Scott Nelson MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Debt Expert

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
· Oct 4th, 2026
Get debt advice from The Debt Advice Service

Total amount of debt?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.

Section 69 of the County Courts Act 1984 concerns the court’s power to award interest on debts or damages in England and Wales. It does not itself give a collector bailiff powers.

In this easy-to-understand article, we’ll explain:

  •  What Section 69 of the County Courts Act 1984 really means.
  • How interest claims differ from enforcement powers
  •  Ways to calculate the interest you might owe.
  •  Tips on how to avoid court action over debt.
  •  Advice on dealing with big debts.

We know it’s stressful when you’re dealing with bailiffs. Some of our team members have been in the same boat. But remember, there’s always a way out.

Here’s how you can handle the situation in the best possible way.

Could you legally write off some debt?

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

Answer a few questions to start your enquiry. Options available depend on your circumstances.

How much debt do you have?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

What is the County Courts Act 1984?

The County Courts Act 1984 governs aspects of County Court proceedings in England and Wales. It is not a single UK-wide court procedure and has been amended over time.

What is Section 69 of the County Courts Act 1984?
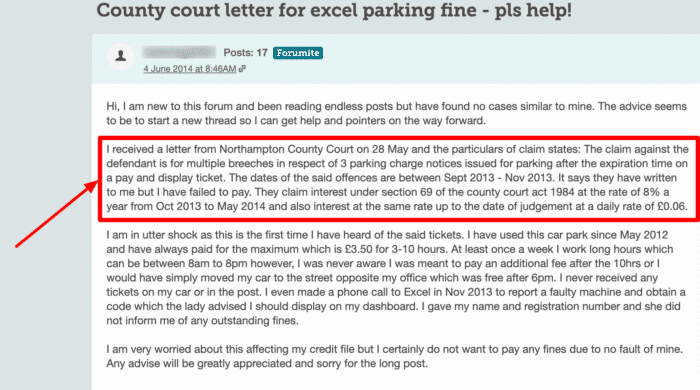
Section 69 allows simple interest to be included in a judgment for all or part of a debt or damages over an appropriate pre-judgment period. The court decides the rate and period under the law and rules; the section does not automatically award 8% on every debt.

Contractual interest and other statutory interest regimes can apply instead. Section 69 restricts overlap where interest already runs for the same period; post-judgment interest has separate rules.

Here, you can see this forum user on MoneySavingExpert has received a letter saying interest will be claimed against them as part of the County Courts Act 1984 Section 69 and they are looking for advice.

Understand your debt options

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.

Get Started

MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

What is the Commercial Debts Interest Act 1998?

The Late Payment of Commercial Debts (Interest) Act 1998 is a separate regime. For qualifying business-to-business late payments, statutory interest is generally 8 percentage points above the relevant Bank of England base rate, not a flat 8%. See related guidance.

The commercial late-payment regime concerns qualifying payments for goods or services and has conditions, including the effect of contractual remedies. It is not a general rule for all damages or consumer debts; a statutory entitlement can arise without first obtaining a judgment. See related guidance.

Is statutory interest simple or compound?

Section 69 interest is simple rather than compound. Qualifying commercial late-payment statutory interest is also calculated separately from any applicable contractual compound-interest clause.

The difference between simple and compound interest is that simple interest is calculated on the original (principal) amount, whereas compound interest is calculated on the original amount and on the interest already accumulated on it.

An illustration of simple interest at 8% a year

The following example assumes an applicable simple annual rate of 8%, a £500 principal and 100 chargeable days. It is not a statement that 8% applies to your debt or that commercial statutory interest is fixed at that rate.

Keep the daily calculation unrounded until the final result:

  1. Multiplying the total debt amount by 0.08
  2. Divide the answer to the above by 365 (= daily rate of interest)
  3. Multiply the daily rate of interest by the number of days the debt has been owed

» TAKE ACTION NOW: Fill out the short debt form

For example, if you have a debt worth £500 that you have owed for 100 days. The claim would be calculated as follows:

500 (money owed) x 0.08 = 40 (= annual rate of interest)

£40 ÷ 365 = approximately £0.109589 per day

£40 ÷ 365 × 100 = approximately £10.96

The illustrative interest is £10.96, subject to the legal entitlement, period and rounding method. It is not automatically awarded just because a creditor includes the figure in a letter.

If you genuinely owe money on a loan or credit card, you should aim to avoid legal proceedings. Making a late payment is not the end of the road, and you can still do plenty to avoid a court date and the risks of legal proceedings. 

Court fees, interest and recoverable legal or enforcement costs can increase the amount owed, but the rules limit what can be recovered. A claimant is not automatically entitled to every solicitor charge.

Bailiff enforcement requires the appropriate authority and can add statutory fees. The older £75 plus £235 figures are not a reliable current total: applicable fees depend on the enforcement type, stage, debt amount and transitional rules. See related guidance, related guidance.

Unpaid debts and legal actions could also have long-term financial implications, such as potentially affecting your credit score, so the way I see it, it is best to avoid them taking legal action if you can.

Take the first step towards tackling your debt

Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.

MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha

Very helpful and informative thank you

Get started

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.

For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.

How to avoid debt court action

Respond promptly to a genuine claim or demand. Negotiation can help resolve a debt, but does not automatically prevent proceedings or decide what interest is lawful.

  1. Negotiate a Payment Plan

Propose payments based on an accurate budget and ask whether interest and charges can be frozen. A creditor need not accept the exact proposal, and the agreement should be confirmed in writing.

A payment plan is only sustainable if it allows for essential living costs. Do not assume a smaller monthly instalment prevents further hardship or reduces total cost.

Before you agree to a repayment plan like this, ensure you have worked out an accurate budget. Only by knowing what you can realistically afford to repay can you commit to a new agreement with the confidence of not making the situation worse. 

We have a great budgeting 101 guide to help you do just that and to help you manage your money in the future, too.

  1. Consider free debt advice and available solutions

Free debt advisers can explain informal and formal options. Eligibility, fees, effects on assets and credit records, and exclusions differ between solutions.

There are a number of excellent charities acting on behalf of debtors to make debt recovery less stressful. 

Grab more info on our site’s dedicated debt solutions page!

  1. Engage a Debt Management Business

An IVA must be administered by an authorised insolvency practitioner. Free debt-advice organisations can still advise on suitability and may offer or refer to formal options.

IVA fees are normally paid through the arrangement. Do not assume that a fee-charging debt-management business is the only route or that an IVA necessarily saves money compared with suitable alternatives.

Using one has potential pitfalls, so make sure you understand the pros and cons of using a debt management business.

More assistance with late payment of commercial debts

If you are due to face legal action and want to know more about fixed interest entitlement among creditors, industry news or debt solutions, we recommend speaking with a registered charity offering advice services. 

You can find a registered charity online and their contact details on their website.  

Could you legally write off some debt?

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

Answer a few questions to start your enquiry. Options available depend on your circumstances.

How much debt do you have?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

