


Credit card debt after a spouse dies: who is responsible?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
How estate debts and personal liability differ, and why you should check before using your own money to repay a deceased partner’s credit card.
What Happens to Debt When You Die?
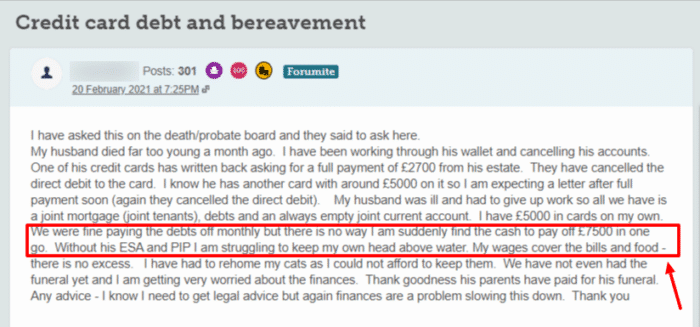
An executor or administrator normally pays valid estate debts from estate assets, not personal funds. However, mishandling an estate can create personal liability. Get professional probate advice before distributing assets or paying selected creditors if the estate may be insolvent.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
How Do I Pay It Off After They have Passed Away?
Notify the credit card provider of the death and ask its bereavement team for the balance and required documents. Give details of the executor or administrator, and ask how payments, interest and correspondence will be handled. Do not use the deceased person’s card.
Check whether any insurance was intended to repay the borrowing. The destination of a life-insurance payment depends on the policy, any trust and the ownership arrangements; it is not always paid outside the estate. Do not assume a payment received personally must be used for a debt for which you are not liable.
If the estate cannot pay all debts, obtain probate or insolvency advice before paying creditors or distributing assets. An insolvent estate has legal priorities that are not simply the same as a living person’s household budget. See MoneyHelper’s guide.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Joint Debts
An additional cardholder is normally not liable for the primary cardholder’s personal credit card balance just because they used an additional card. Check the actual agreement and any separate guarantee.
For genuinely joint borrowing, the surviving borrower will usually remain liable for the full outstanding amount under joint-and-several liability. The estate may also have a liability. Ask the creditor to explain the agreement and seek advice before assuming a debt has simply transferred or will be forgiven.
What Happens If I Don’t Pay?
We’ve all wondered – what exactly will happen if you stop paying off your credit card debt? Well, the answer is a whole lot of bother.
- Your creditor will send you reminders and then demands that you pay any missed payments
- If you don’t pay, your account will default
- If you still don’t pay your debts, your creditor can choose to sell your debt to a debt collection agency or employ an agency to chase you for the missed payments.
If you don’t pay the collectors, your creditor or the collection agency might be able to take legal action against you to get their money back. Legal action usually starts with a CCJ.
But remember that the above will only happen if the debt is yours or a joint debt that you shared with your spouse when they were alive.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Is it a Good Idea to Go to an Advisor for Help?
Free debt advice can help identify which debts are yours and what payments are affordable. Estate administration may also need a probate solicitor, particularly where assets are jointly owned, a guarantee exists or the estate is insolvent. Check the scope and any fees before engaging a service.





