


DCBL Debt Letters and Bailiff Notices: Your Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you worried about a DCBL Bailiffs Debt Letter? Maybe you’re scared that a bailiff might come to your home or take your things.
First establish whether the letter concerns ordinary debt collection or enforcement under a court writ or warrant. The DCBL name alone does not tell you which powers apply.
In this article, we will help you understand:
- How to check if the debt they say you owe is really yours.
- What steps you can take if you do owe the debt.
- How to deal with the DCBL Bailiffs in a calm, smart way.
- Your options if you can’t pay the debt.
Read the document and deadline before deciding what to do. Free debt advice can help if you dispute the account or cannot afford payment.
We will use our knowledge to help you make the best choices about your DCBL Bailiffs Debt Letter. So, take a deep breath and read on.
Why Are DCBL Contacting You?
DCBL may contact you about an alleged debt or an existing enforcement case. Verify the creditor, amount and stage rather than assuming receipt of a letter proves liability.
A collection letter does not confer bailiff powers. A Notice of Enforcement should identify the separate enforcement authority and debt; obtain advice promptly if one has arrived.
Do You Really Owe DCBL Bailiffs?
Sometimes debt collection companies can make mistakes or get the wrong person.
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
Ask for the account basis, balance and authority to collect. If a judgment or warrant already exists, ask for those details and advice on the proper court remedy.
Use a request to resolve a genuine uncertainty or dispute. A known debt does not need to be disputed simply to delay payment.
An evidence request does not automatically stop enforcement or extend a court deadline. Keep records and respond through the legal process already in progress.
We have ready-made templates you can use on this guide!
At this stage, you may also want to look for free debt advice from a UK debt charity.
Your Rights When Dealing with Bailiffs
If you’re dealing with DCBL bailiffs, it’s crucial to understand your rights. This way, you’ll prevent unfair treatment and other unpleasant situations.
We’ve put together this table that explains what bailiffs can and can’t do. For more information, be sure to read our detailed guide.
| Bailiffs may | Important limits |
|---|---|
| Visit under a valid enforcement power | Normally at least 14 clear days’ notice is required before taking control of goods; courts can shorten notice. An eligible debt-advice request can extend it to 28 clear days. |
| Take non-exempt goods belonging to the debtor | They cannot take ordinary essential household items or someone else’s property. Some jointly owned goods may be affected. |
| Take a vehicle where legally permitted | Ownership, finance, disability and other exemptions must be checked. ANPR does not remove those limits. |
| Enter through a door when lawful | For ordinary civil debts they usually cannot force first entry to a home. A CCJ by itself is not a power to break in. |
| Enter into a controlled goods agreement | Ask for a clear inventory and terms; breaking an agreement can have serious consequences. |
| Sell goods under the enforcement rules | Notice and sale requirements apply. Get advice if you dispute ownership, exemption, entry or fees. |
England and Wales only. Tools and equipment needed personally for work, study or education have a combined exemption limit of £1,350. The rules differ elsewhere in the UK.
Do You Have to Pay DCBL Enforcement?
You might have to pay DCBL if you really owe the debt, but there are times and situations when you don’t have to pay.
You can propose affordable repayment, but cannot unilaterally set binding payment terms or assume enforcement has been suspended.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
DCBL Bailiffs Proved the Debt, What Now?
A missing reply does not automatically cancel the debt or make it payable only after judgment. For an existing court order, use the appropriate payment or challenge procedure.
If the debt is correct, discuss an affordable payment arrangement or seek free advice about alternatives. Do not agree to payments that leave essential bills unpaid.
Our financial expert, Janine Marsh, advises: If a bailiff has proven you owe money and you don’t have cash to hand, you’re within your rights to suggest a payment plan.
Acceptance is not guaranteed. Get any agreement, including what happens to enforcement, confirmed in writing.
You should get the help of debt charities to help you work out what you can afford to pay and other options available to you.
A repayment plan with DCBL is not the only way to get out of debt in an affordable way.
A creditor may obtain a CCJ, including by default if court papers are ignored. Taking control of goods then requires a separate lawful enforcement step; a collection letter alone is insufficient.
» TAKE ACTION NOW: Fill out the short debt form
What should you do if you receive a DCBL final reminder?
The best thing to do here is not to ignore the situation.
A final reminder is not itself proof that the debt is correct. Check what has been supplied and whether there is an actual Letter of Claim, judgment or enforcement notice.
Only the court can issue a CCJ. The creditor or its legal representative may bring a claim; DCB Legal is a separate law firm from DCBL.
If you’re struggling to pay, there are many free debt charities such as:
- Citizens Advice Bureau (CAB) you can expect the very best help and support in dealing with your debt problems. The skilled and experienced advisors will give you their expert guidance on debt matters.
- StepChange provides free online debt advice and will help you to take charge of your debt.
It’s important to remember that your credit rating may be affected by the debt management route you take, so consider your options carefully. We go through different debt solutions below.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How should you use online reviews?
Review scores change and do not establish whether your debt or the firm’s conduct is correct.
Reviews may concern different services, including recovery for creditors and collection from debtors.
Read the context of an individual account rather than treating a rating as proof of wrongdoing or fair treatment.
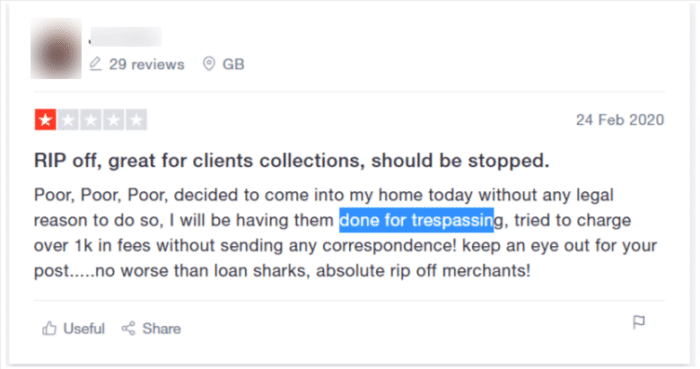
If something went wrong in your case, use evidence and the published complaints procedure.
Our advice would be to keep your wits about you when dealing with this company. Check your bank account and any fees that they may be adding.
Direct Collection Bailiffs Ltd (DCBL) Contact Details
If you have any questions, or you’re looking for the DCBL email address or phone number, we’ve put their contact details in the table below.
| Website: | https://dcbltd.com/ |
| Phone number for complaints | 0203 434 0432 |
| Email address for complaints: | [email protected] |
| Postal complaints address | Complaints Officer, Direct House, Greenwood Drive, Manor Park, Runcorn, WA7 1UG |
References
Schedule 12, Tribunals, Courts and Enforcements Act, 2007
Part 1, Regulation 10, Certification of enforcement agents, 2014.





