


High Court Enforcement Officer Powers: Your Rights


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Do you feel worried about a bailiff coming to your home? Are you scared about your things being taken away? It can be quite a tough spot to be in, but remember, you have choices. This article is here to help you understand those choices.
This guide explains the taking-control-of-goods rules in England and Wales. Scotland and Northern Ireland have different enforcement procedures. Seek free independent debt advice if a visit, removal or sale is imminent.
In this simple guide, we will help you understand:
- The powers of a High Court Enforcement Officer.
- The steps you can take if a bailiff is expected at your home.
- What a High Court Writ means.
- Which items a High Court bailiff can or can’t take.
- How to deal with bailiff fees.
Below, you can learn more about your rights and how to feel more calm about dealing with bailiffs. Remember, we can’t stop the bailiffs from doing their job, but we can help you understand your rights and make the best choices for you.
Let’s get started.
What is an HCEO?
A High Court Enforcement Officer (HCEO) is a type of enforcement officer – commonly known as a bailiff – who works to enforce orders from the High Court.
High Court Enforcement Officers can enforce High Court judgments and eligible County Court judgments transferred for enforcement. County Court debts of £600 or more may qualify, subject to exclusions; judgments based on agreements regulated by the Consumer Credit Act cannot be transferred for this purpose. Transfer does not guarantee faster recovery.
What is their power?
For debt recovery using a writ of control, agents can seek payment and take lawful control of eligible goods. Residential entry and business-premises powers differ; a writ is not an unrestricted permission to break into any property.
» TAKE ACTION NOW: Fill out the short debt form
Agents may request payment, agree affordable arrangements or control eligible goods. Goods may remain with the debtor under a controlled goods agreement, or be removed and later sold if the statutory conditions are met. Not every visit results in removal or sale.
This article concerns enforcement against goods under a writ of control. High Court officers also carry out other work, such as possession and delivery orders, under different powers. Always check the particular document and authority.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What is a Writ?
A writ of control is a High Court enforcement document authorising recovery through the taking-control-of-goods process. Other High Court writs have different purposes and should not be treated as interchangeable.
An agent needs the appropriate writ and authority to use High Court enforcement powers against goods. This is different from an ordinary request for payment, which does not itself authorise seizure.
The underlying debt may come from a High Court judgment or a County Court judgment transferred to the High Court for enforcement. A creditor does not issue a CCJ itself; a court makes the judgment.
A County Court judgment orders payment. It may follow a hearing, an admission or default if the claim was not answered. If it was wrongly entered, seek prompt advice about challenging it rather than assuming both sides were heard.
Your judgement will include the following:
- How much you owe
- How you should pay
- Who you should pay
- Your deadline to pay.
A CCJ is normally registered and remains on the register and credit file for six years. Paying it in full within one calendar month of judgment allows the entry to be removed. Paying later normally results in a “satisfied” entry for the remainder of the six years.
Give the court evidence of payment if you need the register updated or a certificate of cancellation or satisfaction. Payment within one calendar month is a basis for removal, not a guarantee the judgment was never initially registered.
Enforcement must be permitted by the judgment and applicable rules. Check whether payment is overdue, whether instalment terms apply and whether any stay or other restriction is in force.
What goods can they take?
A High Court bailiff can take any goods that the debtor owns to clear the debt – with some exceptions.
There are strict rules on what can’t be removed from your property. These items include:
- Goods owned solely by someone else, and items belonging to or exclusively used by a child. Joint ownership needs separate consideration.
- Pets or service animals
- Qualifying equipment needed personally for work, business, study or education, normally up to £1,350 in total and subject to statutory exceptions.
- A vehicle displaying a valid Blue Badge because it is used to transport a disabled person, and qualifying goods needed for care. A leased Motability vehicle is also third-party property.
- Anything permanently fitted to your home – kitchen units, etc.
Bailiffs also can’t take things that you need to live. These items can be anything that you use for your ‘basic domestic needs.’ They can take some of these things, but must leave you with:
- A table with enough chairs for everyone in your home
- Beds and bedding for everyone in your home
- A phone or mobile phone
- Any medicine or medical equipment that you need to care for someone
- A washing machine
- A cooker or microwave, and a fridge.
If exempt goods or someone else’s property have been taken, contact the agent immediately with evidence and seek advice on the appropriate court procedure and deadline. An error does not automatically cancel the debt or guarantee that goods will be returned without costs. A formal third-party or exempt-goods claim may be needed under the Civil Procedure Rules; a complaint does not automatically stop sale.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Do they have to give notice?
For enforcement action under the rules in force from 1 May 2026, the usual minimum notice before taking control of goods is 14 clear days. A qualifying debt advice provider can request an extension to at least 28 clear days before the original deadline, except for excluded business debt. A court can shorten notice in specified circumstances; earlier enforcement action is protected by transitional rules.
High Court writs of control are subject to these taking-control-of-goods notice rules. Other High Court work, such as possession enforcement, has different procedures. An old forum post should not be used as a statement of current law:
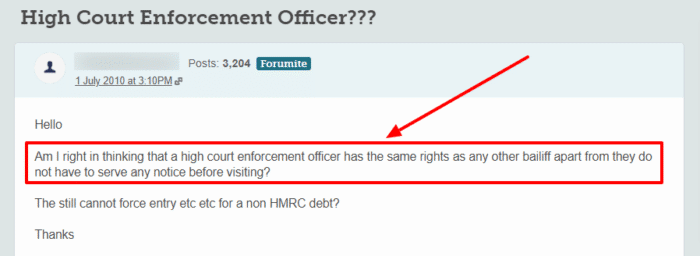
Source: https://forums.moneysavingexpert.com/discussion/2567253/high-court-enforcement-officer
Check the current legislation and court guidance, and ask a free debt adviser to apply it to your circumstances. The example above is historical and should not be relied on for a current deadline.
What times can they visit?
A High Court Enforcement Officer can come to your home between the regulated hours of 6 am and 9 pm.
There are statutory exceptions: court authorisation, business premises while open, and a reasonable period to finish action lawfully begun. The 6am to 9pm rule is therefore not absolute.
Can they enter my home?
For ordinary civil debts, including council tax, an enforcement agent cannot force initial entry into a home. They may enter through a normal unlocked door where they have lawful authority, but cannot climb through a window or push past you. You can communicate through a closed door. High Court business-premises enforcement and re-entry to recover controlled goods have separate rules.
If you don’t want them to come inside, you should keep your doors locked and communicate with them through the letterbox or through an upstairs window.
A debtor-owned vehicle outside the home may be controlled without entry to the house, but ownership and exemptions matter. Goods necessary personally for work, study or education are protected up to £1,350 in aggregate. A vehicle displaying a valid Blue Badge because it is used to transport a disabled person is exempt. A work commute alone does not automatically protect a car, and financed or third-party vehicles require careful ownership checks. See related guidance.
Can an officer force entry?
For a High Court civil-debt writ, limited force powers may apply at qualifying business premises or when recovering goods already controlled after breach of an agreement and the required notice. A writ alone does not authorise forced initial entry to a home.
What does it really mean?
Where a specific legal power permits reasonable force, an agent may use a locksmith. The method and degree of force must be lawful and reasonable in the circumstances; using a locksmith does not itself create authority to enter.
Agents cannot use force against a person to gain entry. Entry must use a door or other legally permitted usual means; they cannot treat an open window as permission to climb in. Seek urgent advice if the claimed entry power is disputed.
What can an officer not do?
A High Court bailiff cannot enter your home in some situations.
They cannot:
- Use force against a person, including pushing past them, to gain entry.
- Entering, re-entering, remaining or taking control of goods where the only people present are children under 16, vulnerable people, or a combination of those groups.
- Gain entry through any other means that a door, i.e. they cannot climb through open or unlocked windows
Ownership of goods – who has the burden of proof?
Agents must not take property owned solely by someone else for your debt. Provide purchase or ownership evidence promptly if there is a dispute. The owner may need to make a formal claim under the Civil Procedure Rules, so do not rely only on an informal complaint.
For example, a partner may have bought a new computer. You could prove this by showing evidence that your partner bought the computer. It’s not always easy to prove an asset isn’t yours, especially if you claim it’s owned by someone else you live with.
Can you stop bailiffs?
A stay of execution can temporarily stop enforcement of a writ. Setting aside a judgment is a separate remedy and requires proper grounds; a stay does not automatically cancel the judgment. The application and evidence depend on the order and court, so obtain advice before applying.
For a default judgment, the court must set it aside in specified cases where it was wrongly entered. It may also set it aside or vary it where there is a real prospect of defending the claim or another good reason, considering promptness. Non-receipt of documents is not the only ground, and filing an application does not itself guarantee a stay.
If you want to explore this option further, it’s best to speak with a UK debt charity.
How much are their fees?
Fees can substantially increase the balance, so check the stage and itemised calculation.
High Court fees attach to defined enforcement stages, not automatically to every visit. The figures below apply under the rules effective from 1 May 2026; earlier enforcement action has transitional protection.
Compliance stage: £79. This covers the initial compliance work, including preparing and issuing the notice of enforcement.
First enforcement stage: £200 plus 7.5% of the portion of the debt above £1,200. Second enforcement stage: £520 when the statutory conditions for that stage are met. The second enforcement stage is not an automatic second-visit charge. If no contact is made at the first attendance, the debtor must have another opportunity to pay or enter a repayment arrangement or controlled goods agreement. Full payment or an arrangement kept to can prevent escalation; failure to engage, agree or maintain payments can allow the next stage under the regulations.
Sale or disposal stage: £550 plus 7.5% of the portion of the debt above £1,200. The percentage is not charged on the whole debt merely because it exceeds the threshold.
Only additional expenses permitted by the fee regulations can be recovered, subject to their conditions and reasonableness requirements. Some expenses are specified in the rules and others require court approval. Request an itemised breakdown and the basis for each charge.
Are HCEOs regulated?
The High Court Enforcement Officers Association has a Code of Best Practice that is based on the National Standards issued by the Ministry of Justice.
Statutory duties apply regardless of association membership. The National Standards are guidance, and any association code or independent accreditation requirements are additional to the law.
The law and relevant professional standards address matters such as:
- Provide relevant ID on request
- Act within the law at all times
- Respect confidentiality
- Do not exaggerate the powers that they hold
- Act in a professional, calm, and dignified manner
- Do not discriminate.
If you think that a HCEO has broken any of these rules, or any other rule in the Best Code of Practice, you can make a complaint. I go through this process below.
How to complain
If you think that your HCEO has been unreasonable or behaved inappropriately, you can make a complaint. You can also make a complaint if you feel that they have broken any of the High Court Enforcement Officer Association’s (HCEOA) Code of Best Practice.
Make your first complaint to the HCEO’s company or agency so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
After the firm has considered your complaint, check whether the Enforcement Conduct Board can investigate: the firm, activity date and complaint must fall within its scheme. Council complaints may instead fall within the relevant local-government ombudsman process after you complain to the council. Court challenges and urgent requests to stop enforcement are separate. HCEOA is a trade association, not a body that automatically fines officers when a complaint succeeds. Serious fitness-to-operate complaints and court challenges have separate routes; compensation is not guaranteed. See related guidance.





