Trust Deed

How to Get Out of a Trust Deed? Cancel Guide

Scott Nelson MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Debt Expert

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
· Aug 13th, 2025
Get debt advice from The Debt Advice Service

Total amount of debt?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.

Are you searching for ways to cancel a trust deed? Or, perhaps you’re interested in knowing more about trust deeds.

Either way, you’ve made the right choice by being here. Each month, over 170,000 people like you visit our website seeking advice on debt solutions.

In this easy guide, you’ll learn:

  •  What a trust deed is and how it works
  •  How to cancel a trust deed
  •  What happens after your trust deed ends
  •  If you can write off some debt
  •  Who to contact for help

According to the Money & Pensions Service, 700,000 people are either in problem debt already, or are at risk of experiencing problem debt.1 So we know how hard this can be.

But don’t worry. We’re experts on money matters, and we’re here to help you understand and deal with them.

Could you legally write off some debt?

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

Answer a few questions to start your enquiry. Options available depend on your circumstances.

How much debt do you have?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

Cancelling a Trust Deed

  • A Trust Deed is a legally binding agreement that cannot be revoked at will.
  • If you cannot pay the installments your creditors find acceptable, your Trust Deed may fail.
  • The failure of a Trust Deed will most likely lead to your sequestration – so you could lose your belongings.

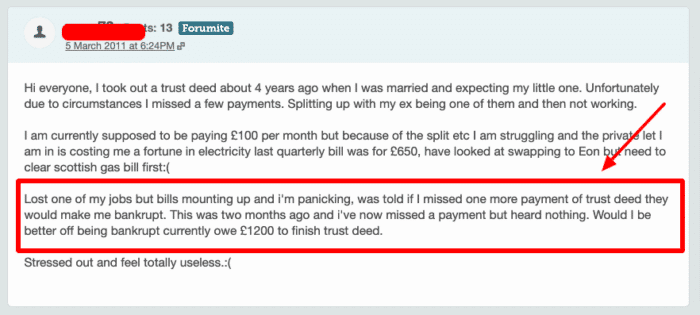
People often contemplate cancelling their Trust Deed due to unexpected life changes such as employment shifts, unexpected expenses, or financial circumstances.

Understanding these reasons can add clarity to the process.
source

Apart from sequestration, cancelling a Trust Deed can also impact your credit rating for several years, making it challenging to obtain future credit or loans.

It’s also worth noting that your financial stability could be at risk if you face aggressive actions from creditors.

Its terms bind you once you’ve entered into a Trust Deed.

However, like any contractual agreement, there are stipulations and nuances. It’s always recommended to consult with a legal professional if considering cancellation to minimise the financial implications of cancelling a Trust Deed.

How will you cancel a Trust Deed?

There is a straightforward method to come out of a Scottish Trust Deed, yet it needs your trustees to consent. 

They could contact your creditors as part of the Trust Deed termination process, prompting them to say they mean to end the Trust Deed and are looking for their discharge.

This would impact returning you to the starting point, and then you could set up an installment plan/Debt Arrangement Scheme (DAS) if you wish, all things considered.

Remember, if you cancel a trust deed, you are no longer covered by protection from creditors.

» TAKE ACTION NOW: Fill out the short debt form

Get debt advice from The Debt Advice Service

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.

Get started

MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit [MoneyHelper](https://www.moneyhelper.org.uk/en/money-troubles/dealing-with-debt).

How soon will you be discharged from your debts?

It will be written in your agreement that it is so long to run for and when you will be discharged.

Typically it is forty-eight months, i.e. four years from the date you sign it (however, it tends to be longer). Be that as it may, this release isn’t automatic, unlike what happens in sequestration.

Your creditors must release your trustees before you can be discharged. This implies that a Protected Trust Deed may stay open in the Register of Insolvencies for quite a while after four years.

Your discharge is generally binding on the entirety of your creditors.

This implies they can’t pursue you for the money you owed them before you consented to the arrangement.

Yet, there are two exceptions. These are; 

  1. Debts not covered by the arrangement (like overpayment of social security), or if a creditor who protested the agreement can demonstrate in court that he would have more cash back if he had been bankrupt. This is an exceptionally uncommon function in reality.
  1. In the event that the Trust Deed fails to get protected, your discharge doesn’t stop creditors who protested in any case still pursuing you for the money you owe them.

Consistent communication with your trustee is crucial.

Whether facing difficulties with payments or simply needing clarity on your agreement’s details, your trustee is there to guide and support you throughout the tenure of your Trust Deed.

Other ways available

There are a few different ways to manage personal debts in Scotland. Scottish Trust Deeds aren’t accessible to everybody (and aren’t the ideal alternative for everybody either).

  • A Debt Payment Programme under the Debt Arrangement Scheme is one alternative. It could allow you to completely reimburse your debts while your regularly scheduled instalment is diminished to a reasonable sum. Interest stops, and you have lawful security from your creditors.

    This alternative likewise offers some adaptability, similar to emergency payment breaks.
  • A Debt Management Plan could push you to reimburse your debts completely. It’s not ensured that interest will stop, and no formal lawful protection is granted.

    Your regularly scheduled instalment is diminished to a moderate sum. This is an especially adaptable alternative.
  • Bankruptcy is utilized to manage more critical debt issues. It works likewise to a secured Trust Deed; however, it probably won’t be appropriate for some mortgage holders.

    You can go bankrupt regardless of whether you can’t manage the cost of a regularly scheduled instalment (in contrast to the other debt arrangements).

Who do you contact for help?

If you are struggling with debt, you should look for counsel at the earliest opportunity.

Seeking advice and managing your debt at the beginning phase may assist you in avoiding the more severe outcomes of being in debt, for example, legal activity by your creditors or sequestration.

Various people can give free, classified, and unprejudiced money guidance vis-à-vis in your neighbourhood.

A few associations may likewise offer information and guidance via phone. If you request guidance, ensure the individual managing you knows you live in Scotland. Debt regulations and solutions can differ significantly across regions.

Therefore, for those residing in Scotland, it’s crucial to seek advice tailored to Scottish laws and financial practices

Some helpful contacts who will offer free advice on debt

Could you legally write off some debt?

MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.

Answer a few questions to start your enquiry. Options available depend on your circumstances.

How much debt do you have?

MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.

If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.

For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.

References

  1. Money & Pensions Service – Financial wellbeing in Scotland
Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
