Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters.
Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations.
MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.
If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you wondering how long a debt can be chased? You’ve come to the right place. Every month, over 170,000 people visit this site for advice on debt matters.
This article will answer your queries and guide you on:
Understanding the time limit for chasing a debt in the UK.
Whether you need to pay a debt older than six years.
How the statute-barred limitation period works.
Checking if your debt needs to be paid.
How to deal with debts you’re not required to pay after six years.
It’s quite common to feel concerned about debt. After all, a study by Citizens Advice found evidence of poor practices by debt collectors in the UK, including the collection of very old debt.1
Don’t worry! Our aim is to provide you with clear, simple information to help you make the best decisions.
Let’s get started.
Could you legally write off some debt?
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
Answer a few questions to start your enquiry. Options available depend on your circumstances.
MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.
If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Do I Have to Pay a Debt Older than 6 Years?
There’s a chance you won’t have to pay a debt if it is older than six years old. This does depend on a few factors.
Debts older than six years can become statute-barred.
The Limitation Act 1980, or the Statute of Limitations, decided on the length of time that creditors can chase a debt.
Not all debts will fall under statute-barred territory.
The Limitation Act 1980 only applies when there has been no acknowledgement of the debt or payment towards the debt in the limitation period and only applies to residents of England and Wales.
Paying off debts in the UK older than six years is necessary if you’ve had a CCJ issued against you during the limitations period. The limitation period is how long the creditors and debt collection in the UK must take court action against you.
This will depend on the type of debt it is (unsecured/secured) and to who you owe the money.
A CCJ can have some pretty severe effects on your credit record, so take advice from debt charities such as Stepchange before it gets to that point.
Plenty of options are available to help you manage your debts and avoid the CCJ (County Court Judgement) implications.
When Does the Statute-Barred Limitation Period Start From?
The date the limitation period begins can be the most recent from any of the following.
When you or a third party acknowledges that you owe the debt, make sure you state that you don’t owe it during all communication, be it a letter, email, or phone. Keep a copy or record of all communication you make, as you might need it to use as evidence to support your claim.
From the date of your last payment made towards the debt. The payment counts if it was made on your behalf by a third party, such as a debt management service.
A defaulting term date or time when the creditor could have started legal action against you but failed to do so. This information is found in the terms and conditions of the loan but not always. If the creditor began court action at the time, the debt cannot become statute-barred.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Check if You Have to Pay a Debt
Before dealing with debt collectors, the first step is deciphering if you must pay the debt and if it’s now statute-barred.
Begin by looking at the debt and calculating how long has passed since you last paid on it. You must also check to see if it has been six years since you last contacted the creditor.
You may not have to pay the debt you owe in other circumstances, too, including:
If you felt pressured into signing the agreement by the creditor
If the creditor didn’t make the terms of the agreement clear at the time of signing
The creditor failed to check that you could afford the repayments at the time of signing
The debt isn’t yours
Speak to UK Debt Management Services for free and impartial advice if you are not sure.
Understanding secured and unsecured debts is important, so check out this guide.
Remember, you must not have paid or acknowledged the debt for six years for it to meet Statute-barred debts criteria. These debts must also be paid if they have a CCJ issued against you within the limitations period.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.
If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Can A Debt Be Enforced after 6 Years Have Passed?
Secured loans such as mortgages have an extended time limit.
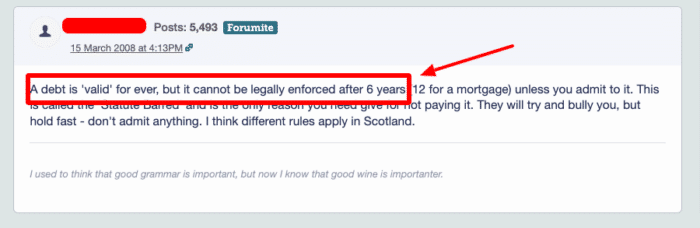
These secured debts can be chased for up to 12 years. Additionally, different debts can be chased indefinitely.
These debts include money owed to HM Revenue and Customs, such as income tax, VAT, and capital gains tax. You also must pay money owed to the Department of Work and Pensions for benefit overpayments.
Will My Old Debt Be Written Off?
Having a statute-barred debt older than six years doesn’t mean the debt is written off.
The debt won’t simply disappear. It will still appear on your credit file, which can have serious implications when seeking credit.
Furthermore, the creditors can continue to ask you to repay the debt. They can’t legally enforce debt repayment under debt enforcement in the UK.
Many creditors will continue to chase a debt that is statute-barred. If you want to check debt to see if it is no longer enforceable, there are steps you can take.
Check your credit file.
Inform your creditor that the debt is statute-barred and enforcement is no longer an option.
You can avoid getting a CCJ if your creditors take you to court and can prove the debt is statute-barred.
It’s also possible to stop debt collectors from harassing you and removes the need for dealing with debt collectors. You can achieve this by reporting them to the Financial Conduct Authority or taking them to court.
Remember to keep proof of postage and a copy of any communication you make with the creditor and only write to them if you’re certain the debt is statute-barred.
Get Help with Your Debt
You don’t have to panic or deal with debts alone. There are debt advisors that will help you.
If you’re dealing with debt collectors, want to establish if a debt is statute-barred, or simply wish to avoid debt building up, contact one of the debt advising services in the UK:
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
Answer a few questions to start your enquiry. Options available depend on your circumstances.
MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.
If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters.
Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations.
MoneyNerd does not provide debt advice or recommend debt solutions. We can introduce you to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. Their debt advice is free, and there is no obligation to proceed.
If you request an introduction, we’ll share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.