


How Much Should You Offer to Settle a Debt? UK Settlement Guide


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you having trouble paying your debts and thinking of making a settlement? You are in the right place to find out how much you should offer to settle a debt.
We understand that the idea of making a settlement offer can be daunting; you’re not alone. In fact, over 170,000 people visit our website each month for guidance on debt solutions.
In this article, we’ll cover:
- Understanding what a debt settlement is in the UK.
- Reasons why creditors might accept less than you owe.
- Who usually tries to settle a debt.
- How to offer a settlement.
- The impact of a settlement offer on your credit file.
Our team has handled many debt situations, so we know how tricky it can be. We will help you navigate the process with clear, easy-to-understand advice.
Read on to find out more about settling your debt.
How Much Should You Offer to Settle a Debt?
To get a debt settlement, you need to make a reasonable offer. The size of your settlement offer on your debt will depend on your circumstances and what you can afford to repay.
There is no standard percentage that a creditor must accept. Base an offer on what is available after essential living costs and priority debts, and explain your circumstances honestly.
However, the exact amount your creditor will accept could vary greatly depending on the following:
- Your financial situation
- The nature of the debt
- The creditor’s policies
- Your negotiation skills
A larger offer may be more attractive, but do not offer money you need for essentials or promise payments you cannot make.
How to Make an Offer?
You can make a settlement offer on your debt yourself by negotiating with creditors. Call the creditor or collection agency and ask to discuss a settlement.
You can then provide them with a figure you want to pay in writing to get the debt cleared through ‘partial settlement’.
It is wise to provide information about why you are offering this and maybe state that this is the maximum you can offer.
Some people get anxious when speaking with creditors or don’t trust their negotiating skills. In these cases, you may get someone else to make a debt settlement offer on your behalf.
It may be a friend, relative, or even a reputable UK debt charity. There are even companies that will provide this service for a fee.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
When Should You Pay the Amount?
It is essential that you do not make the payment before getting it in writing that you have a settlement offer accepted.
For example, if you are told over the phone that they will accept your settlement and then pay without written confirmation, the creditor could claim later they never formally accepted. The amount you just paid will go towards paying off the debt, but it will not wipe the debt.
Similarly, if you get a debt settlement offer acceptance letter, make sure you make the payment before any end date that the creditor gives. If you make it after this date, it may no longer count as a settlement payment.
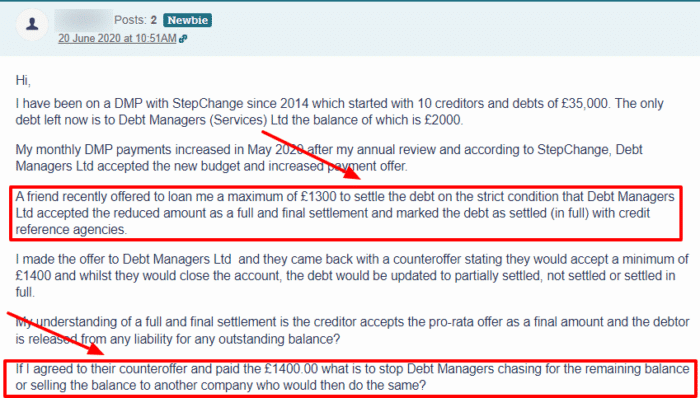
Before paying, obtain clear written confirmation that the agreed sum will settle the whole liability and that the remaining balance will not be pursued or sold on. Ask how the account will be reported to credit reference agencies, and keep the agreement and payment evidence.
Should You Keep Evidence of Payment?
Absolutely. If you have received a settlement confirmation letter, you should keep this as proof of your payment. This is in case the creditor claims later they never agreed to the settlement or that they claim they didn’t receive the payment on time.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
How Long Does Settled Debt Stay on Your Credit File?
A defaulted account normally stays on your credit file for six years from the original default date, even if you settle it later. If the account never defaulted, the retention period generally runs from settlement or closure. Paying less than the full balance may be recorded as a partial settlement.
Why Would Creditors Accept Less?
A creditor might accept a lump sum because it offers a realistic return sooner than affordable instalments would. It can still reject the offer.
A time-limited contribution from a relative or friend may help explain an offer, but it does not force the creditor to accept. Get agreement before paying, and seek advice if you have several creditors so the offers are fair and affordable.
Another reason relates to who owns the debt. Some debt collection agencies buy debt for well below its value, meaning they still make a big profit if you offer less than the money owed.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
What If They Don’t Accept the Offer?
If they don’t accept your full and final settlement offer, you might want to make another offer. However, if your previous offer was said to be all you can afford and you now offer more, there is a good chance that the creditor will not believe you.
Explain any changed circumstances honestly. Consider the available alternatives with a free debt adviser before increasing your offer.
If your maximum settlement offer is rejected, I suggest you search for other debt solutions to pay off some of the debt gradually. This should be a crucial part of your debt management plan.
After so many months of paying part of the debt off, you might want to offer a new settlement figure. Because you’ve already paid off some of the debt or maybe saved more, you now might have your debt settlement offer accepted.
If you need debt advice on how to make a full and final settlement offer, you may want to consider talking with a debt charity or personal insolvency practitioner. Get in touch with:





