Debt Info
Council Tax Debt

Council tax bailiffs: payment plans, rights and help

Scott Nelson MoneyNerd Janine Marsh MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Founder of MoneyNerd

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
&
Janine
Janine Marsh MoneyNerd

Janine Marsh

Former MoneyNerd Contributor

Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.

Learn more about Janine
· Oct 4th, 2026

Advertisement

Request a call from The Debt Advice Service

Total amount of debt?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Stop council tax bailiffs

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.

Council tax arrears are a priority debt. This guide explains council tax enforcement agents in England and Wales and steps to take if you cannot pay.

In this guide, we will explain all you need to know about council tax bailiffs. We will cover:

  • The simple process of collecting council tax arrears.
  • What you can do to stop council tax bailiffs.
  • If bailiffs can enter your home for council tax.
  • If the council can enter your home without a warning.
  • How long you can be chased for council tax debt.

We understand your worry. We know it’s hard to think about these things, but we’re here to help you – together, we can find a way through this.

Let’s get started.

Advertisement

Request a call from The Debt Advice Service

Tell us how much debt you have to continue to the enquiry form. Options depend on your circumstances.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

How Can I Stop Them?

You should aim to clear your debt or come to an agreement before an enforcement agent gets involved. 

Lawful enforcement fees can be added once the relevant stage begins. Ask for an itemised balance and contact a free debt adviser promptly.

If you do pay anything to a bailiff, make sure you get a receipt.

Prevention is better than cure when it comes to bailiff action! Dealing with bailiffs can take a toll on your mental health. 

For enforcement action under the rules in force from 1 May 2026, the usual minimum notice before taking control of goods is 14 clear days. A qualifying debt advice provider can request an extension to at least 28 clear days before the original deadline, except for excluded business debt. A court can shorten notice in specified circumstances; earlier enforcement action is protected by transitional rules.

Full payment of the debt and lawful fees can end enforcement. If you need instalments, ask the council or enforcement company to accept an affordable arrangement and confirm in writing whether visits are on hold; an offer alone does not stop a visit.

Again, get a receipt if you have paid.

If illness, disability or other circumstances make you vulnerable, tell the council and enforcement company immediately and ask them to review how the case is handled.

Vulnerability can affect the appropriate approach and the recovery of some fees, but it does not create an automatic exemption from enforcement.

Agents must not enter, re-enter, remain in premises or take control of goods where the only people present are children under 16 or vulnerable people, including a combination of them. This is different from a blanket ban on visiting anyone who lives alone.

Vulnerability depends on the person’s circumstances and how enforcement affects them. Tell the enforcement company and creditor about your needs, provide relevant evidence if available, and ask for suitable adjustments. A diagnosis or membership of a particular group does not automatically cancel the debt, stop all visits or remove all fees.

Explain your circumstances before a visit if possible and request appropriate adjustments, a hold for advice or return of the case to the council where necessary.

Under regulation 12 of the Taking Control of Goods (Fees) Regulations 2014, enforcement-stage fees and related disbursements are not recoverable from a vulnerable debtor unless they have been given an adequate opportunity to obtain assistance and advice before controlled goods are removed. This is a conditional protection, not a blanket fee exemption.

Remember, it’s best to call them before they call on you!

The council can still seek payment of a valid debt. Ask for confirmation of any agreed hold or arrangement and continue paying ongoing council tax where possible.

Advertisement

Debt advice: Continue to the debt enquiry form

Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.

Can they force entry?

For ordinary civil debts, including council tax, an enforcement agent cannot force initial entry into a home. They may enter through a normal unlocked door where they have lawful authority, but cannot climb through a window or push past you. You can communicate through a closed door.

An earlier visit alone does not authorise forced re-entry. Reasonable force may be available to recover goods already controlled after a repayment agreement is breached, but only if the statutory conditions and required notice are satisfied. Get urgent advice if forced re-entry is threatened.

Force against a person is not permitted under these taking-control-of-goods powers. Any re-entry must remain within the lawful enforcement authority.

This is why it is important to keep paying your CGA or communicate with the company if you need to miss a payment or change the schedule. The bailiff may be able to help if you speak with them first. 

Agents may take control of a debtor’s non-exempt vehicle on premises they have power to enter or on a public highway. Ownership, finance and disability or work exemptions need to be checked.

Advertisement

How the introduction works

The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.

Options depend on your circumstances. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Can they enter my property without notice?

You might also be wondering if the local council can come into your property. 

Council housing visits for repairs or inspections are separate from council tax enforcement. Access requirements depend on the tenancy and purpose of the visit.

Ordinary inspection rights do not give a housing officer a general right to force entry. Emergencies or a specific legal order can create different powers.

A housing officer does not gain bailiff powers merely because council tax is unpaid. Ask which legal authority is relied on for any demand to enter or remove goods.

If they do this, seek advice and consider lodging a complaint. 

Council officers can have specific statutory access powers for particular purposes, but there is no general power to enter a private home simply to collect council tax.

How long can you be chased for debt?

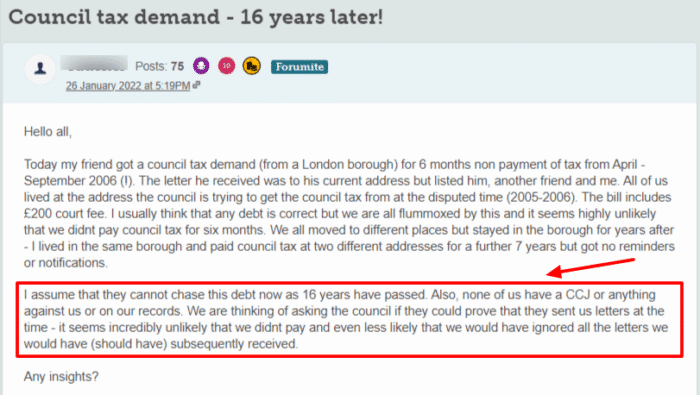
In England and Wales, an application for a council tax liability order is generally subject to a six-year limit from when the sum became due under the relevant billing rules. The date and any order already made must be checked.

Do not assume an old bill is unenforceable. Ask the council for the bill, due dates and details of any liability order, and have a debt adviser check them.

Council tax has its own statutory recovery rules; the limitation rules for ordinary credit debts cannot simply be applied to it.

If the council obtained a liability order in time, the position is different from a debt for which no order was obtained. See related guidance.

Once a valid liability order has been made, the six-year limit for applying for that order does not automatically cancel the debt or prevent later enforcement.

A liability order is not overridden simply because six years have passed. Seek advice on the particular order and proposed enforcement method.

Scotland has separate council tax recovery and prescription rules. Get Scottish debt advice rather than applying the England and Wales six-year application limit.

If you think your arrears are no longer enforceable, it’s best to seek advice first to make sure. 

Advertisement

About The Debt Advice Service

Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Can I write off my debts?

You might be able to write off some of your council tax debts with a debt solution. Even if these debts can’t be covered, getting a debt solution might help you get back in control of your finances enough to pay back the council.

There are several different debt solutions available in the UK, so I recommend speaking to a debt charity as soon as possible. Their advisors will be able to look at your finances in detail and help you work out which debt solution will work best for you.

I have linked a few charities that offer these advisory services for free below.

Individual Voluntary Arrangement (IVA)

An IVA is a formal insolvency arrangement with creditors. It can include agreed payments or other contributions and binds creditors covered by the arrangement once approved. Fees, effects on assets and credit, and the risk of failure need to be considered with an authorised insolvency practitioner.

An IVA can write off the unpaid balance of included debts on successful completion, subject to its terms. Excluded debts remain payable, and failure can leave you liable for remaining debt and further action.

There is no universal statutory requirement to owe several thousand pounds or have more than one creditor. Suitability depends on the debts, available income or assets, alternatives and the provider’s criteria.

Trust Deed

Scotland has different debt remedies, including protected trust deeds, the Debt Arrangement Scheme and bankruptcy. A trust deed is one option, not a compulsory replacement for an IVA; ask a Scottish debt adviser which options fit your situation. See related guidance.

A protected trust deed is a formal Scottish insolvency arrangement with conditions, costs and risks to assets and credit. Protection and discharge depend on its status and successful completion; it does not automatically cover every debt or prevent every type of contact.

Debt Relief Order (DRO)

In England and Wales, a Debt Relief Order may be available if qualifying debts are no more than £50,000, spare monthly income is no more than £75, assets are no more than £2,000 and any qualifying vehicle is worth no more than £4,000. Other conditions apply, including not owning your home. An approved adviser must assess eligibility. See related guidance.

A DRO normally gives 12 months of protection for the debts included in it. Ongoing bills and excluded debts still need to be paid. Follow your adviser’s guidance, especially where rent arrears or eviction are involved.

Included debts are normally discharged at the end of the DRO period if the order remains in force. Changes in circumstances must be reported and can affect the order; excluded debts are not written off.

Bankruptcy

If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.

Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.

Sequestration

Sequestration is the Scottish version of bankruptcy.

If you have little income and no valuable assets, you may be able to apply for a minimal asset process bankruptcy (MAP). A MAP is a quicker, cheaper, and more straightforward version of sequestration, so worth considering.

How do I complain? 

You can complain about unlawful charges, threats, inappropriate conduct or failure to consider vulnerability. Bailiff enforcement is not generally governed by FCA debt collection rules. See related guidance.

Complain to the enforcement company and the creditor, identifying the conduct or charge you dispute. For a County Court bailiff employed by HMCTS, complain to the court. A complaint does not itself suspend enforcement or extend a court deadline. For council tax, use the council’s complaints procedure as well.

The Financial Ombudsman Service is not a general appeal body for bailiff enforcement and does not fine bailiffs. The correct escalation route depends on the agent and creditor: it may involve an eligible enforcement complaints scheme, a council ombudsman complaint or an application to court. Obtain advice on the route and any deadline. See related guidance.

For a council complaint, the relevant local government ombudsman may be available after the council’s process: the Local Government and Social Care Ombudsman in England or the Public Services Ombudsman for Wales. Check the enforcement firm’s own applicable independent complaints scheme too. See related guidance, related guidance, related guidance.

Advertisement

Request a call from The Debt Advice Service

Tell us how much debt you have to continue to the enquiry form. Options depend on your circumstances.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine Marsh MoneyNerd
Debt Expert
Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.