


Link Financial Debt – Should You Pay?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you stressed about a letter from Link Financial Debt Collection? Are you puzzled about where the debt came from or if you should pay it at all?
This guide explains how to verify a Link Financial letter, check the balance and respond within any applicable deadline.
In this guide, we’ll help you understand:
- Who Link Financial Debt Collectors are.
- If you really owe the money they claim.
- The ways you can stop them from contacting you too much.
- How to protect your mental wellbeing during this process.
- Your options to set up a payment plan or even write off your debt.
Dealing with debt can be stressful. Free, independent advice can help you assess liability, affordability and the next steps.
We’re here to help you navigate this journey.
Do You Owe Money to Link Financial Debt Collection?
Link Financial will send a letter to your address telling you that you owe them or their client money – and they are the company employed to collect the debt.
An ordinary collection letter is not necessarily a formal Letter of Claim. A business seeking a debt from an individual may need to follow the Debt Claims Protocol, usually allowing at least 30 days to reply before court action. See related guidance.
They may follow this up with an email and frequent calls.
Check the evidence rather than assuming a legal warning is an empty threat. A disputed or unfamiliar debt still needs a timely response, particularly if court papers arrive.
Check if you really owe the money
Are you sure you really owe the money? The first thing to establish is where the debt started and how much you really owe.
Ask for an itemised balance showing the original amount, payments, interest and charges. An increase must have a lawful basis; do not assume every added sum is correct.
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
Follow our ‘prove it’ guide with letter templates and get them to prove that you owe the money.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Before requesting evidence
First identify the type of debt and the stage reached. Consider these points before sending a template:
- If evidence has already been supplied, identify what remains unclear rather than repeating an identical request.
- If the debt may be time-barred, obtain advice before making a payment or written admission.
A limitation or prescription defence depends on the applicable law and facts, not simply the date the account was opened. See related guidance.
For many simple-contract debts in England and Wales, the limitation period is six years from the relevant cause of action, subject to payment, written acknowledgement and court-proceeding rules. Many Scottish obligations prescribe after five years under different rules. Debt type and history matter; age alone does not establish that recovery is barred.
We recommend consulting a debt advice company or charity to assert whether your debt is statute-barred. And if it is, use our free statute-barred templates to send a professional and clear message to Link.
In England and Wales, limitation generally restricts a court remedy rather than automatically cancelling a simple-contract debt.
Scottish prescription can extinguish the obligation. If a claim arrives, respond and raise the relevant defence instead of assuming the court will identify it for you.
Tax and other public debts have different rules; there is no universal 20-year limitation period for everything owed to HMRC. Ask an adviser to identify the debt and jurisdiction.
A judgment debt is not governed by the ordinary six-year simple-contract rule. It does not automatically disappear after six years, although permission may be required for some later enforcement steps.
» TAKE ACTION NOW: Fill out the short debt form
How do you make a payment to Link Financial?
Not surprisingly, Link Financial has made it super easy for you to make a payment.
Use the payment methods shown on Link’s current official customer site or verified notice. Avoid using further unaffordable credit to repay a debt.
To pay online, go to https://www.linkfinancial.eu/.
Reach the customer portal through the official website and check the account reference before paying.
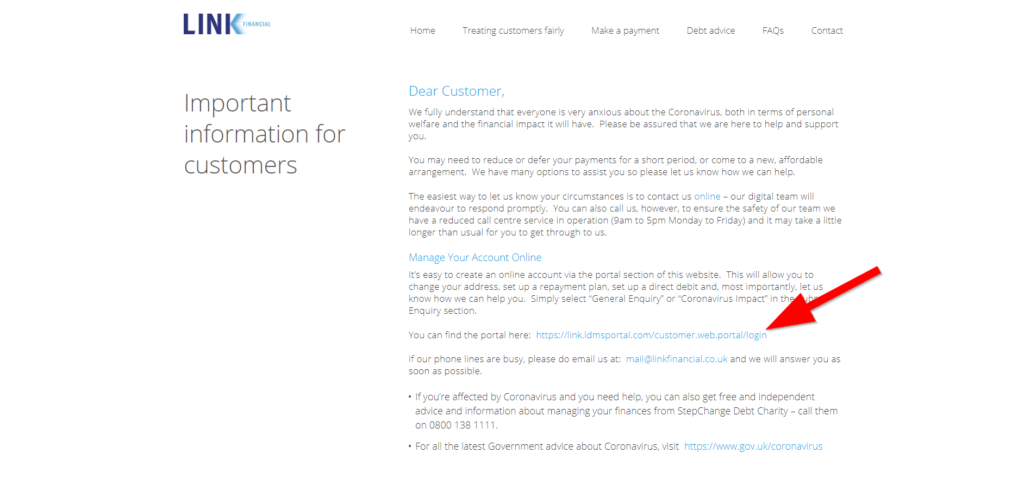
From there, you either need to register for an account or use existing details to log in. To register for a customer account, you will need your ‘link customer reference’, which you can get from an agent on the phone, or from an email or letter that they have sent you.
Before agreeing a payment amount, check essential spending, priority debts and any genuine dispute. Keep to existing legal deadlines while obtaining advice.
A free debt adviser can compare informal repayment, a DMP and any suitable formal debt solution. Eligibility, fees, credit effects and risks to assets vary. A DMP usually repays debts in full and does not guarantee frozen interest; an IVA has formal approval and completion requirements and is not suitable for everyone.
You can explore all these options and more on our debt options hub!
Repayment and debt-relief options
A creditor may consider an affordable arrangement, settlement or write-off in appropriate circumstances. None is guaranteed, and an agent may need the owner’s authority.
If limitation or prescription applies, obtain advice on explaining that position. It is a legal question, not a general method of making any debt disappear.
Your other options are debt solutions.
When to Complain About Link Financial Outsourcing Limited
If you have a complaint about Link Financial, you should first tell them about it.
Keep in mind that they are regulated by the FCA. This means that they have a code of conduct that they must stick to.
If you think that they have not acted properly or addressed your complaint sufficiently, you could make a complaint to the Financial Ombudsman Service (FOS).
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
When they become aggressive
If you experience threatening or abusive behaviour, record what was said, when it happened and who contacted you.
A demand for payment must not use misleading threats or unreasonable pressure.
Ask the firm to investigate specific conduct and explain the outcome you want.
Do not assume why an individual acted as they did; focus your complaint on the evidence.
If Link Financial Debt Collectors have been aggressive to you, start keeping records of events and consider making a complaint.
Ask for a reasonable contact method and explain any vulnerability. The firm should consider your circumstances, but a preference or debt solution does not automatically prevent every necessary legal notice or communication.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
When they contact you too much
Contact frequency and manner should be reasonable for your circumstances. Repeated oppressive contact can breach regulatory rules or amount to harassment, but no fixed number of calls automatically proves a criminal offence.
Keep a contact log, including unanswered or automated calls, and explain any unreasonable pattern in your complaint.
You can fight back against this by sending them your correspondence preferences in writing.
Keep a copy of this letter in case they ignore your preferences; it could be grounds to launch a complaint with the Financial Ombudsman.
When they don’t give you time
FCA consumer-credit rules require appropriate forbearance and consideration of reasonable time to seek advice. The pre-action and court timetables also matter.
If they try to take legal action against you straight after telling you that you have a debt to repay, this might be worth complaining about.
Not giving you time could be a way to pressure you into their own repayment proposal, which could not be the best option for your situation.
When they tell others about your debt
Collectors must handle information lawfully and avoid inappropriate disclosure to family, colleagues or neighbours. They may communicate with an authorised adviser or representative, and other lawful disclosures can be permitted.
A caller should take reasonable steps to verify identity before discussing account details.
If information was disclosed improperly, ask the firm to investigate and explain what happened. The legality depends on the circumstances and basis for disclosure.
Complain to Link first. For eligible financial-service complaints, follow the FOS process and deadlines. A data-protection complaint can also be raised with the ICO where appropriate.
Are Link Financial bailiffs?
An ordinary debt collector has no power to force entry or take goods. It may request a voluntary visit or payment, but you can refuse entry and ask it to leave. Bailiff enforcement requires separate lawful authority.
A debt collector must not pretend to have enforcement powers it does not possess.
At a doorstep visit, ask for identification and the reason for the visit. You can communicate without opening the door.
An ordinary collector can enter only with permission and cannot seize possessions. Separate rules apply to an authorised enforcement agent.
For an ordinary unsecured debt in England and Wales, enforcement normally requires a judgment and a further enforcement step. A CCJ alone is not a warrant to take goods, and a default judgment can arise without a hearing.
Please note, letting your debts escalate to this stage is not advised.
If you have allowed your debts to escalate you may require a debt solution to get them under control.
Main Differences Between Debt Collectors and Bailiffs
Understanding the main differences between debt collectors and bailiffs is essential to prevent unfair treatment.
Check out the table below for a quick and easy breakdown of the main distinctions between these two roles. If you’d like to learn more about your rights when dealing with debt collectors, please read our complete guide.
| Issue | Debt collector | Bailiff or enforcement agent |
|---|---|---|
| Role | Requests payment for a creditor or debt purchaser. | Acts under a legally valid enforcement power and must follow its limits. |
| Entry | No power to force entry; you can refuse entry and ask them to leave. | Usually cannot force first entry to a home for council tax or an ordinary civil debt. Limited exceptions and re-entry rules apply. |
| Goods | Cannot seize your goods. | May take non-exempt goods belonging to the debtor where the legal conditions are met; essential items and some work equipment are protected. |
| Bank accounts | A judgment alone gives no access. | Taking money from an account normally requires a separate third-party debt order obtained by the creditor, not a doorstep bailiff power. |
| Contact | Must avoid harassment; regulated firms must contact at reasonable times. | Visits are normally between 6 am and 9 pm, subject to legal exceptions. |
| Vulnerability | Tell the firm what support or communication adjustments you need. | Tell the agent and creditor about vulnerability and seek advice about additional safeguards. |
| Disputes | Ask for evidence of the debt and complain about improper conduct. | Check identification, the enforcement authority and fees; get urgent advice about an invalid notice or proposed entry. |
Link Financial Outsourcing Telephone Number
Use Link’s official customer contact page and the account reference on a verified letter. Different teams may have different contact details.
| Company Name: | Link Financial Outsourcing |
| Other Names: | Link Financial |
| Post: | Link Financial Outsourcing Limited, PO Box 107, Caerphilly CF83 3GG |
| Customer contact | Link’s current contact page lists 03330 145 145. Check its published hours and the details for your account. |
| Company website: | https://www.linkfinancial.eu/ |
| Customer email address | [email protected] |
| Incoming calls | A displayed number is not proof of the caller’s identity; verify through an independent official route. |
You can request written contact, but continue checking correspondence and legal deadlines. Blocking calls does not resolve or cancel the account.
References





