


NCO Europe Debt Collection: Check a Letter and Your Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
If you’ve received a letter from NCO Europe Debt Collection, you might be feeling worried and unsure.
Check who sent the letter and which account it concerns before sharing information or paying.
In this simple guide, we will show you:
- Who NCO Europe Debt Collection is.
- What they do and who they work for.
- If you really owe them money.
- What to do if you can’t afford to pay.
If collection contact is causing difficulty, you can ask for suitable arrangements and free debt advice.
With our experience, we’ll help you learn how to deal with NCO Europe Debt Collection.
Do You Owe Money to Them?
A real company’s name can appear in an impersonation attempt. Verify unexpected correspondence through NCO Europe’s official website or the original creditor.
NCO Europe describes debt collection and account-management services for clients.
Check the letter to identify the creditor and confirm NCO’s instruction. The company name alone does not prove that the debt is yours.
Acting for a client is different from buying a debt. Do not assume NCO owns the account or that a purchase price changes your liability.
Typical Process
A genuine letter or call may seek payment or information about an account. It could also involve an error that needs investigation.
We’ve put together this table that explains the key stages and actions involved in the debt collector timeline. If you’d like to learn more, please read our specialized guide.
| Possible stage | What can happen | What to do |
|---|---|---|
| Missed payments | The creditor or collector may contact you, apply contractual charges or issue required notices. There is no single timetable for every debt. | Check the debt and contact the creditor early. Prioritise essential bills and seek free debt advice. |
| Collection activity | Letters, calls or a proposed visit may follow. A collection agent has no power to seize your belongings. | Ask for identification and evidence of the debt. You do not have to let a debt collector into your home. |
| Letter of claim | A creditor may send a formal pre-action letter before making a claim. | Follow the response deadline and get advice; do not ignore it. |
| Court claim | In England and Wales, a creditor may apply for a county court judgment. A judgment and later enforcement are separate stages. | Respond to the claim by the court deadline, whether admitting it, disputing it or asking for time to pay. Attend if the court requires a hearing. |
| Enforcement after judgment | Where legally permitted, a creditor may seek enforcement such as an attachment of earnings, charging order or warrant of control. | Get advice promptly about the specific notice, available objections and affordable payment options. |
Check if you really owe it
Are you sure you really owe the money? The first thing to establish is where the debt started and how much you really owe.
» TAKE ACTION NOW: Fill out the short debt form
Ask for an itemised balance and check any interest, fees and payments rather than assuming the amount is correct.
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
A missing original agreement does not automatically cancel an account. The documents and legal consequences depend on the debt and any specific statutory request.
An ordinary debt collector has no right to force entry or seize goods. A visit must comply with applicable contact and privacy rules; there is no blanket ban on every doorstep visit. FCA rules prohibit workplace visits without prior consent for regulated consumer-credit collection.
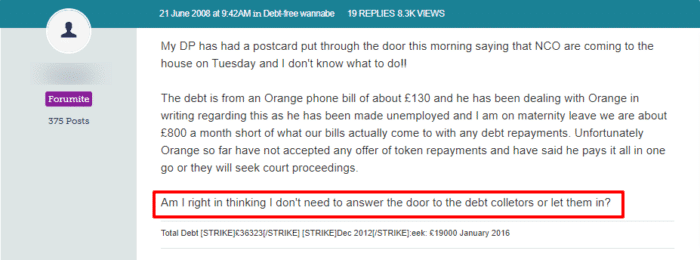
You do not have to admit an ordinary collector to your home. A forum example cannot establish whether the conduct in your own case is unreasonable.
Follow our ‘prove it’ guide with letter templates and get them to prove that you owe the money.
Can’t Afford to Pay?
If payment would leave you unable to meet essentials or priority bills, seek advice before agreeing to an arrangement.
If that’s your case and you cannot afford to repay the amount of debt on your NCO Europe account don’t worry.
For regulated-credit debts, appropriate forbearance must be considered. Ask about a sustainable arrangement, but do not assume a particular offer must be accepted.
However, just because NCO Europe Debt Collection is offering you a way to repay over time, don’t assume that this is the best option available to you.
If you have unsecured debts, you may be eligible for a debt solution.
There are several debt relief options available in the UK, so we recommend speaking to a debt charity for some free debt advice. Their advisers will be able to make sure that you choose the solution that is best for you.
Debt Management Plan (DMP)
A DMP is an informal debt solution that lets you pay off your debts via a single monthly payment.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement managed by an insolvency practitioner. Your proposal sets out payments, any assets involved and fees. Once approved, it binds the creditors and debts covered by it and restricts recovery action; it is not a blanket ban on necessary correspondence.
Many IVAs involve payments for five or six years, but the agreed term varies. Qualifying unpaid debt is normally released only on successful completion. An IVA affects your credit record, may involve assets or home equity, and can fail if its terms are not met.
IVA suitability depends on your debts, affordable contributions or available assets, fees and creditor approval. There is no universal rule that you must owe several thousand pounds to more than one creditor. Get independent debt advice and compare other options before agreeing to an IVA.
Trust Deed
IVAs are not available in Scotland. A Scottish money adviser can compare a protected trust deed, the Debt Arrangement Scheme, sequestration and informal arrangements; a trust deed is not compulsory.
A protected trust deed is a Scottish insolvency arrangement, usually lasting at least four years of contributions. It can discharge qualifying unpaid debt on successful completion, but fees apply and your home or other assets may be at risk. Covered creditors cannot pursue payment outside it, but can still send required documents.
Debt Relief Order (DRO)
In England and Wales, a DRO may suit an eligible non-homeowner with low surplus income, limited assets and qualifying debts within the £50,000 limit. Detailed income, asset, vehicle and residence rules apply. An approved debt adviser checks eligibility and submits the application to the Insolvency Service.
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Continue paying essential ongoing bills and excluded debts. A DRO does not prohibit every required creditor notice.
A DRO normally lasts 12 months. If it remains in force, the qualifying debts listed in it are normally discharged at the end. You must report relevant changes and continue paying ongoing bills and excluded debts, such as court fines and student loans.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish version of bankruptcy.
Scotland’s Minimal Asset Process is a route into bankruptcy for people who meet its conditions. Its application fee has been removed. Ask an approved Scottish money adviser to compare it with the alternatives and explain the effects on assets, credit and income.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Is It Possible to Write Off My Debts?
A creditor may consider a reduced settlement or discretionary write-off, but acceptance is not guaranteed. Making an offer can also affect an old debt’s limitation position, so take advice first.
Negotiating with debt collectors can be tricky so you can use our free letter template as a guide when you write to ask them to accept your settlement offer.
Keep in mind that they are under no obligation to accept your offer.
Offer only what you can afford and obtain written acceptance explaining whether the payment settles the liability, what happens to the remaining balance and how the account will be reported.
There are some options to explore that can wipe out some of the debt, and some we have mentioned already. These are:
You can learn more about these in our debt solution guides.
How Do You Complain About Them?
An ordinary debt collector has no right to force entry or seize goods. A visit must comply with applicable contact and privacy rules; there is no blanket ban on every doorstep visit. FCA rules prohibit workplace visits without prior consent for regulated consumer-credit collection. A collector must protect your privacy and must not disclose a debt to an unrelated person without a lawful basis. Contact with someone you have authorised, such as a debt adviser, is different. Keep evidence of any improper disclosure and complain.
If they violate these rules, you can complain.
Make your first complaint to NCO Europe so that they have the chance to sort out the issue themselves.
If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
For an eligible complaint, the Ombudsman can require a remedy or compensation where appropriate. It does not impose regulatory fines.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
NCO Debt Collectors Contact Details
| Company name: | NCO Europe Ltd |
| Other names: | NCO Europe Debt Collection |
| Company number: | 03122581 |
| Website: | https://www.ncoeurope.com |
| Phone number: | 0330 060 1500 Mon – Thurs: 8am to 8pm Friday 8am to 7pm Saturday: 8:30am to 1pm Sunday: Closed |
| Email address: | enquiries@ncoeurope.com |
| Registered office: | New City House, 57-63 Ringway, Preston, Lancashire, PR1 1AF |
References





