


Resolvecall Debt Letters and Visits: Your Rights and Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Received a letter or visit from Resolvecall? Check the sender, creditor and account before sharing information or agreeing to payment.
We’re here to help you. Here is what you will learn from this article:
- How to find out if the debt is really yours. If it’s not, you won’t need to pay!
- The ways to ask Resolvecall to leave you alone.
- The right ways to set up a plan to pay the debt.
- If there is a chance to wipe off your debt.
You can ask for written information, suitable contact arrangements and free independent debt advice.
We’re here to share our knowledge and help you figure out what the next steps are. Let’s dive in!
How Do You Ask Them to Prove the Debt?
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
The purpose of this letter is to get them to actively tell you the details about the debt so you can either accept it or challenge it.
An investigation may identify an error or require further evidence. A proof request does not guarantee that the account closes or all contact stops.
If you don’t know where to start, you can use our free letter template as a guide.
An old account needs a limitation or prescription assessment. Its age alone does not determine the result.
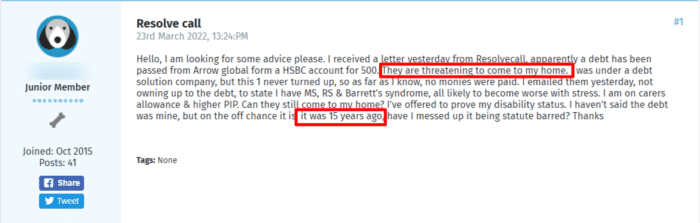
For many unsecured debts in England and Wales, the usual limitation period is six years from the relevant cause of action, not simply the last phone call. A payment, qualifying written acknowledgement or court proceedings can affect the position. Scotland usually has a five-year prescription period for many ordinary debts, with different rules and exceptions. Court judgments, secured debts and some tax debts require separate advice. Get free debt advice before paying or acknowledging an old debt; do not ignore court papers.
In England and Wales, limitation can provide a defence to a court claim; Scottish prescription can extinguish an obligation.
Judgments, secured debts and tax debts have separate rules, so do not apply an ordinary consumer-debt time limit indiscriminately.
A CCJ does not expire merely because its credit-file entry disappears, but later enforcement can require permission or face other restrictions.
Different Responses to Prove-the-Debt Letters
The firm may investigate, request information from its client, provide documents or identify an error.
If they contacted you because your name matched someone who did owe the debt, they may write to you to say that the debt no longer applies, and they will not contact you again.
If a reply only says you have been traced, check whether it addresses the specific account and dispute.
Explain any unresolved dispute and ask for the missing evidence. Do not ignore a genuine Letter of Claim or court papers.
There is also the possibility that Resolvecall will reply with genuine evidence that you owe them the debt.
But what is classed as genuine evidence and proof?
Relevant evidence may include an agreement, account statements, bills, payment history or assignment information, depending on the debt.
Not every enforceable agreement requires production of an original wet-ink signature. Specific Consumer Credit Act requests have their own rules and consequences.
A disputed signature or suspected fraud needs a specific explanation and investigation; there is no basis for implying that Resolvecall routinely forges signatures.
If payment is unaffordable, an adviser can compare repayment and formal solutions. Each has different effects on included debts and collection activity.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What If You Owe the Debt?
Check the evidence, enforceability and affordability before paying. Get advice first if an old debt may be affected by limitation.
Resolvecall’s website says it acts for clients. Verify the named creditor and collection instruction rather than assuming Resolvecall owns the account.
If you’re struggling with debt and repaying is not possible because you simply do not have enough money to pay it, you should still make contact with Resolvecall and explain your circumstances.
Ask about a sustainable arrangement based on your budget after essentials and priority bills.
Obtain written terms and confirmation of any recovery pause. An informal payment plan does not automatically prevent every future legal step.
Just make sure that you get a copy of your payment plan in writing before you make your first payment. This will keep your records up-to-date and make it much more difficult for Resolvecall to challenge you about this debt later!
Before you negotiate a payment schedule with Resolvecall, make sure you know the exact amount you can afford to repay.
You need to be realistic about your finances at this point – agreeing to a payment plan that you can’t afford is only going to make your financial situation worse.
To do this, create a budget and plan for all your essential expenses against your income. Some UK debt charities can help you do this and may even be able to communicate with Resolvecall on your behalf.
What If They Come to Your Home?
Resolvecall employs staff to visit people who owe debt at their homes. You do not need to welcome these people inside if you do not want to.
A visit must comply with applicable contact and dispute rules. Whether conduct is harassment depends on the circumstances, not simply whether you received an appointment notice.
An ordinary debt collector has no right to force entry or seize goods. A visit must comply with applicable contact and privacy rules; there is no blanket ban on every doorstep visit. FCA rules prohibit workplace visits without prior consent for regulated consumer-credit collection.
You can check a visitor’s identity without admitting them. Verify the instruction independently with the creditor or official Resolvecall contact details.
If they arrive and you are not home, reviews left by people chased by Resolvecall said the caller left a note asking them to call.
A calling card is not a court order. An ordinary collector cannot force entry or seize goods, and a CCJ alone does not give it bailiff powers. Check genuine correspondence and deadlines.
If you are home and want to know what the Resolvecall employee has come to say but do not want to deal with them directly, you should ask for them to write down what they are here for.
It is likely that these people are at your home to discuss ways to clear the debt and may want to come up with a repayment plan. If this is something you want to do, then you could do it with them in person or you could make arrangements to do it over the phone.
If you do invite them inside, they must leave as soon as you ask them to.
Your Rights With Debt Collectors
It’s important to understand your rights when dealing with debt collectors. That’s why we’ve created this table, which explains what they can and can’t do. To learn more about your rights, make sure to check out our detailed article.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Repayment and Debt-Solution Options
- Snowball method: targets smaller balances first while maintaining required payments elsewhere. It is not a formal debt solution and is not automatically best; prioritising higher-interest debt may cost less.
Any credit effect depends on payment history and the wider record. No budgeting method guarantees a higher score.
- DMP: an informal arrangement for affordable payments towards suitable debts. It does not automatically bind every creditor or stop legal action; provider fees may apply. For regulated credit, if the firm has put a repayment arrangement in place as forbearance and you meet its terms, it must reduce, waive or cancel further interest and charges enough to prevent the debt increasing during that arrangement.
- IVA: An IVA is a formal arrangement administered by an insolvency practitioner. Its approved terms govern contributions, assets and fees; only covered debts remaining on successful completion are released. It does not ban every required creditor communication. There is no universal statutory minimum debt or requirement for two creditors. Suitability depends on your debts, assets, affordable contribution or lump sum and creditor approval. Compare alternatives through independent debt advice. It does not guarantee protection of home equity.
- DRO: During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Continue paying essential ongoing bills and excluded debts. A DRO does not prohibit every required creditor notice.
- Bankruptcy: a formal option with consequences for assets, income, credit and some jobs. Obtain advice before applying.
- Protected trust deed: A protected trust deed is one possible Scottish insolvency option, normally involving four years of contributions and consideration of assets. It has different rules from an IVA. A Scottish money adviser can also consider the Debt Arrangement Scheme, bankruptcy and informal arrangements.
- Sequestration – The Scottish equivalent of bankruptcy.
- MAP: Scotland’s Minimal Asset Process is a route into bankruptcy for people who meet its conditions. Its application fee has been removed. Ask an approved Scottish money adviser to compare it with the alternatives and explain the effects on assets, credit and income.
We have a detailed post on what your debt options are here.
If you are considering a debt solution, we recommend that you speak to a debt charity for free advice. Their advisers can help you find the best option for you.
How Can You Manage Contact?
For regulated consumer credit collection, FCA rules require firms to give due regard to reasonable requests about when, where and how they contact you. You can ask for letters or emails instead of calls and explain any health or accessibility needs. This is not an automatic ban on every call or required notice. Keep a record of unreasonable contact and complain if your request is not properly considered. A formal solution may restrict recovery of included debts, but does not ban every required communication.
There are pros and cons to all debt solutions so it is important to consider your options carefully. You should speak to a debt charity if you are considering a debt solution.
We have included some links above to a few organisations that offer free debt counselling services in the UK.
» TAKE ACTION NOW: Fill out the short debt form
Can You Make a Complaint Against Them?
If you think there is an issue, your first port of call should be filing a complaint against Resolvecall to their main office.
You need to give them the oppurtunity to sort out your problem before you escalate the matter!
Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
The FCA supervises firms and considers reports of misconduct but does not resolve an individual complaint or award compensation. The Financial Ombudsman can require redress for an eligible complaint, not impose regulatory fines.
References





