


Student finance overpayments: checking the amount and repayment options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Did you get a letter saying you owe money because of a student loan overpayment? This can be a shock, and you might have lots of questions.
This guide is here to help. Each month, over 170,000 people visit our website seeking advice on debt matters.
In this article, we’ll explain:
- What a student loan overpayment is, and why you might have one.
- If you need to pay back the money straight away.
- How to sort out the overpayment if it wasn’t your fault.
- How this might affect your credit score.
- What might happen if you choose not to pay.
Unfortunately, nearly half of the individuals who deal with debt collection agencies have experienced harassment or aggression1. We understand what you’re going through.
Don’t worry; we’re ready to guide you through the details. Let’s start by learning more about student loan overpayments.
What is a student loan overpayment?
A student loan overpayment is when Student Finance pays you more than you’re entitled to.
There are several reasons why you might be overpaid by Student Finance, such as:
- You changed course
- Your course length changed or your new course is shorter
- Your personal circumstances have changed, especially if you have children
- Your living arrangements have changed, such as moving in with parents
- You changed universities, such as moving from a London university to one outside of London
- You stopped studying at university before your course ended – but after receiving a new term loan
Leaving a course can lead to a reassessment. It is normally the part covering a period for which you were not entitled, rather than every payment already received, that becomes an overpayment.
Unfortunately, many people have received a letter from Student Loan Overpayment Debt Collection and are unsure of their rights. By searching online forums, you’ll soon notice that you’re not alone…
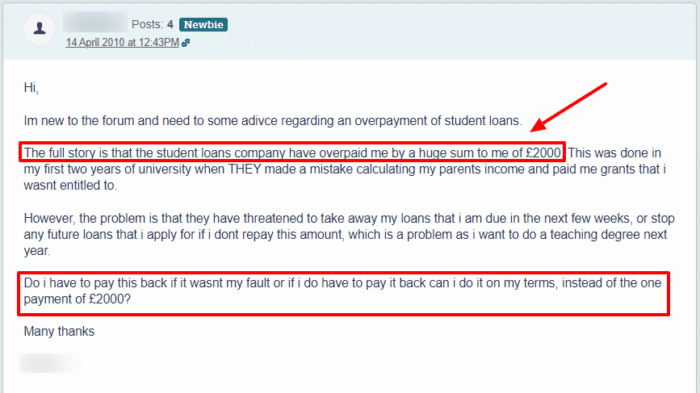
Source: https://forums.moneysavingexpert.com/discussion/2404361/student-loan-overpayment-help
But don’t worry. We’re here to help you understand your options.
Your Rights With Debt Collectors
SLC may refer an unpaid amount for collection. A referral does not authorise intimidation or give an ordinary collector bailiff powers.
To avoid any unpleasant situations, it’s important to know your rights. That’s why I’ve put together this quick table that explains what debt collectors are allowed to do. If you’d like to learn more, please read our complete guide.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
A word on student loan repayment overpayments
Student loan overpayment is a term that could be used in another situation.
When you’ve finished university and repaying your loan, there’s a chance you could end up repaying too much within the tax year. There are also many reasons this could happen.
If you believe too much has been taken in repayments, check SLC’s refund rules and contact it through official details. A refund of excess repayments is different from recovery of finance paid to you in error.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Do I have to pay it back?
A confirmed recoverable overpayment normally must be repaid, but you can ask for the calculation and challenge an entitlement error through the appropriate process.
You may be allowed to make your Student Finance repayments over several months or on a fixed repayment schedule.
» TAKE ACTION NOW: Fill out the short debt form
Do I have to pay back student loan overpayment if it wasn’t my fault?
An administrative mistake does not automatically remove the duty to repay. Ask for the decision and calculation, and use the complaint or appeal route if you dispute them.
This can be quite frustrating, but as we discuss below, there are ways to make the repayment more affordable.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How do you repay?
How you repay a student loan overpayment debt depends on whether you’re still receiving student loan payments or not.
If you return to study, recovery may be made from later student-finance payments under the relevant rules. The treatment depends on the type of funding and course dates; ask SLC about any hardship.
When you’re no longer receiving student loan payments, the overpayment debt needs to be repaid as a lump sum or over multiple instalments. This can be discussed and negotiated directly with Student Finance.
There is no minimum amount of income you have to receive before repaying an overpayment like there is with general student loan repayments. You could even be asked to repay a student loan overpayment if you’re currently out of work.
Further details can be found on this dedicated student loan overpayment page.
Will it affect credit score?
An income-contingent student loan is not normally reported like an ordinary credit account. However, court action leading to a registered judgment can affect credit.
Do not treat that general reporting rule as a guarantee that an overpayment dispute or all types of student-loan enforcement can never affect your credit record. See related guidance.
Can you set up a repayment plan?
A student finance overpayment repayment plan can be set up when you cannot afford to repay the debt in one go.
SLC is willing to listen to your specific situation and is often accommodating to help you repay the debt in a manner that works for you.
Ask SLC to consider an affordable arrangement and explain any hardship. Acceptance of the exact instalment you propose is not guaranteed.
But if this support isn’t enough, there may be a way you can get further help…
What happens if you don’t repay?
You will be contacted and requested to pay If you don’t repay your student loan overpayment debt after the first letter.
This can escalate to a stressful student loan overpayment debt collection process, which is best avoided.
Can Student Loans send bailiffs?
A collector is not a bailiff. Further court action and a valid enforcement authority would normally be needed before bailiffs could take control of goods for this type of debt. Contacting SLC can help but does not guarantee enforcement is avoided.
Keep in mind that debt collectors and bailiffs are different. We recently spoke to the Mirror about them. While a bailiff may be permitted to take your possessions, a debt collector never can. All they are allowed to do is ask for a payment.
Does student debt ever get written off?
Write-off rules differ by loan plan and funding type. The normal write-off date for the main loan should not be assumed to cancel a separately recoverable grant or loan overpayment.
Limitation is a separate issue from statutory loan cancellation. Rules differ between income-contingent loans, older mortgage-style loans, overpayments and judgments; obtain advice about the specific debt.
Plan 1
- For Plan 1 where the first loan payment for the course was on or after 1 September 2006, cancellation is normally 25 years after the April you were first due to repay, not the date you first actually paid.
- If you had your first loan payment before 1/9/2006: your loans will be written off when you’re 65.
Plan 2
Plan 2 loans are normally written off 30 years after the April you were first due to repay.
Plan 4
- For Plan 4 where the first loan payment was on or after 1 August 2007, the period is normally 30 years after the April you were first due to repay.
- For earlier Plan 4 loans, cancellation is normally at age 65 or 30 years after the April you were first due to repay, whichever is earlier.
Plan 5
Plan 5 loans are normally written off 40 years after the April you were first due to repay.
Postgraduate Loans
Postgraduate Loan plan balances for England and Wales are normally written off 30 years after the April you were first due to repay.
For postgraduate students in Northern Ireland, you are on Plan 1.
For postgraduate students in Scotland, you are on Plan 4.
Death
Student Loans Company (SLC) will cancel loans of someone who has died.
They will only cancel the loans on receipt of evidence that the person has died – this can include an original death certificate – and their Customer Reference Number.
Onset of Disability
SLC may cancel a loan where illness or disability means you can no longer work and the applicable conditions are met. Receipt of a disability benefit alone does not automatically establish entitlement to cancellation.
Ask SLC which medical and benefit evidence is required for your case, and provide the customer reference number.
Benefits mentioned in the cancellation guidance can include the following, but evidence and eligibility still need to be assessed:
- Disability Living Allowance
- Industrial Injuries Benefit
- Severe Disablement Allowance
- Personal Independence Payments.
References





