01389493417: Check Opos Calls and Respond Safely


Quick answer
If a caller using 01389493417 says they are from Opos, verify the contact independently. A displayed number does not prove the caller’s identity.
Opos Limited is a debt collection business. This guide explains how to check the account and respond safely.
Choose the right contact route
- Check an account: contact Opos through its official website, then ask for the creditor, reference and balance.
- Repeated calls: keep a dated call record and explain your communication preferences to the verified firm.
- Raise a complaint: use the firm’s complaints procedure and keep its response.
Read about contact preferences · Read the complaints guidance
Worried about paying the debt they’re calling about?
Talk through your debts, your budget and your options with The Debt Advice Service.
Complete the form to request a free advice call. There’s no obligation to take a debt solution.
This requests a call from The Debt Advice Service, not contact with the debt collector. It does not extend any court or enforcement deadline.
Advertisement. MoneyNerd introduces enquiries to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. We do not provide debt advice. If you submit an enquiry, your details are shared with their team so they can contact you.
Some debt solutions have fees and may affect your credit rating and assets. MoneyNerd may receive a fee if you go ahead with a solution. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Who Called Me?
Do not rely on the number 01389493417 alone. Use Opos’s official website to check a call or letter; its current general enquiry number is 0141 428 3990.
Our detailed Opos guide explains the company’s role and the options available when you receive a debt demand.
Can I ignore the calls?
You do not have to answer an unexpected call. You can contact Opos through independently verified details and ask for written information instead.
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
Managing collection calls could also reduce your anxiety about the situation.
Do not give payment details or sensitive information to an unexpected caller. Hang up and contact the organisation through details you find independently on its official website. Once you have verified it, reasonable identity checks protect your privacy: a genuine collector should check that it is speaking to the right person before disclosing account details.
In most cases, these types of calls usually occur after a debtor hasn’t responded to a debt letter from the company. It can be better to deal with this letter.
The best response depends on whether you recognise the debt, dispute it or need help paying. Do not ignore a Letter of Claim or court papers.
For many unsecured debts in England and Wales, the usual limitation period is six years from the relevant cause of action, not simply the last phone call. A payment, qualifying written acknowledgement or court proceedings can affect the position. Scotland usually has a five-year prescription period for many ordinary debts, with different rules and exceptions. Court judgments, secured debts and some tax debts require separate advice. Get free debt advice before paying or acknowledging an old debt; do not ignore court papers.
Why have they contacted me?
A genuine enquiry may concern an account the caller is collecting, but it can also involve a wrong number or a disputed account. Check the firm independently and ask which creditor, account reference and balance the enquiry concerns.
If you recognise the debt but cannot afford the payments, use the advice-call option below. For questions about the account itself, contact the verified collector.
An online forum account describes receiving repeated messages. This is an individual report, not proof that every Opos contact breaches the rules.
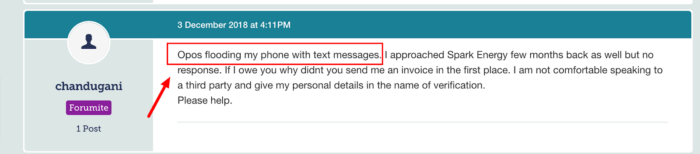
Source: https://forums.moneysavingexpert.com/discussion/comment/76315502#Comment_76315502
Ignoring genuine correspondence can leave a dispute unresolved and may lead to further action. The next step is not automatic and depends on the debt.
To offer you a quick insight into the average timeline adopted by debt collectors, I’ve created this table. To better understand the debt collection process, be sure to explore our detailed breakdown of the debt collection timeline.
| Possible stage | What can happen | What to do |
|---|---|---|
| Missed payments | The creditor or collector may contact you, apply contractual charges or issue required notices. There is no single timetable for every debt. | Check the debt and contact the creditor early. Prioritise essential bills and seek free debt advice. |
| Collection activity | Letters, calls or a proposed visit may follow. A collection agent has no power to seize your belongings. | Ask for identification and evidence of the debt. You do not have to let a debt collector into your home. |
| Letter of claim | A creditor may send a formal pre-action letter before making a claim. | Follow the response deadline and get advice; do not ignore it. |
| Court claim | In England and Wales, a creditor may apply for a county court judgment. A judgment and later enforcement are separate stages. | Respond to the claim by the court deadline, whether admitting it, disputing it or asking for time to pay. Attend if the court requires a hearing. |
| Enforcement after judgment | Where legally permitted, a creditor may seek enforcement such as an attachment of earnings, charging order or warrant of control. | Get advice promptly about the specific notice, available objections and affordable payment options. |
More than one call or text is not automatically unlawful. Excessive, threatening or unreasonably timed contact can be grounds for a complaint.
Worried about paying the debt they’re calling about?
Talk through your debts, your budget and your options with The Debt Advice Service.
Complete the form to request a free advice call. There’s no obligation to take a debt solution.
This requests a call from The Debt Advice Service, not contact with the debt collector. It does not extend any court or enforcement deadline.
Advertisement. MoneyNerd introduces enquiries to The Debt Advice Service, a trading style of Pacific Financial Solutions Limited. We do not provide debt advice. If you submit an enquiry, your details are shared with their team so they can contact you.
Some debt solutions have fees and may affect your credit rating and assets. MoneyNerd may receive a fee if you go ahead with a solution. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
How do I stop them from contacting me?
You can ask Opos to change how it contacts you. Legitimate account notices may still be necessary.
That said, excessive contact can cause financial stress, and your mental health could be affected.
For regulated consumer credit collection, FCA rules require firms to give due regard to reasonable requests about when, where and how they contact you. You can ask for letters or emails instead of calls and explain any health or accessibility needs. This is not an automatic ban on every call or required notice. Keep a record of unreasonable contact and complain if your request is not properly considered.
Explain the effect of the contact, keep evidence and complain if the firm does not properly consider your reasonable needs.
Only agree to payment after checking the creditor, amount and your liability. If the debt is old or disputed, obtain advice first. If it is valid but unaffordable, ask about affordable repayments and free debt advice.
How do I Complain about the calls?
If you think that Opos Debt Collectors has been unreasonable or behaved inappropriately, you can make a complaint. You can also make a complaint if you feel that they have broken any of the Financial Conduct Authority’s (FCA) guidelines.
Make your first complaint to Opos so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
Opos Debt Collectors Contact Details
| General enquiries | 0141 428 3990 |
| [email protected] | |
| Complaints email | [email protected] |
| Postal address | Opos Limited 15 Meadowbank Street Dumbarton G82 1JR |
| Official website | Opos Limited |
References