


01482483281: Verify Wescot Calls and Your Rights


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
If a caller using 01482483281 claims to be Wescot, check the contact independently before sharing information or paying.
This guide explains how to verify a debt collection call and respond to the account it concerns.
In this article, we will give you clear and easy-to-understand information about:
- Who Wescot Debt Collectors are.
- Why you have been contacted by 01482483281.
- How to handle a call from Wescot Debt Collectors.
- How to ask for reasonable contact arrangements.
You can ask for written information and obtain free debt advice if a collection call worries you.
Let’s figure out the best way to handle this situation!
Who called you?
A displayed number cannot prove that Wescot called you. Verify the contact through Wescot’s official website or the creditor that says it instructed Wescot.
Wescot Credit Services is a debt collection business. Its role and the action available depend on the account it is collecting.
Our Wescot guide explains the difference between collecting a debt and enforcing a court judgment.
You can read our Wescot Debt Collection guide for help dealing with them and your debts.
Why have they made contact?
A verified contact may concern an unpaid account or an attempt to trace its holder. Tell the verified firm if it has contacted the wrong person.
The forum post below describes one person’s experience. It is not proof that every repeated call breaches FCA rules.
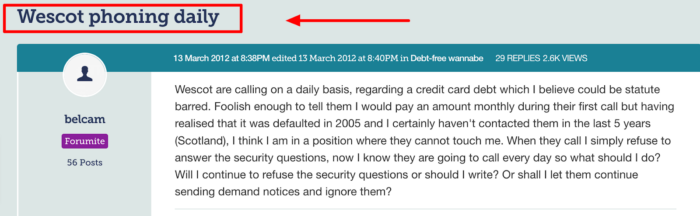
Source: https://forums.moneysavingexpert.com/discussion/3849213/wescot-phoning-daily
You can complain about excessive, threatening or unreasonably timed contact.
Do not assume calls mean that you received or ignored an earlier letter.
Where the England and Wales Debt Claims Protocol applies, a creditor normally sends a Letter of Claim before issuing a claim. A call is not a court order, and legal notices should be dealt with separately.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Can you ignore their calls?
You do not have to discuss an account by phone. Ask for written information and respond to genuine legal notices within the applicable deadlines.
If you have no account information, contact the firm independently rather than relying on an incoming call.
This could also reduce your stress levels.
If you do answer the call, don’t provide the caller with your personal information. You’re not obligated to do so.
Do not give payment details or sensitive information to an unexpected caller. Hang up and contact the organisation through details you find independently on its official website. Once you have verified it, reasonable identity checks protect your privacy: a genuine collector should check that it is speaking to the right person before disclosing account details.
An enforceable unpaid debt may lead to a court claim. A CCJ and any later enforcement require the relevant legal steps; missing a call does not automatically send bailiffs to your home.
We always recommend responding to debt collectors – even just to question the debt’s validity. You have the right to request proof of the debt.
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
How do you stop them from contacting you?
You can ask Wescot to limit calls and explain which contact method is suitable for you.
For regulated consumer credit collection, FCA rules require firms to give due regard to reasonable requests about when, where and how they contact you. You can ask for letters or emails instead of calls and explain any health or accessibility needs. This is not an automatic ban on every call or required notice. Keep a record of unreasonable contact and complain if your request is not properly considered.
It’s best to do this in writing and keep a copy of the letter in case you need to complain later.
Put a reasonable request for written contact in your complaint if calls are causing difficulty. Keep copies of what you send and the response.
» TAKE ACTION NOW: Fill out the short debt form
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How do you complain?
If you provided Wescot Debt Collection with your communication preferences and they ignored them, you should lodge a complaint directly to Wescot.
Complain to the firm first and keep copies and call logs. For an eligible regulated financial complaint, you can normally approach the Financial Ombudsman Service after a final response or after eight weeks without one, usually within six months of the final response. The Ombudsman can require a remedy or compensation; it does not impose regulatory fines. Tax, council and other non-credit debts may have different complaint routes.
This service will review the series of events, preferably with proof supplied by you.
Call logs can help show frequency and timing. The Ombudsman may require a remedy for an eligible complaint; it does not punish firms with regulatory fines.
Know Your Rights
Even while recovering a legitimate debt, debt collectors must abide by certain rules and have limited rights when doing their job.
Knowing your rights and those of the debt collectors visiting/contacting you is key to ensuring that they don’t take advantage of you during the process.
Please check out our related article on the topic and take a quick look at the table below to learn more.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Wescot Credit Services Debt Collection Contact Details
| Telephone number | 01482 484673 |
| Email address | [email protected] |
| Postal address | Wescot Credit Services Limited PO Box 137 Hull HU2 8HF |
References





