Can I Use a Home Equity Loan to Buy Another House?


Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Loans Warehouse is a credit broker, not a lender. Approval and terms depend on checks. Compare fees, interest and the total amount repayable. A longer term may increase the overall cost. MoneyNerd introduces enquiries and may receive a referral fee.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Are you wondering how to use the value of your house to buy another? This is a common question and we’re here to help.
This article will explain how you can use a Home Equity Loan to buy a second house. We’ll guide you through:
- Understanding what home equity is.
- Knowing the true cost of a bad home equity loan.
- The process of applying for a home equity loan.
- Weighing up the good and bad sides of home equity loans.
- Using home equity to buy a second home or an investment property.
Borrowing against your home to buy another property involves costs and the risk of losing the secured home if payments are not maintained. This guide explains the main checks.
Is it possible to do it?
Borrowing against an existing property may fund another purchase if the secured lender permits the use and any new mortgage lender accepts the borrowed deposit. All borrowing must be disclosed and affordable. See related guidance.
Both lenders must assess the funding structure and commitments. Allow for property tax, fees, repairs and, for investments, periods without rent; a rental return or future price increase is not guaranteed. See related guidance.
How much can I use?
Loan-to-value compares secured borrowing with the property’s value, not with the equity alone. A second-charge lender normally considers the existing mortgage and proposed loan together, alongside affordability and credit criteria. There is no universal percentage of equity you can borrow.
Enquire about a secured loan through Loans Warehouse, a credit broker, not a lender. Approval and terms depend on checks. Compare the full cost before applying. MoneyNerd may receive a referral fee. Your home may be repossessed if you do not keep up repayments on a loan secured against it.
Can I use it to pay off my current mortgage?
A second-charge loan does not normally replace the first mortgage. If you want to refinance that mortgage, compare a remortgage or other suitable arrangement, including settlement charges and the total cost.
Buying a second home vs an investment property
The difference between buying a second property and buying a new property to generate rental income is usually clear-cut. The former is purchasing a home you will use exclusively at different times of the year. For example, buying a house by the coast or in the Lake District for summer holidays with the family.
The latter is when you buy a second property that will be rented out to other people who pay to live there – or pay to holiday there. In this case, you’ll usually require a buy-to-let mortgage instead of a standard residential mortgage.
Explore secured loan options
Loans Warehouse is a credit broker, not a lender. You can enquire about options based on your circumstances. Approval and terms depend on lender checks; an enquiry is not a guaranteed offer.
Compare the interest rate, fees, monthly payments and total amount repayable. A longer repayment term can increase the overall cost. Consolidating unsecured debts into a secured loan puts your home at risk.
MoneyNerd introduces enquiries to Loans Warehouse and may receive a referral fee. Broker and lender fees may apply and should be explained before you proceed.
Your home may be repossessed if you do not keep up repayments on a loan secured against it.
What are the Advantages?
The benefits of using a home equity loan to buy a second house as a rental investment are:
- A larger deposit may change the new mortgage’s terms, but a deposit funded by debt must be accepted by the lender and the additional payments included in affordability checks.
- Rates may differ between secured and unsecured options; compare the total costs and terms rather than assuming a home-equity loan is cheapest.
What are the Disadvantages?
Just like any source of credit, there are also downsides to using a home equity loan, such as:
- Both properties can be exposed to market falls, and the home securing the additional loan is at risk if payments are missed.
- Debts are less streamlined – instead of having the same number of mortgages as homes, you will also have a home equity loan similar to a mortgage (but not the same!). Your debts are less streamlined and can be more tricky to manage.
- Fees and charges: check arrangement, broker, legal, valuation and early-repayment costs and when each is payable; there is no universal closing-cost charge.
Can I use a HELOC to get a second house?
A US-style home equity line of credit (HELOC) should not be assumed to be a standard UK product. Any UK revolving or drawdown secured facility has its own availability, fees and payment terms. Check whether interest or capital payments are required during the drawdown period and how the balance must be repaid.
- Check the facility limit, permitted use and whether funds remain available when needed
- Check whether rates are fixed or variable and how changes affect payments
- Check payments due during any drawdown period and the eventual capital repayment; do not assume payments start only after drawing ends
A second-property purchase needs a lender-approved funding structure, affordability assessment and a plan for all repayments.
A Loans Warehouse customer’s experience
Individual experiences vary. Compare the total cost, fees, repayment term and risks before applying. A lower monthly payment may mean paying more overall, and secured borrowing puts your home at risk if repayments are not maintained.
Polly
“This was by far possibly one of the nicest experiences I’ve had getting a secured loan.”
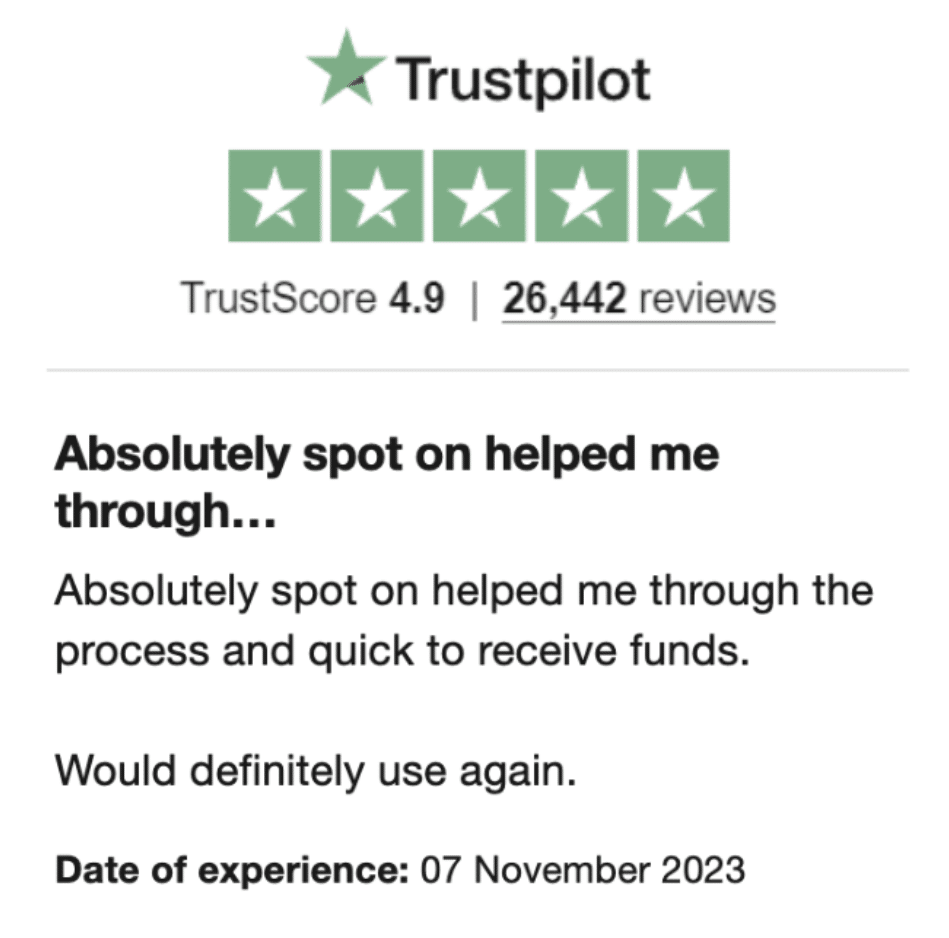
Reviews shown are for Loans Warehouse. Search powered by Loans Warehouse.
Can I get it with a poor credit score?
It’s not impossible to get a home equity loan, HELOC or remortgage with a bad credit history, but it is more complicated. Lenders prefer to lend to people with a track record of being able to repay their credit on time and in full, so securing a home equity loan with poor credit can be difficult.
You might still be offered a loan or a new mortgage, but you may have to pay more interest than those with a good credit score. Search the market to discover all your options. If you don’t qualify for other alternatives because of bad credit, prioritising improving your credit score is a good idea.
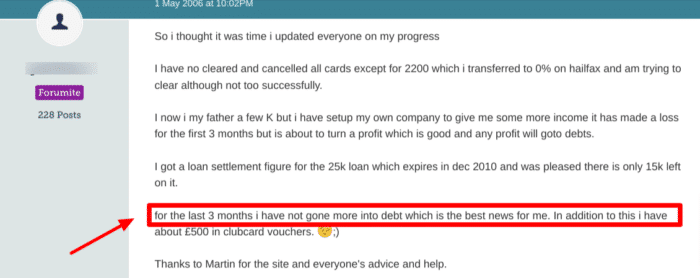
This MoneySavingExpert forum user was in a financial predicament and was looking for a way to get out of debt. Using advice from other forum users, he managed to get his financial situation under control.
Can I get a second loan?
Additional secured loans may be possible subject to existing lenders’ consent, charge priority, sufficient security and affordability. Disclose all existing mortgages and loans; further lending is not guaranteed.
When there is a second or third lien of credit, lenders can have more difficulty recovering money in the event of defaults and may be less inclined to lend to you.