Debt Info
Bailiffs

Cannot afford a court fine? Reviews and payment options

Scott Nelson MoneyNerd Janine Marsh MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Founder of MoneyNerd

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
&
Janine
Janine Marsh MoneyNerd

Janine Marsh

Former MoneyNerd Contributor

Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.

Learn more about Janine
· Oct 21st, 2026

Advertisement

Request a call from The Debt Advice Service

Total amount of debt?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
cant pay court fines

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.

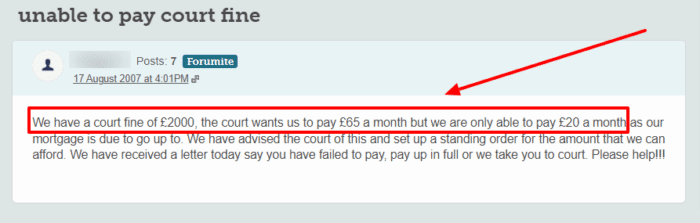
If you cannot afford a criminal court fine in England and Wales, contact the fines office promptly. Ask about reviewing the amount or payment terms and provide accurate financial information.

  •  What a court fine is and why you might have one.
  •  Steps to take if you can’t pay your fines.
  •  How a judge decides the amount of a fine.
  •  How court-fine payment difficulties differ from other debt problems.
  •  Options for appealing against a court fine.

This guide concerns criminal court fines, not every charge described as a “fine”. Civil parking penalties, private parking charges and fixed penalties have different challenge and enforcement procedures.

The available review and payment options depend on the court’s powers and your circumstances. A reduction or extension is not guaranteed.

So, if you’re troubled by unaffordable debt, struggling to pay court fines, or just need to know more about your situation, we’re here to help.

Let’s dive into what your options are.

Advertisement

Request a call from The Debt Advice Service

Criminal court fines in England and Wales are not written off by a Debt Relief Order or ordinary bankruptcy discharge. For difficulty paying a fine, contact the fines office promptly. The form below requests a call from The Debt Advice Service about your debt circumstances; it does not challenge a fine, change its payment terms or pause a deadline.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

What is a court fine?

A criminal fine is a financial sentence following conviction. Available penalties and maximum amounts depend on the offence and court. A large fine does not automatically come with a short prison sentence.

Must I pay my fines?

Criminal court fines, fixed penalties and civil penalty charge notices are different. Civil parking debt enforcement is not ordinary criminal fine enforcement and does not itself carry imprisonment for non-payment.

A private parking charge is a civil claim. It may increase or lead to a County Court claim if unpaid and enforceable, but neither a collection letter nor the charge itself is a criminal conviction. See related guidance.

Check the named creditor or authorised agent and the basis of the claim. Do not assume a particular debt purchaser is involved in every private parking case. See related guidance, related guidance.

Advertisement

How the introduction works

The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.

Options depend on your circumstances. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

What if I don’t pay?

Do not ignore a court fine because you cannot afford it. Contact the fines office promptly to discuss your circumstances.

If you are facing financial hardship and can’t afford to pay your court fines, you should follow the steps that I have talked through above. This includes:

  • Asking to pay in installments
  • Asking to pay over a longer period
  • Asking to pay at a later date.

If you cannot afford the amount demanded, contact the fines office or the enforcement agent named on the notice promptly. Explain your budget and ask what payment arrangements can be considered. Acceptance is not guaranteed, and a request does not suspend enforcement unless a pause is confirmed.

But if you just don’t pay, your situation is going to get worse.

The enforcement route depends on the order and notices already issued. Check each document and deadline, and contact the relevant fines office.

Further steps may include deductions, bailiff enforcement or a court hearing where the legal requirements are met. There is no single guaranteed sequence for every unpaid fine.

StepChange found that 90% of people who have been visited by a bailiff in the last 2 years identify as vulnerable. With over 50% reporting depression and more reporting stress and anxiety2.

If summoned, attend unless the court confirms you no longer need to. Paying the balance does not mean you should assume the hearing has been cancelled. See related guidance.

You can be arrested if you don’t go to the court summons. This hearing is your chance to show the court how much you can realistically pay without falling into severe financial hardship.

Take an accurate budget showing your income, essential spending and other commitments to any means hearing.

A free debt-advice organisation can help you prepare your budget and understand your options.

To request a call from The Debt Advice Service: Fill out the short debt form

This requests a callback; it does not change a court fine or pause enforcement or court deadlines.

What does the court fine you for?

A criminal fine is imposed for an offence under the relevant sentencing powers. The following notices should be distinguished from that sentence:

  • Fixed Penalty Notice: a statutory way to dispose of certain alleged offences, usually subject to payment and other conditions. It is not itself the same as a court sentence.
  • Penalty Charge Notice: a civil statutory penalty, commonly for council parking or traffic contraventions, with its own appeal and enforcement process.
  • Parking Charge Notice is not technically a fine because it’s given by a private company rather than a judge for parking infringements.

Advertisement

About The Debt Advice Service

Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.
Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

How does a judge determine fines?

Unless it’s a fixed penalty, the judge can determine your fine and also set the payment deadline by considering the nature of your crime and your financial situation.

You will get a notice of fine and a collection order with the following details after the hearing:

  • The fine amount
  • Payment deadline
  • Payment method(s)
  • The officer to contact if you’re unable to pay

Can I appeal against a court fine?

A challenge or review is not restricted to just two situations. The correct route depends on whether you dispute the conviction, sentence, financial information or the proceedings themselves. See related guidance.

Ask about a review where you cannot afford the fine or the court lacked accurate financial information

Seek prompt legal advice about an appeal, reopening or statutory declaration where the relevant grounds apply; deadlines differ

Advertisement

Request a call from The Debt Advice Service

Criminal court fines in England and Wales are not written off by a Debt Relief Order or ordinary bankruptcy discharge. For difficulty paying a fine, contact the fines office promptly. The form below requests a call from The Debt Advice Service about your debt circumstances; it does not challenge a fine, change its payment terms or pause a deadline.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Things I can do if I’m unable to pay

If you can’t afford a fine due to a financial situation, don’t just ignore it, as there are at least three things you can do to tackle the issue.

Court fines are very important and must be paid, or there could be consequences. Reach out to the fines officer before the payment deadline and do the following.

 1. Ask for a reduction

Yes. You can ask if you could get a reduction on your fine after explaining your situation, and you might get help via fine adjustment. The court may demand certain personal and financial information to help know how much you can afford.

2. Ask for an extension

You can ask about changing the due date or instalments and explain your budget. The court’s decision depends on the case; an extension is not automatically granted if a reduction is refused.

3. Look for alternative payment options

Another thing you can do if you can’t pay court fines is to provide alternative payment means. This could be by:

  • offering to pay in instalments
  • taking the fine from your benefits
  • deductions from your income
  • asking the court or a legal adviser about the appropriate review procedure for the specific order

Paying in instalments

You can negotiate with the court, stating that you wish to pay in instalments. Also, you need to stipulate the amount you can afford to pay weekly or monthly, and the court will consider your application and communicate their decision.

Report a material change in circumstances promptly. The court may be able to vary payment arrangements or review the fine under its legal powers, but not every financial order can be reduced in the same way.

Taking from your benefits

Deductions may be possible from certain benefits under the applicable rules. Tell the fines office which benefits you receive and ask what arrangement can be considered. Examples include:

  • Jobseeker’s Allowance
  • pension credit
  • Income Support
  • Eligible Employment and Support Allowance or Universal Credit, subject to the applicable deduction rules

Deductions from your income

Another alternative payment could be via your weekly or monthly earnings. You can ask the court to deduct the fine from your earnings and fill out a means enquiry form that tells the judge how much you earn weekly or monthly in order to stipulate the amount to be taken.

Deductions from earnings follow the applicable statutory scale and protected-earnings rules. Do not treat 40% or 20% as a universal maximum for every order and pay level.

Check the correct procedure for any frozen bank funds

An interim third-party debt order in civil proceedings has its own hardship-payment procedure. It should not be presented as a standard alternative for paying a criminal court fine. Seek advice about the actual order received.

Do not rely on a universal £5 minimum bank balance or assumed bank fee. The terms of the order, account and applicable procedure need to be checked.

References

  1. Citizens Advice – Debt Statistics and Bailiff Issues
  2. StepChange – Creditor and Debt Collector Conduct
Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine Marsh MoneyNerd
Debt Expert
Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.