


Can council tax arrears lead to a CCJ? Liability orders explained


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Council-tax liability orders differ from County Court judgments. Understand credit-file effects, enforcement and how to challenge a disputed bill.
What is a county court judgement?
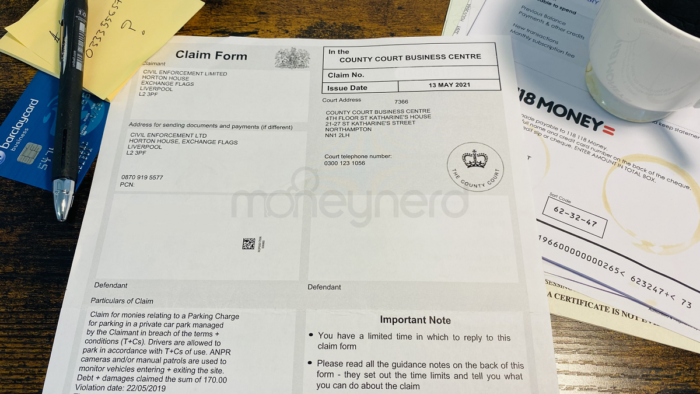
A County Court judgment (CCJ) is a civil court decision that money is owed. It can affect a credit record, normally for six years unless paid in full within one month and removed. It is not the usual court order used to collect council-tax arrears in England and Wales.
Council-tax liability orders are made by the magistrates’ court under a separate process. The rest of this guide concerns that process, not a County Court claim or its application forms.
Can you get one for council tax?
What is a liability order?
A liability order confirms that council tax is payable and gives the council further recovery powers. Recoverable legal costs can be added; there is no universal £20 total.
Options can include statutory deductions from employed earnings, an application for deductions from certain benefits, or enforcement agents. Wage and benefit deductions are separate procedures. Charging orders and bankruptcy require their own legal conditions and court processes; creditor bankruptcy generally requires at least £5,000 of qualifying debt.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Does it expire?
In England and Wales, the council generally has six years from the date a council-tax sum became due to apply for a liability order. This is not a six-year period restarted by your last payment. Once a liability order has been obtained in time, its enforcement is not automatically barred when the original bill reaches six years old. Ask the council for the order date and a breakdown, and get advice about the particular enforcement action. Scotland has a different recovery system.
Can I ignore it?
Do not ignore a liability order or related notices. Ask the council for a breakdown if the balance is disputed, and seek free debt advice if you cannot pay. Continued non-payment can lead to further lawful recovery and costs. Specific penalties or imprisonment require separate legal conditions; they do not follow automatically from ignoring an order.
Dealing with arrears
How to get deductions
Check Council Tax Reduction for low income and the available discounts or exemptions for your household. A 25% single-person discount normally applies where only one counted adult lives in the home. Some residents, including qualifying full-time students, are disregarded; there is no general restriction to students in their teens.
Ask the council to assess your circumstances and any discretionary hardship assistance. A benefit award does not automatically settle every council-tax bill.
| Debt Strategy | How It Can Help With Council Tax Arrears |
|---|---|
| Flexible Payment Arrangements | Local councils often offer the option to spread council tax payments over 12 months instead of the standard 10. |
| One-Off Payment | If affordable, pay the arrears or agree instalments. Any discretionary reduction must be assessed by the council; a lump sum does not automatically earn a discount. |
| Hardship Schemes | Council Tax Reduction (CTR) Discretionary Relief Hardship Funds Support for Vulnerable Individuals Current discretionary support (ask your council) Charitable Grants |
| Discounts and Exemptions | Check for eligibility for discounts (e.g., single-person discount of 25%) or exemptions (e.g., properties unoccupied due to the resident’s death, properties where everyone’s a full-time student, or someone qualifies to be disregarded because of severe mental impairment; the effect depends on the household and eligibility rules) |
| Deferred Payments | Some councils allow deferring payments wherein you’ll pay less now and make up for it later. |
| Challenge your Council Tax Band | If you believe your property’s council tax band is incorrect, you can challenge it to potentially lower future payments and refund previous overpayments. |
| Debt Solutions | Certain formal debt solutions like Debt Relief Orders (DRO), Bankruptcy, and Individual Voluntary Arrangements (IVA) can potentially write off council tax arrears, |
| Professional Debt Advice | UK residents can seek free advice from debt organizations and charities for council tax guidance tailored to their specific financial situation. |
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
How do I challenge it?
Start by identifying the dispute: the bill, liable person, discount, band or the procedure for making the liability order. The correct route and deadlines depend on that issue. There is no general 14-day County Court attachment-of-earnings appeal for a council-tax liability order.
Contact the council immediately with evidence, ask for its decision in writing, and obtain advice about any Valuation Tribunal appeal or court remedy that applies. Do not assume a complaint suspends payment or enforcement. If a hearing is listed, follow the summons and seek advice before the date. See the government appeal guide.
Can bailiffs force entry?
Can They Take Everything?
There are strict rules on what bailiffs can’t remove from your property, even if they are collecting for priority debts like council tax. These items include:
- Anything that belongs to someone else – this includes things that belong to your children
- Pets or service animals
- Vehicles, tools, or equipment that you need for your job or to study up to £1,350
- A mobility vehicle or any vehicle with a valid Blue Badge
- Anything permanently fitted to your home – kitchen units, etc.
Bailiffs also can’t take things that you need to live. These items can be anything that you use for your ‘basic domestic needs.’ They can take some of these things, but must leave you with:
- A table with enough chairs for everyone in your home
- Beds and bedding for everyone in your home
- A phone or mobile phone
- Any medicine or medical equipment that you need to care for someone
- A washing machine
- A cooker or microwave, and a fridge.
If you think that a bailiff has taken something that they shouldn’t, you need to complain immediately.
You can also contact a debt charity for some advice. I have listed several charities that offer free advice at the bottom of this page.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
What if I am a vulnerable person?
Tell the council and enforcement agent about any disability, serious illness, mental-health difficulty, bereavement, pregnancy or other circumstance affecting your ability to deal with enforcement. Explain the impact and any support or reasonable adjustment needed; a carer or adviser can help.
Vulnerability must be considered in the circumstances. It does not automatically cancel the debt or guarantee an indefinite pause. Ask for time to obtain advice, an appropriate contact method and confirmation of any agreed hold. Keep records and seek help promptly if the proposed visit could put you at risk.
Can you go to prison for arrears?
In England, imprisonment for council-tax non-payment is a last-resort procedure. The magistrates must investigate your means and find wilful refusal or culpable neglect; inability to afford the bill alone is not enough. The maximum is three months. Wales has abolished imprisonment for council-tax non-payment. Scotland uses a different enforcement system.
A later committal or means-enquiry summons requires urgent legal advice. Follow the court’s attendance instructions; failure to attend when required can result in an arrest warrant. If payment is made before the hearing, get confirmation about whether attendance is still needed.
How long can you be chased for the debt?
In England and Wales, the council generally has six years from the date a council-tax sum became due to apply for a liability order. This is not a six-year period restarted by your last payment. Once a liability order has been obtained in time, its enforcement is not automatically barred when the original bill reaches six years old. Ask the council for the order date and a breakdown, and get advice about the particular enforcement action. Scotland has a different recovery system.
See regulation 34 for the liability-order application limit. Get advice about the actual order and recovery action before relying on limitation.
Does it affect credit rating?
References





