


Credit Limits International Debt Letters: How to Respond


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Receiving a surprising letter from CLI International Debt Collectors can be a bit scary. But don’t worry; you are not alone in this. Over 170,000 people visit our website each month for advice on debt problems.
In this article, we will help you understand:
- Who CLI International Debt Collectors are, and if they are a real company
- Why they might be contacting you
- What to do if they get in touch with you
- If they can chase you for foreign debts
- What to do if you can’t afford to pay
Unfortunately, nearly half of the people who deal with debt collection agencies have experienced harassment or aggression1. Some of our team members have been there too.
We understand how you feel and are here to guide you through this process. Let’s dive in!
Why are Credit Limits International Debt Collectors getting in touch with you?
What should you do if CLI Collectors get in touch?
But don’t worry, below you’ll find what you can do if they get in touch.
» TAKE ACTION NOW: Fill out the short debt form
Check the details
If your debt is old, it may be statute-barred.
Many ordinary unsecured debts may become statute-barred after six years in England and Wales, or prescribed after five years in Scotland. The start date, debt type, payments, legally relevant acknowledgments and any court claim all matter. A creditor’s letter alone does not restart the period. Ask a debt adviser to check the facts before paying or admitting liability, and respond to any court papers on time.
If a limitation or prescription defence may apply, get advice before paying or admitting liability.
In England and Wales, limitation does not normally extinguish an ordinary contractual debt; in Scotland, prescription can do so. Court papers still require a timely response, and cross-border claims need separate advice.
Different rules apply to debts such as tax, council tax, mortgage shortfalls and debts already covered by a judgment or decree. A CCJ does not expire or cancel the debt when its six-year credit-file entry ends; some later enforcement needs court permission. Get advice on the particular debt and enforcement method.
Remember that UK debt laws have been set up to protect you as much as possible!
Take notes
Know Your Rights With Debt Collectors
If you’ve been contacted by CLI International Debt Collectors or any other debt collection company, it’s crucial to understand your rights to prevent unfair treatment.
Collectors must use lawful and reasonable contact methods and protect your personal information. Ordinary collectors cannot force entry or seize goods. For regulated consumer-credit collection, workplace visits generally require consent. Authorised advisers, joint debtors and people legally entitled to act for you are different from unrelated third parties.
If they violate these rules, you can complain.
Here’s a quick table that will help you better understand what debt collectors can and can’t do. If you want to learn more about your rights or require further advice, make sure to check out our detailed guide.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Paying up
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What If You Can’t Afford to Pay?
If CLI have proved that you owe the debt, but you can’t afford to pay, you may need to consider a debt solution.
There are several debt solutions available in the UK, so we recommend speaking to a debt charity to get some free advice before you start one.
Their advisors will be able to look at your finances in detail and be able to work out what solution will suit your finances best.
They may also offer financial literacy and debt management services to help you get back in control of your finances.
Debt Management Plan (DMP)
A DMP is an informal debt solution that lets you pay off your debts via a single monthly payment.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement managed by an insolvency practitioner. Your proposal sets out payments, any assets involved and fees. Once approved, it binds the creditors and debts covered by it and restricts recovery action; it is not a blanket ban on necessary correspondence.
Many IVAs involve payments for five or six years, but the agreed term varies. Qualifying unpaid debt is normally released only on successful completion. An IVA affects your credit record, may involve assets or home equity, and can fail if its terms are not met.
IVA suitability depends on your debts, affordable contributions or available assets, fees and creditor approval. There is no universal rule that you must owe several thousand pounds to more than one creditor. Get independent debt advice and compare other options before agreeing to an IVA.
Trust Deed
IVAs are not available in Scotland. A Scottish money adviser can compare a protected trust deed, the Debt Arrangement Scheme, sequestration and informal arrangements; a trust deed is not compulsory.
A protected trust deed is a Scottish insolvency arrangement, usually lasting at least four years of contributions. It can discharge qualifying unpaid debt on successful completion, but fees apply and your home or other assets may be at risk. Covered creditors cannot pursue payment outside it, but can still send required documents.
Debt Relief Order (DRO)
In England and Wales, a DRO may suit an eligible non-homeowner with low surplus income, limited assets and qualifying debts within the £50,000 limit. Detailed income, asset, vehicle and residence rules apply. An approved debt adviser checks eligibility and submits the application to the Insolvency Service.
While a DRO remains in force, listed qualifying debts are protected from most recovery action. This is not a ban on every necessary letter, and you must continue paying ongoing bills and excluded debts.
A DRO normally lasts 12 months. If it remains in force, the qualifying debts listed in it are normally discharged at the end. You must report relevant changes and continue paying ongoing bills and excluded debts, such as court fines and student loans.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish version of bankruptcy.If you have little income and no valuable assets, you may be able to apply for a minimal asset process bankruptcy (MAP). A MAP is a quicker, cheaper, and more straightforward version of sequestration, so worth considering.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Will Debt Affect Your Credit?
Your credit might be affected by CLI, but your credit report will already be marked by your missed payments with your original creditor.
A default, missed payments or a formal debt solution can affect your credit record; an ordinary collection letter is not itself a CCJ.
This can have an impact on your ability to get credit as you will be flagged as a ‘high-risk’ customer – someone who is likely to have issues paying back what they owe.
Credit reporting depends on the account and solution. Defaults normally remain for six years from the original default date; a sale does not restart that date. Formal insolvency records and informal arrangements have different reporting rules, and ending an entry does not guarantee approval for new credit.
Can They Chase You For Foreign Debts?
A creditor may seek cross-border recovery, but its rights depend on the governing law, jurisdiction, service rules and any process for recognising or enforcing a foreign judgment. An English collection firm does not have automatic court-enforcement powers everywhere in the world.
Take this example.
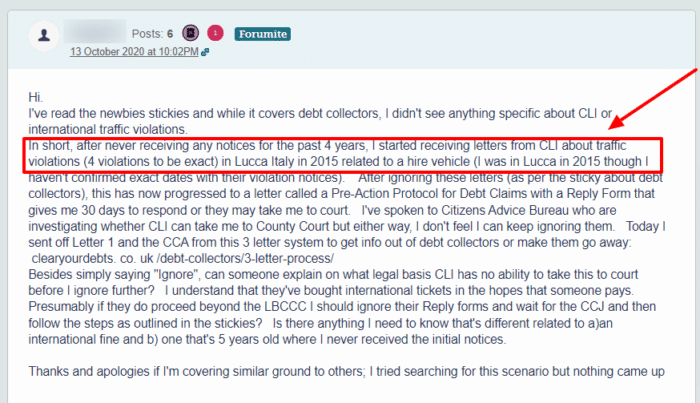
If you aren’t sure if you owe money for international debts, you should speak to a debt charity.
They will be able to give you specific advice, depending on what your debt is for and where it is in the debt collection process.
Credit Limit International Contact Details
References





