


Debt evidence request letter: UK template and its limits


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
If you do not recognise a collection demand, a written evidence request can help clarify the creditor, amount and basis of liability. It does not automatically cancel a debt or stop court proceedings.
In this article, we will help you to:
- Understand why you’ve received a debt collector letter.
- Learn about debt collectors and enforcement agents.
- Find out if a debt collector needs to show proof of debt.
- Discover what a debt validation letter is.
- Learn how to write one and why it’s important.
Check the type of debt and whether a court order already exists before choosing a template. Keep copies and respond separately to any legal deadlines.
Let’s dive in and start to make things clearer.
Have you received a letter?
Collection letters may request payment or warn of possible proceedings. Read the actual document: a reminder, letter of claim and court claim each need a different response.
If you’ve received one of these letters there is a lot you need to know. Read on to armour yourself with the facts and your rights.
What is a debt validation letter?
“Debt validation letter” is a general description, not a single statutory UK procedure. This guide uses it to mean an evidence request to a creditor or collector.
It can either refer to:
- A letter you send in reply to a debt collection agency asking them to validate you owe the debt, or prove you owe the debt. This is why they’re also called prove-the-debt letters.
- The letter the debt collection business sends in reply to your letter, which should validate the debt.
For the rest of this post, we’ll refer to a debt validation letter as the letter you send in reply asking the debt collection agency to prove you owe the debt.
Why send one?
Send an evidence request when you dispute liability or need to understand the amount claimed. A generic request does not automatically suspend every contractual payment obligation.
Ask for an itemised balance, the original creditor, relevant agreement or bills and the basis on which the sender owns or collects the account. A Consumer Credit Act request for a relevant agreement is a separate statutory process.
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Do they work?
The reply may establish an error, confirm liability or leave a dispute unresolved. Failure to reply does not by itself settle or write off the debt.
But that doesn’t mean you should always send one. There might be times when you should take other action…
Should I send it?
You should send a prove the debt letter if you dispute owing some or all of the money.
If you believe the account was already paid, tell the current collector and provide or request the relevant payment evidence. You can also ask the original creditor to confirm settlement; there is no reason to leave the current demand undisputed.
You may not want to send a debt validation letter if you know you owe the money and want to avoid further time and the possibility of more late charges added to the debt.
If an old debt may be time barred, seek advice before making a qualifying acknowledgement or payment. Not every debt uses the same limitation period or is extinguished by age. See related guidance.
A properly framed limitation or prescription response may be appropriate once the position is checked. It does not replace a defence to court proceedings. See related guidance.
Debt validation letter UK template
Use the linked template as a starting point and adapt it to the facts. Do not include assertions that you cannot support, and do not assume a template extends a deadline. See related guidance.
How long does a debt collector have to validate?
There is no universal two-week deadline for every informal proof request. For specified Consumer Credit Act information requests, the statutory period is generally 12 working days after receipt of a valid request and any required fee. Pre-action and court procedures have their own deadlines.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Possible scenarios
What to do after sending a debt validation letter will depend on how the debt collection agency reacts to your letter. We discuss the three most common scenarios below.
- Collection agency did not respond to debt validation letter
Sometimes the debt collection agency won’t respond to your debt validation letter. Just as this forum user experienced:
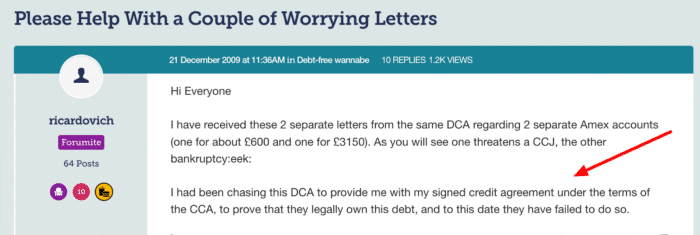
Source: https://forums.moneysavingexpert.com/discussion/comment/28045073#Comment_28045073
Keep your request and any reply, even if collection stops. Silence and absence from a credit report do not prove that the debt has been cancelled; respond promptly if a later claim arrives.
- Collection agency didn’t respond and sent more debt letters
If the collection agency didn’t respond but then continued to make payment requests and legal threats, you should send a complaint reply.
Explain the unresolved dispute and ask the firm to investigate under the applicable rules. Further complaint rights, including the Financial Ombudsman where eligible, depend on the activity and the complaint procedure. See related guidance.
Sometimes the Ombudsman won’t deal with your type of debt, such as a phone debt. In this case, ask a debt charity to who you should escalate the debt – and include this group/organisation in your complaint.
Respond to the court claim by its deadline and set out the relevant defence and evidence. Showing that you sent a proof letter is not, on its own, a defence to every debt.
- Debt collector validated my debt
If a debt collector validates your debt with proof, you should discuss ways to repay with the debt collection agency. If you cannot afford the debt, you should seek immediate advice from a debt charity.
An authorised debt adviser can assess eligibility for Breathing Space in England and Wales. It can pause specified collection and enforcement for qualifying debts, but it has conditions and exclusions and does not write off the balance. See related guidance.





