


What Happens if You Don’t Pay a CCJ after 6 Years?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you wondering what happens if you don’t pay a CCJ after 6 years? You’ve come to the right place for answers. Every month, over 170,000 people visit our website for advice on debt and credit.
In this article, we’ll explain:
- What a CCJ is and how it can affect you.
- What can happen if you don’t pay a CCJ after 6 years.
- How a CCJ can change your credit report.
- What you can do if you have a CCJ.
- How you may be able to write off some debt.
We know it’s not easy dealing with a CCJ, and it’s common to feel unsure about seeking help. In fact, Citizens Advice revealed that 60% of adults facing financial difficulties hesitate to seek assistance.1
If that’s your case, don’t worry — you’re not alone. We’re here to help guide you through the process and help you find a way to clear your debt.
How Do I Know If I Have a CCJ?
What Happens if I Don’t Pay?
Debt Solutions Comparison
Dealing with debt can be challenging. But don’t worry, there are different debt solutions available that can help you ease your worries.
These are:
| Option | How it works | Key limits and risks |
|---|---|---|
| Debt management plan | Informal repayment of eligible non-priority debts through an affordable budget. | Creditors need not agree, freeze interest or stop court action. Fees apply with some providers; free providers exist. |
| IVA | Formal agreement covering eligible debts and accepted through the creditor voting process. | Fees, credit effects, asset/equity terms and failure risks apply. Payments and term depend on the agreed proposal. |
| DRO (England and Wales) | Normally 12 months of protection before qualifying debts are discharged if the order remains in force. | Current qualifying-debt limit £50,000; strict income, asset, vehicle and residence conditions. Homeowners are not eligible. Application is through an approved adviser to the Insolvency Service, not a court. |
| Bankruptcy (England and Wales) | Formal insolvency that can discharge qualifying debts. | Assets and employment may be affected. Discharge is usually after 12 months, but income payments may continue for up to 3 years. |
| Consolidation loan | New borrowing to repay selected existing debts. | Does not write off debt. Fees or a longer term can increase the total paid; secured borrowing puts your home at risk. |
| Agreed payment break or reduced payments | A temporary arrangement negotiated with the creditor. | Interest may continue, credit reporting can be affected, and the debt remains. Terms require agreement. |
| Informal negotiation | Ask creditors for affordable payments or a settlement. | Acceptance is not guaranteed; record terms in writing. Priority bills still need separate attention. |
| Equity release | Eligible homeowners may access property value through a lifetime mortgage or home reversion. | Reduces the estate and may affect benefits or care funding. Requires specialist advice and comparison of alternatives. |
Can You Go to Prison for Not Paying?
What Happens if I Don’t Pay a CCJ After 6 years?
» TAKE ACTION NOW: Fill out the short debt form
What Happens to the Judgment That Were Issued After 6 Years?
Can I Set Aside My CCJ?
In some cases, you can set aside your CCJ.
This will remove it from the Register of Orders Judgements and Fines and your credit file.
If your CCJ is a default judgement, where you couldn’t defend or acknowledge your creditor’s claims, you can apply to have it set aside.
You can also apply for it to be set aside if you couldn’t or didn’t attend the hearing if you had a good reason for your absence. Good reasons for non-attendance could be that your claim form was sent to the wrong address or that you weren’t given a month to pay off your debt.
Misdelivery of letters is quite common!
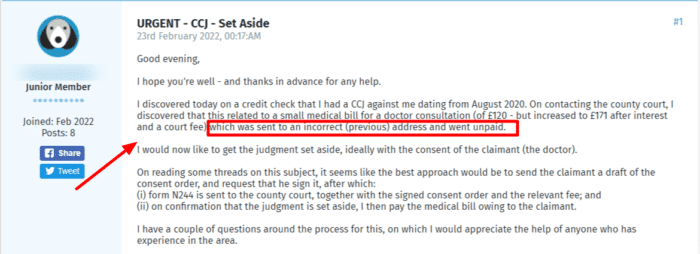
If you can show the court that you can successfully defend your creditor’s claims, you can have the CCJ set aside by issuing an N244 form.
You will also need to provide a draft defence and a witness statement.
If your application to set aside your CCJ is successful, it will be removed from the register immediately.
Will It Affect My Job?
Any CCJs will be visible on your credit report.
Fortunately, it’s not standard practice for employers to do credit checks on any prospective employees.
However, some roles will require a ‘fit and proper’ test. This includes most jobs in the financial services sector, legal professions, and some other career paths.
You will need to have a good credit history to pass this test.
Can I Rent if I Have One?
Unfortunately, you may find it difficult to find a rental property if you have an active CCJ. This is because CCJs are visible on public registers so your applications may be turned down.
Keep in mind that if your CCJ is more than 6 years old, it is not on your credit file so your prospective landlord can’t turn you down on this basis alone.
How do I Get Rid of a CCJ Without Paying?
Can Bailiffs Force Entry?
How Do I Prevent A CCJ?
Don’t want a CCJ? The easiest way to avoid one is to keep up with your debt repayments.
But this isn’t always possible!
If you can’t make your debt repayments, you can negotiate with your creditors to get a new payment plan. If your creditor agrees to a new payment plan, they can’t get a CCJ against you until they apply for legal enforcement measures.
Keep in mind that your creditors are under no obligation to accept your requests. If they don’t, the CCJ is not stopped!
References





