


DVLA Debt Collection: Check the Penalty and Respond


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you puzzled about a letter from a debt collector named Capital Resolve about a DVLA debt? You might be asking, where has this debt come from? Should I pay it? Is it real? Don’t worry; this guide is here to help.
Each month, over 170,000 people come to our website for advice on debt issues, so you’re not alone.
In this article, we’ll cover:
- Where DVLA debts come from and how to check if they’re real.
- The role of debt collection agencies such as Past Due and Capital Resolve.
- How to deal with a DVLA fine.
- Ways to handle too much DVLA debt.
- What happens if you ignore your DVLA debts.
We know that a letter from a debt collector can be worrying; some of us have been in your shoes. Research shows that 64% of UK adults find interactions with current debt collectors stressful1. Luckily, we’re here to help you learn more about how to handle your DVLA debt.
In a Nutshell
DVLA administers vehicle registration and vehicle tax in the UK and driver licensing in Great Britain. Northern Ireland driver licensing is handled by DVA. Check which authority and offence your notice concerns.
Sometimes your debts just slip through the cracks, and nowhere is this more evident than when dealing with your car.
You will often receive a DVLA penalty letter if you haven’t insured your vehicle if you haven’t taxed it, or if you haven’t declared that it is off the road.
Declaring your vehicle as being off the road is also known as a Statutory Off Road Notification, or SORN for short. As soon as you take out a SORN, you will get a refund for any full months of remaining tax, and you won’t be able to use the vehicle on the road until you tax it again.
Paying a fine
Paying a DVLA fine before they start using the DVLA debt recover process starts is straightforward. If you follow this link, you will be able to find out all the necessary steps to settling your fine.
They offer several different ways of paying;
- an in-website option
- a telephone option (0300 790 6808, only available from Monday-Friday, 9am-5pm)
- or by post (if you send a cheque or a postal order with your vehicle registration number written on the back) to DVLA Enforcement Centre, D12 Longview Road, Morriston, Swansea, SA99 1AH.
Sometimes, however, everyone can forget to pay up the debts that they owe. When this happens, the DVLA may use a debt collection agency to recoup the money.
DVLA can instruct an agency to collect an outstanding penalty; that does not mean the agency bought the debt. Its current policy says these collection agencies contact people by letter, text, phone or email and do not visit their home or workplace.
DVLA penalties do not all follow an ordinary consumer-debt timeline. Identify whether the notice concerns late licensing, an out-of-court settlement or an insurance fixed penalty before using general debt guidance.
| Possible stage | What can happen | What to do |
|---|---|---|
| Missed payments | The creditor or collector may contact you, apply contractual charges or issue required notices. There is no single timetable for every debt. | Check the debt and contact the creditor early. Prioritise essential bills and seek free debt advice. |
| Collection activity | Letters, calls or a proposed visit may follow. A collection agent has no power to seize your belongings. | Ask for identification and evidence of the debt. You do not have to let a debt collector into your home. |
| Letter of claim | A creditor may send a formal pre-action letter before making a claim. | Follow the response deadline and get advice; do not ignore it. |
| Court claim | In England and Wales, a creditor may apply for a county court judgment. A judgment and later enforcement are separate stages. | Respond to the claim by the court deadline, whether admitting it, disputing it or asking for time to pay. Attend if the court requires a hearing. |
| Enforcement after judgment | Where legally permitted, a creditor may seek enforcement such as an attachment of earnings, charging order or warrant of control. | Get advice promptly about the specific notice, available objections and affordable payment options. |
» TAKE ACTION NOW: Fill out the short debt form
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What happens when I don’t pay?
When you forget to pay a debt that you owe, the company you owe the money to will often contact a debt collection agency to collect the money.
It is often a cause for stress when you receive a letter from a company you probably haven’t dealt with in the past. More so if they’re asking you to pay a sum of money you may not even realise you owe, but in the initial letter they send they will tell you who they are collecting on behalf of.
When it comes to the DVLA, they have been known to use a host of different debt collection agencies to collect fines and DVLA penalties – everything from SORN to road tax evasion!
DVLA’s current vehicle-enforcement policy names the following agencies:
- Advantis Credit Ltd
- Ardent Credit Services, trading as Debt & Revenue Services (DRS)
- BPO
- CCS Collect
- Capital Resolve Ltd
- Pastdue Credit Solutions Limited and The Zinc Group
An older list, from a 2010 information request linked below, included these names. It is historical and should not be used to authenticate a current demand:
- Inter-Credit International Ltd
- JB Credit Recovery
- Legal & Trade
- Moorcroft Group
- Philips Collection Services Ltd
Use DVLA’s current official policy and contact details to check an agency. A historical listing is not proof that a caller, letter or payment link is genuine.
What to do next
If you’ve received a letter from one of the debt collection agencies listed above, in relation to a debt you might owe to the DVLA, you may be a little worried and suspicious.
One of the first things you should do is to make sure that the company who has sent you the letter is legitimate.
Legitimacy
There are all sorts of stories about debt collection scams out there, so it’s better to be safe than sorry.
Companies House can help identify an entity but does not authenticate correspondence. Check your DVLA penalty reference and contact DVLA using independently obtained GOV.UK details if you are unsure.
A genuine agency can be impersonated. Do not use a company registration or familiar name as the only check before sharing information or paying.
Follow our ‘prove it’ guide with letter templates and get them to prove that you owe the money.
Information
From the moment you receive the first piece of correspondence from the DVLA debt collection agencies, you should start gathering as much information as you can.
Go through all your correspondence from the DVLA and cross-reference the amounts with the letter from the debt collection agency.
Query any error and provide relevant evidence. A minor mistake does not automatically cancel the penalty. Keep copies and follow the notice’s challenge or payment deadline.
If any problems arise further down the line, you will be able to present essential evidence.
Payment
If you are certain the debt is yours, that the figures match up, and that you have the funds to pay in full, you should pay the DVLA debt collection agencies.
Keep a receipt and ask for confirmation that the account is settled. Processing time or another account can mean correspondence does not stop immediately.
If you can’t pay in full, you should get in touch with them as soon as you can. You may be able to arrange some kind of repayment scheme where you pay the debt back in agreed instalments.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
What if you ignore it?
If you ignore your DVLA debts, you will have to deal with the consequences of unpaid DVLA fines which means that the situation is only going to get worse!
An unpaid late licensing penalty can be referred to collection. Separate untaxed-vehicle or registration offences, and uninsured-vehicle fixed penalties, can lead to prosecution. A collector’s letter does not automatically produce a CCJ.
If a civil County Court claim is brought, a CCJ is a possible outcome of that separate process. Criminal proceedings and magistrates’ court fines follow different rules. The following register points concern CCJs only.
Your judgement will include the following:
- How much you owe
- How you should pay
- Who you should pay
- Your deadline to pay.
Unless you pay within one month of the CCJ being issued, it will be recorded in the Register of Judgements, Orders and Fines for 6 years. If you pay off your debt within these 6 years, you can request that your judgement is marked as ‘satisfied’ on the register.
To do this, write to the court with proof that you have paid off the debt in full.
If a CCJ is paid in full within one calendar month, you can apply for its removal from the register. Send the court the required evidence; later payment normally results in a satisfied entry.
A CCJ normally appears on your credit file for six years from the judgment date unless it is removed earlier under the applicable rules. It can make borrowing harder or more expensive, but it does not make all credit impossible.
This is because companies use your credit file to see if you are a ‘high-risk’ customer – someone who might have difficulty paying their bills on time. If you have a CCJ, you have had such trouble paying back your debt that someone had to go to court about it.
Understandably, companies are going to be reluctant to give you credit!
After 6 years, it is no longer visible on your credit report and you should find it easier to get credit again.
Vehicle-tax enforcement can also involve clamping, removal and eventual disposal under separate statutory powers. That is not an ordinary collector seizing a car merely because a demand letter was ignored.
Ignoring your DVLA debts is really not a good idea!
Will It Affect Your Credit Score?
Dealing with DVLA debts can be stressful enough without worrying about your credit file.
A DVLA penalty or collection letter is not itself a CCJ. Any credit effect depends on the action actually taken and the records produced by that process.
From our experience, this is a common concern!
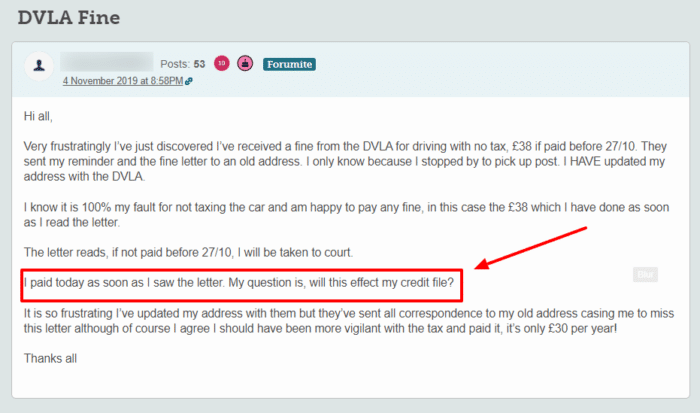
A council parking PCN, a DVLA licensing penalty and a criminal court fine are different. Do not use parking-PCN guidance to decide the court or credit consequences of a DVLA notice.
How Can You Avoid It?
You can avoid DVLA debts with some simple organisational techniques:
- Set automatic reminders for key dates
- Set up automatic payments for your vehicle tax and insurance.
Being a little bit organised is the easiest way to prevent DVLA debts. Accidental vehicle tax evasion is probably quite common – everyone has forgotten that date once!
DVLA Debt Collection Agencies Contact Information
| Address: | DVLA Enforcement Centre D12 Longview Road, Morriston, Swansea, SA991AH |
| Phone: | 0300 790 6808 Monday-Friday, 9 am to 5 pm |
| Website: | https://www.gov.uk/pay-dvla-fine |
References





