


Equity Release Calculator – Work Out How Much


MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
MoneyNerd introduces enquiries to Age Partnership and may receive a referral fee. MoneyNerd does not provide equity release advice. Equity release reduces the value of your estate and can affect means-tested benefits. With a lifetime mortgage, unpaid interest compounds and increases the amount owed. Fees and early repayment charges may apply.
Ask a regulated adviser to explain suitability, costs and alternatives. For free, impartial guidance, visit MoneyHelper.
Are you keen to uncover more about equity release plans and their costs? This is the perfect place for you. In this article, we'll take you through:
- A clear definition of equity release.
- The process for obtaining a realistic quote.
- How to compute equity release costs with a calculator.
- The benefits and possible risks of equity release plans.
- Your eligibility for equity release.
We understand that you might be worried about the potential risk to your home’s equity or the long-term costs of a lifetime mortgage, which is why we’ve gathered all the necessary information to put your mind at ease.
Trust us to guide you through the process of equity release, helping you make informed decisions about your financial future. Let’s dive in.
How does equity release work?
There are two main types of equity release: lifetime mortgages and home reversion plans. Enhanced and drawdown arrangements are variations rather than separate legal categories.
Lifetime mortgage
A lifetime mortgage is a loan secured on your home; you retain ownership. Interest that is not paid is added to the balance. The loan is usually settled when the last borrower dies or moves permanently into care, subject to the contract. Required or optional repayments vary by product.
Many lifetime mortgages allow interest to roll up without regular payments, but some require interest payments for a set period. Optional repayments, limits and any early-repayment charges depend on the contract. See related guidance.
The total owed will be deducted from the future sale of the property and given to the lender, and anything remaining will either be the homeowner’s if they moved into care, or estate beneficiaries if the homeowner had passed away.
For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
Enhanced lifetime mortgage
Some lifetime mortgages take health and lifestyle into account and may offer a larger advance or different pricing. This does not automatically make the product suitable for someone with reduced life expectancy.
Medical underwriting considers expected loan duration and other risk factors. A provider may ask health and lifestyle questions and seek supporting information; the outcome is product-specific.
Home reversion scheme
A home reversion plan is a sale of part or all of your home, usually below open-market value, in return for money and the right to remain under the plan’s occupancy terms. It is not a loan. The provider receives its agreed share when the home is sold. See related guidance.
For example, you may release 10% equity from your home but have to give the lender 50% of the future sale proceeds. Releasing equity this way provides more certainty of what will be owed from the eventual property sale, but it can be more costly for many.
» TAKE ACTION NOW: Find out how much equity you could release
Equity release eligibility criteria
Most standard lifetime mortgages start at age 55, but some payment-term lifetime mortgages are available from 50 and require interest payments for an agreed period. Home-reversion minimum ages and all other eligibility rules depend on the provider. Check the youngest applicant’s age and the actual product criteria. See related guidance, related guidance.
Eligibility depends on the product, age, property, credit circumstances and any required affordability assessment. Minimum property values and borrowing limits are lender-specific. An existing mortgage normally has to be cleared at completion, often using some of the released funds.
Consider the costs and risks of equity release
Equity release is a long-term financial decision. A lifetime mortgage is a loan secured against your home. If interest is added to the loan, the debt can grow substantially and reduce the inheritance you leave.
Consider the fees, effect on means-tested benefits, early repayment charges and future care needs. Alternatives may include downsizing, using other assets or a retirement interest-only mortgage where affordable.
Use the button below to start an enquiry with Age Partnership. An estimate does not confirm eligibility or suitability. Get specialist financial and independent legal advice before proceeding.
In partnership with Age Partnership, which advises on lifetime mortgages. MoneyNerd introduces enquiries and may receive a referral fee. Equity release can reduce your estate and affect means-tested benefits and future care funding. Fees may apply and interest added to a lifetime mortgage increases the amount owed. Specialist financial and independent legal advice are required before proceeding.
How much equity can I release?
The amount available and any later further advance depend on age, property, the product and lender criteria. There is no single universal 60% limit or once-only rule. See related guidance.
Lenders limit borrowing based on their product design, risk assessment and any guarantees; an estimate is not an offer.
But the amount of equity you can release will also depend on the type of scheme you use. For example, an enhanced lifetime mortgage may allow you to release more than a regular lifetime mortgage or home reversion scheme. The amount you can release will also be based on your age, property value and other details about your property.
How much will I pay back with equity release?
The amount you pay back on equity release will depend on the amount of equity you release, the interest rate you agree to, and the length of time your lifetime mortgage lasts. But to give you an idea of how costly a lifetime mortgage can become, here is an example:
Illustration only: a £65,000 lifetime mortgage at 6.4% annual compound interest, with no repayments or added fees, would be about £136,840 after 12 years. A permanent move into care by the last borrower normally triggers repayment; a sale is common but another repayment source may be agreed.
Your property increased in value by 10% over the 12 years and it was sold for £165,000. The total debt owed on your initial £65,000 equity release equates to almost £137,000 due to the rolling interest; it has more than doubled over just 12 years. So, £137,000 of the sale proceeds will be paid to the lender and the remaining £28,000 (minus fees and taxes) will be yours to keep.
For a plan meeting the relevant Equity Release Council standards, the right to remain depends on keeping the property as your main residence and meeting the contract terms. A no-negative-equity guarantee limits repayment to the net sale proceeds when its conditions are met; it does not stop the balance growing or make the product risk-free.
An Age Partnership customer’s experience
Individual experiences vary. Equity release is a long-term decision, and specialist advice is needed to assess whether it is suitable for you. Compare the costs, risks and alternatives before proceeding.
Mrs Wareham
“I am more than pleased to have taken out Equity Release with Age Partnership.”
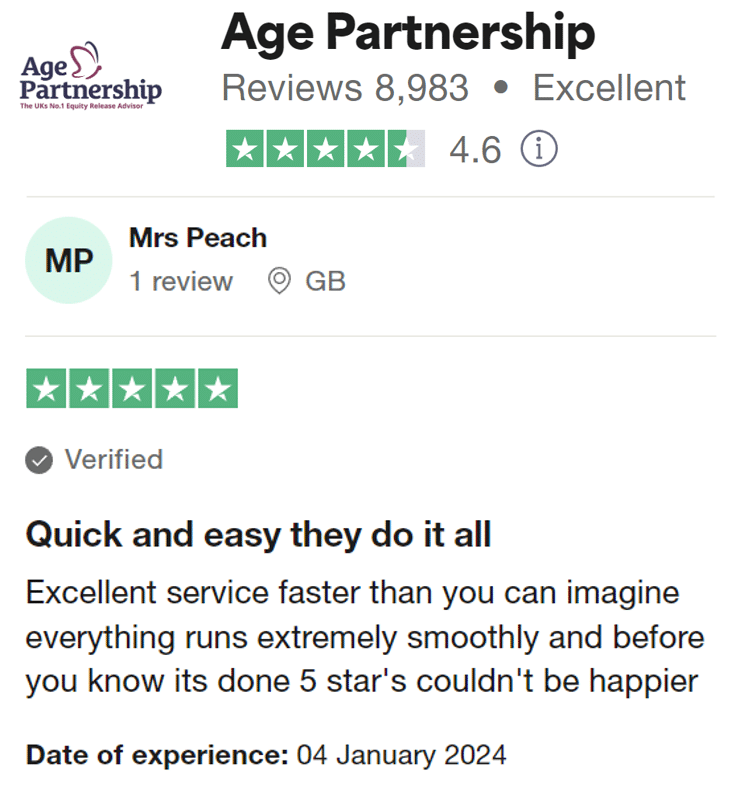
Reviews shown are for Age Partnership. Search powered by Age Partnership.
What interest rate can you get on equity release?
Rates change and depend on the product and your circumstances. Obtain a current personalised illustration and compare the APRC, fees, repayment options and total projected cost; this article does not quote a live market-leading rate.
How do you calculate equity release?
Home reversion is a sale of a share, not an interest-bearing loan. For a lifetime mortgage, projecting future debt requires assumptions about the rate, compounding, fees, repayments and duration.
Nevertheless, an equity release calculator can help…
What is an equity release calculator?
A calculator gives an illustration based on stated assumptions. A borrowing-limit estimate and a compound-interest projection answer different questions. Neither is a lending offer, approval or suitability assessment; actual terms require a valuation, checks and specialist advice.
Where can I find an equity release calculator?
You can find a free equity release calculator on the websites of equity release providers and generic finance websites.
How does it work?
Some calculators estimate a borrowing limit from age and property value; others model future interest costs from figures you enter. Read what the particular calculator estimates and whether it requests contact details.
An interest projection uses the stated assumptions. It cannot establish the actual rate you will be offered or how long the plan will last.
Are equity release calculators accurate?
Calculator accuracy depends on its assumptions and the information entered. It is not inherently more accurate than other loan calculators; confirm actual terms in a personalised illustration.
As part of taking out a lifetime mortgage, there is a high chance that your property will need to be revalued.
What are the advantages of equity release schemes?
Some of the main advantages of using equity release are:
- You can receive a lump sum or drawdown facility
- The money is not subject to tax
- It can be spent on anything you want
- You continue living in your home without paying rent
- It can sometimes be used to reduce inheritance tax
What is the downside to equity release?
The major downside to equity release is the cost of it. Releasing equity with these schemes can be exceptionally expensive if you hold a lifetime mortgage for a decade or longer, like our earlier example highlights.
Another downside to an equity release scheme is that the money you receive could make you lose entitlement to means-tested benefits. You will not lose access to your state pension, but by having significant money in the bank, you could have your pension credits reduced or taken away. This then has an impact on your entitlement to other means-tested benefits, such as a council tax reduction.
Learn more about equity release here!
Uncover more about equity release schemes in the UK with MoneyNerd. Our team has just published 100+ new equity release guides and discussion posts to help all seniors considering this option. Read them for free on our website and get answers to the most asked equity release questions.





