


How Many Times Can a Bailiff Visit? Rules and Your Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
There is no general three-visit limit for bailiffs, and no universal seven-day gap between repeat visits. This guide explains the rules and practical next steps for enforcement against goods in England and Wales.
In this article, we will explain:
- How many times a bailiff can visit your home.
- What a bailiff’s job is and what they can do.
- What to do when a bailiff visits.
- How to check if a bailiff is real.
- Ways to stop bailiffs from visiting your home.
Repeated enforcement contact can be distressing. Explain relevant support needs to the firm and creditor, keep records and seek free debt advice.
Don’t worry! We’ll share our knowledge with you, based on real facts. Let’s dive in to help you get back in control of the situation.
How Long Do They Leave Between Visits?
Your Rights
If you’ve been visited by bailiffs, it’s important to understand your rights. This way, you’ll prevent unfair treatment and stressful situations.
Here’s a quick table that explains what bailiffs can and can’t do. If you’d like to learn more about your rights, be sure to read our detailed guide.
| Bailiffs may | Important limits |
|---|---|
| Visit under a valid enforcement power | Normally at least 14 clear days’ notice is required before taking control of goods; courts can shorten notice. An eligible debt-advice request can extend it to 28 clear days. |
| Take non-exempt goods belonging to the debtor | They cannot take ordinary essential household items or someone else’s property. Some jointly owned goods may be affected. |
| Take a vehicle where legally permitted | Ownership, finance, disability and other exemptions must be checked. ANPR does not remove those limits. |
| Enter through a door when lawful | For ordinary civil debts they usually cannot force first entry to a home. A CCJ by itself is not a power to break in. |
| Enter into a controlled goods agreement | Ask for a clear inventory and terms; breaking an agreement can have serious consequences. |
| Sell goods under the enforcement rules | Notice and sale requirements apply. Get advice if you dispute ownership, exemption, entry or fees. |
England and Wales only. Tools and equipment needed personally for work, study or education have a combined exemption limit of £1,350. The rules differ elsewhere in the UK.
What to Do When They Visit
How to Confirm their ID
Our financial expert, Janine Marsh, advises on letting a bailiff into your home: ‘It’s crucial you check who they say are before you open your door. Ask for their certificate through the letterbox or a window.’
Authenticity verification is something that, in my experience, not enough people know about.
County Court, Civilian Enforcement Officers, and Family Court Bailiffs
High court Enforcement Officers
Certified Enforcement Agents
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
How to Prepare for a Visit
Can They Force Entry to My Home?
» TAKE ACTION NOW: Fill out the short debt form
Can They Take Everything?
No, bailiffs can’t take everything in your house. There are strict rules on what bailiffs are allowed to remove from your property and what are classed as exempted items.
Things bailiffs just can’t take include:
- Goods owned solely by someone else cannot be taken for your debt. Jointly owned goods can be affected, with protection for the other owner’s share; provide evidence and obtain prompt advice if ownership is disputed.
- Goods necessary personally for employment, business, a vocation, study or education are normally exempt up to £1,350 in total, subject to statutory exceptions. The limit covers the combined value of qualifying equipment, not £1,350 for each item. Merely using a car to commute does not automatically qualify it.
- A vehicle displaying a valid Blue Badge because it is used to transport a disabled person, and goods needed to care for a disabled or seriously ill person.
- Any pets or guide dogs.
Bailiffs also can’t take things that are essential for your ‘basic domestic needs.’ This means that, as a minimum, they need to leave you with:
- Beds and bedding for everyone in your home
- A cooker or microwave and fridge
- A landline telephone, or a mobile or internet telephone if there is no landline.
- A washing machine
- A table with enough chairs for everyone in your home
- Medical equipment needed to care for a disabled or seriously ill person, subject to the applicable exemption.
Land and fixtures forming part of the property are not ordinary movable goods available for taking-control-of-goods enforcement. Do not confuse this with a separate possession order or other property-enforcement process.
Any of the debt charities listed at the bottom of this page will be able to give you a comprehensive breakdown of what bailiffs can and can’t take.
Sometimes, you need to be very aware of your rights because they might try to take things that they shouldn’t.
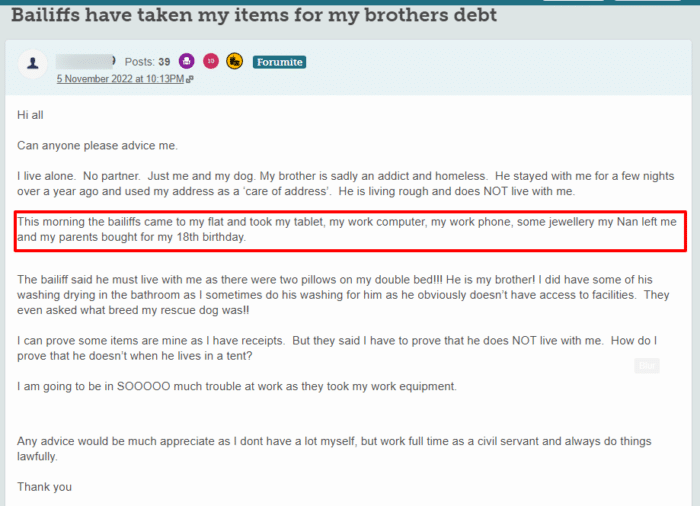
Taking another person’s goods can be unlawful, but an error is not automatically criminal theft. Ownership disputes may need an urgent third-party claim or other court application.
If exempt goods or someone else’s property have been taken, contact the agent immediately with evidence and seek advice on the appropriate court procedure and deadline. An error does not automatically cancel the debt or guarantee that goods will be returned without costs.
Arrange a Payment to Stop Them From Visiting Your Home
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Can I get a Debt Solution?
A suitable formal debt remedy or court order may restrict particular enforcement, but an enquiry, application or informal DMP does not automatically stop every bailiff visit.
There are several different debt solutions available in the UK, so I recommend speaking to a debt charity as soon as possible. Their advisors will be able to look at your finances in detail and help you work out which debt solution will work best for you.
I have linked a few charities that offer these advisory services for free below.
Debt Management Plan (DMP)
A Debt Management Plan can organise affordable payments towards suitable unsecured debts, but is informal and does not automatically stop interest, court action or bailiff enforcement. Priority debts need separate attention.
Because it is informal, it is not legally binding so you are not tied into a DMP for a minimum number of payments.
Individual Voluntary Arrangement (IVA)
An IVA is a formal insolvency arrangement managed by an insolvency practitioner. Your proposal sets out payments, any assets involved and fees. Once approved, it binds the creditors and debts covered by it and restricts recovery action; it is not a blanket ban on necessary correspondence.
Many IVAs involve payments for five or six years, but the agreed term varies. Qualifying unpaid debt is normally released only on successful completion. An IVA affects your credit record, may involve assets or home equity, and can fail if its terms are not met.
IVA suitability depends on your debts, affordable contributions or available assets, fees and creditor approval. There is no universal rule that you must owe several thousand pounds to more than one creditor. Get independent debt advice and compare other options before agreeing to an IVA.
Trust Deed
IVAs are not available in Scotland. A Scottish money adviser can compare a protected trust deed, the Debt Arrangement Scheme, sequestration and informal arrangements; a trust deed is not compulsory.
A protected trust deed is a Scottish insolvency arrangement, usually lasting at least four years of contributions. It can discharge qualifying unpaid debt on successful completion, but fees apply and your home or other assets may be at risk. Covered creditors cannot pursue payment outside it, but can still send required documents.
Debt Relief Order (DRO)
In England and Wales, a DRO may suit an eligible non-homeowner with low surplus income, limited assets and qualifying debts within the £50,000 limit. Detailed income, asset, vehicle and residence rules apply. An approved debt adviser checks eligibility and submits the application to the Insolvency Service.
During the usual 12-month DRO period, recovery of listed qualifying debts is restricted and you generally do not pay those debts. Ongoing bills and excluded debts still need attention. Creditors may send statements and other permitted correspondence.
A DRO normally lasts 12 months. If it remains in force, the qualifying debts listed in it are normally discharged at the end. You must report relevant changes and continue paying ongoing bills and excluded debts, such as court fines and student loans.
Bankruptcy
If you have debts but no realistic possibility of ever paying them off, you may need to declare bankruptcy.
Bankruptcy has an unfair stigma attached to it as it may be your only way of getting a financial fresh start. That said, it is a serious financial situation that should not be taken lightly.
Sequestration
Sequestration is the Scottish version of bankruptcy.
Scotland’s Minimal Asset Process is a form of bankruptcy for people meeting specific debt, income and asset conditions. It has consequences for credit and finances and should be assessed with an approved money adviser. See Minimal Asset Process guide.
» TAKE ACTION NOW: Fill out the short debt form
How do I Complain?
If you think that a bailiff has behaved inappropriately, you can make a complaint.
Make your first complaint to the bailiff’s company so that they have the chance to sort out the issue themselves. But if you think that their response or the way that they dealt with the complaint was insufficient, you can escalate matters.
After the firm has considered your complaint, check whether the Enforcement Conduct Board can investigate: the firm, activity date and complaint must fall within its scheme. Council complaints may instead fall within the relevant local-government ombudsman process after you complain to the council. Court challenges and urgent requests to stop enforcement are separate. See related guidance.
CIVEA means the Civil Enforcement Association. Check the current complaints arrangements for the firm and any applicable independent scheme; membership and eligibility matter. Court complaints about certification are a separate process and can carry costs risks. See CIVEA code of practice.
A free debt adviser can identify the right complaint or urgent court procedure. Keep dealing with legal deadlines while a complaint is considered.
References





