


How to Deal with Debt Collectors in the UK


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
This guide explains how to check a debt demand, challenge a genuine error, request reasonable contact and seek help with unaffordable repayments.
In this article, we’ll show you:
- How to find out if the debt is really yours.
- Ways to stop the debt collector from bothering you too much.
- What you can do if you cannot pay.
- How to talk to the people you owe money to.
- How to possibly get rid of some of your debt.
Keep records and identify the stage of the account. Your response to a collection letter may differ from your response to court papers or a warrant.
Let’s get started and learn more about how to handle debt collectors in the UK.
First, What Is a Debt Collector?
How to respond to a debt demand
1. Learn Everything there is to Know
2. See if Your Debt Is Statute Barred
3. Request for Proof
You can also request a detailed breakdown of the debt as proof that it exists. You may find that some charges or fees have been added that should not have to pay.
4. Make Official Complaints If Necessary
» TAKE ACTION NOW: Fill out the short debt form
How Do I Deal With The Agency?
Do not ignore genuine legal papers. Check ordinary demands and respond appropriately; further action is possible but not inevitable.
Some debt collectors will ask you to pay them immediately. Before you make any payment you need to verify that you do actually owe the debt. Don’t pay until the debt is verified and you are satisfied that you do actually owe it.
If the valid balance is affordable after essentials and priority debts, use a verified payment route. Otherwise, propose a realistic arrangement or seek free advice.
If you opt for a repayment plan, it is essential that you do not miss a payment so only agree to pay what you will realistically be able to.
Keep in mind that most debt collectors will not visit you at home. If they do, you can phone up the company yourself to organise a standing order or other payment. This makes it easier to keep accurate records of your debt payments.
But sometimes you will find yourself dealing with debt collectors looking for debt that is not even yours!
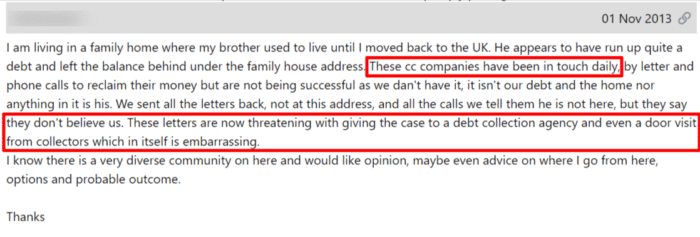
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
It is unreasonable for debt collectors in this example to contact someone daily just because they don’t believe that the person who owes the money is still there.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What outcomes are possible?
How Do I Talk To My Creditor?
Early contact may help agree support, but it does not guarantee that a debt will not be sold or that proceedings will stop.
I recommend talking to them via letter or email because it is much easier to keep detailed records.
If limitation may apply, seek advice before paying or acknowledging liability. A creditor’s letter, a phone conversation or a carefully worded dispute does not automatically restart the period; the legal requirements matter.
Ask about forbearance, affordable repayment or an agreed hold. You do not need to make an unnecessary admission just to ask for advice, and any interest freeze or pause should be confirmed.
If you know that you can afford to repay some of the debt, you can negotiate a repayment scheme. Only agree to pay if you can afford it and make sure you get any repayment plans written in writing before you make a payment. This will make it harder for your creditor to dispute!
Keep in mind that your creditor doesn’t have to agree to any of this – they are allowed to ask for you to pay back all of your debt as you originally agreed. However, it is often in their best interest as they may not get as much money back if you opt for a formal debt solution like an IVA.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Debt solutions and recovery protection
Individual Voluntary Arrangement (IVA)
If you do not have any disposable income, you may wish to consider a Debt Relief Order (DRO).
Debt Relief Order
A DRO may suit an eligible person with low surplus income and limited assets. It has its own conditions and is not simply a cheaper IVA.
In England and Wales, the main DRO limits are £50,000 qualifying debt, £75 monthly surplus income and £2,000 counted assets, with a domestic vehicle worth up to £4,000 generally excluded from the asset limit. Detailed ownership, residence and other conditions apply; an approved adviser checks eligibility.
During a DRO, included qualifying debts are protected from most recovery action under the moratorium rules. This is not a ban on every necessary communication, and excluded debts and ongoing bills still need attention.
A DRO normally lasts 12 months. If it remains in force, included qualifying debts are normally discharged at the end. Report relevant changes and continue paying ongoing bills and excluded debts.
Some debts aren’t part of a DRO – including court fines or child maintenance – so you will need to check with your DRO advisor. You will need to work out a way of paying these debts during your DRO.
Keep in mind that there are different debt solutions that you can use to help beat debt collectors. I always recommend talking to an expert who can help you find the best solution for your financial situation.
Contact any of the following organisations for free debt and financial advice:
What Debts Do I Deal With First?
If you are struggling to manage your debts it can be hard to work out where to start.
The first thing that you should do is identify your priority debts. These are debts that will cause you serious problems if you don’t get them sorted.
Priority debts can include:
- Rent or mortgage arrears
- Council tax arrears
- Energy bill arrears
- Court fines
- TV license payments
- Overpaid tax credits
- Unpaid child maintenance.
Once your priority debts are sorted, you can move on to dealing with any others that you might have.
Non-priority debts are usually unsecured debts and can include:
- Credit card or store card debts
- Private parking charges, which are different from council penalties or criminal fines.
- Unsecured loans – eg payday loans
- Household water bills in England and Wales: domestic supplies cannot be disconnected solely for non-payment, although the debt can still be recovered.
- Debts owed to your family or friends.
The classification depends on the consequences and stage. A court judgment or enforcement notice needs prompt attention even for a debt originally classed as non-priority; ordinary consumer debt is not itself a criminal offence. See related guidance.
A Word on Stopping Harassment





