


O2 Debt: Check the Bill and Get Payment Help


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you worried about an O2 debt? If so, you can rest easy now – this article is just what you need. Every month, more than 170,000 people come to our website for guidance on debt matters, so you’re not alone.
In this guide, we’ll help you with:
- Understanding who O2 is and why you might owe them money.
- Understanding how to deal with your O2 debt.
- Finding out if you can lessen your debt.
- Learning about the O2 debt repayment plan.
- Dealing with old O2 debts.
We know how it feels to be chased for money you owe, as some of us have been in your shoes. We understand your worries and fears, which is why we want to help you.
We’ll help you know more about O2 debts and what to do about them. We’ll also give you tips on how to handle debt issues in general. Let’s start this journey together
Why Might You Get into Debt?
An O2 balance can include airtime charges, device-finance repayments or both. Check which agreement each amount relates to; the legal information-request and complaint rules can differ.
Contract lengths vary. A change in income or circumstances can make an existing commitment unaffordable, so contact O2 before arrears grow.
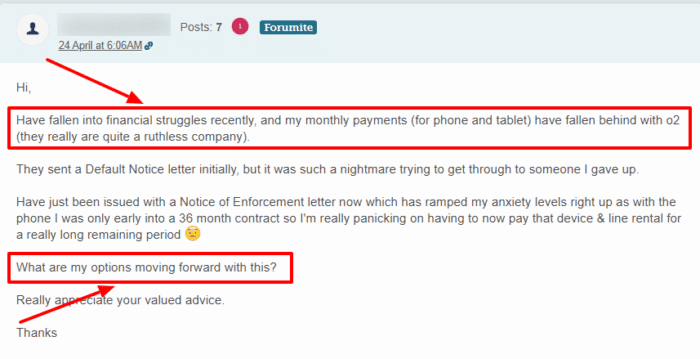
Or they simply miss a payment because they forgot to add money to the account they pay from.
Another common scenario is an individual signing an O2 mobile phone financing on behalf of someone else, such as a partner, who then stops paying for the phone after a breakup.
» TAKE ACTION NOW: Fill out the short debt form
They Provided Proof, What Now?
If you recognise the agreement and the balance is correct and enforceable, discuss affordable repayment. A name on a document alone does not resolve identity fraud, an incorrect charge or every possible dispute.
Seek ways to make the debt affordable so you can clear it without putting too much strain on your financial situation.
Respond to any genuine letter before claim or court papers by the deadline. In England and Wales, ordinary phone debt normally requires a judgment and the relevant enforcement authority before bailiffs can act; an ordinary collector cannot seize goods.
Reported arrears or a default can harm your credit history. Ask how a repayment arrangement will be reported and challenge an inaccurate entry.
You can get free independent debt advice from a charity such as StepChange. MoneyHelper is a public money-guidance service and can direct you to free debt advice.
These organisations offer free impartial advice to those struggling with debt and other financial hardships.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Repayment Plan
If you find yourself in arrears with O2, you can contact their specialist team to discuss a repayment plan.
They will take into account your situation and try to agree on flexible payment options that don’t cause you financial distress and eventually clear the debt over time.
If you agree to a repayment plan and still have an O2 contract active, or a second O2 contract, there is a chance that O2 will block you from accessing further services.
Ask which services or spending limits will be affected by a proposed plan. Do not assume that an arrangement keeps every feature or additional account available.
How Can I Contact their Team?
The O2 Debt Repayment Team are free to call on 0800 902 0217. They are open on weekdays between 8 am and 8 pm.
And on weekends, the helpline is available on Saturday between 8 am and 6 pm, whereas Sunday, their lines are open from 9 am to 6 pm.
You might feel worried about calling the O2 Debt Repayment Team, but these people are trained to offer assistance with your sensitive circumstances and are usually very friendly.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
But, What About Old Debt?
Sometimes, your O2 debt doesn’t get paid, and it catches up with you in a few years.
O2 may use a collection agency for an unresolved balance. Verify any referral and the amount owed.
O2 may instruct an agency to collect on its behalf or assign a debt. Ask who owns it, obtain the account breakdown and verify the payment destination independently.
The agency handling a particular account can change. Confirm any approach with O2 using its official contact details rather than relying on a name in an unexpected message.
First, Request for Proof
A referral does not remove your ability to dispute an incorrect balance or discuss affordability. Contact the current authorised collector and keep records of the response.
Ask for the account details, relevant agreement, itemised balance and evidence that the collector is entitled to seek payment.
A Consumer Credit Act information request may apply to a separate regulated device loan. It does not automatically apply to an airtime service contract, and a compliant copy need not always contain an original signature. Request information to establish the facts, not as a delay tactic.
- Check that the account and relevant dates belong to you.
- Check the charges, payments and any cancellation or settlement already agreed.
- Identify the airtime and device-finance elements and raise specific errors.
Keep a copy of your correspondence and proof of delivery. A request for information does not replace a response to court papers.
Complain first to the business. Ordinary airtime complaints use the provider’s telecoms complaint and ADR process. The Financial Ombudsman may cover a qualifying device-credit complaint, but its debt-collection remit does not automatically cover ordinary mobile service debt.
A debt-information letter can help set out a genuine query. Get advice before assuming that a missing document means no payment can ever be required.
Or, Send a Statute Barred Letter
For an old demand, ask an adviser whether limitation or prescription applies before making a payment or written acknowledgment.
In England and Wales, many simple-contract claims have a six-year limitation period. It is a legal time limit, not a loophole. An adviser will need to check:
- When the creditor first had the relevant right to sue, rather than just the contract’s start date.
- Any payment made during the relevant period.
- Any written acknowledgment and its legal effect.
- Whether proceedings were started or a judgment already exists. Scotland and Northern Ireland have different rules.
A limitation defence is not automatic merely because a bill is six years old. In England and Wales the underlying debt is not generally erased, and a court claim must still be answered in time.
If an adviser confirms the debt is time-barred, explain that position to the collector and keep evidence. A letter does not guarantee all contact will stop or remove the need to respond to court papers.
O2 Contact Details
| Contact us: | https://www.o2.co.uk/contactus |
| Website: | https://www.o2.co.uk/ |





