


Intrum Debt Collection: Letters, Disputes and Repayment Options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Received an unexpected Intrum letter? Verify the sender and account before making a payment.
You may be confused about where this debt has come from and if you should, or indeed have to, pay it. This guide will provide clear and simple advice to help you understand your options and rights, answering common questions, such as ‘Is this a genuine debt?’ and ‘Could I write off some Intrum debt?’
In this article, we’ll cover:
- Who Intrum Debt Collectors are, and why they may be contacting you.
- Your legal rights when dealing with debt collectors.
- How you might be able to write off some of your debt.
- Understanding if the debt is money that you owe.
- Where to get free advice if you’re struggling with unmanageable debt.
You can ask for written information, appropriate support and independent advice if the debt is disputed or unaffordable.
Let’s explore your options together.
Why are Intrum Justitia Debt Collectors trying to reach you?
Intrum may contact you about a purchased account or an account it services for another creditor. Check the named legal entities.
They buy debts from many other companies, so even if you’ve never heard of Intrum debt, they may have purchased your debts, and you could owe them.
The account owner, collector and original lender can be different businesses.
Do not assume the purchase price determines the amount you owe or a settlement the creditor must accept.
Ask for account and assignment information if ownership is unclear.
For regulated-credit debts, firms must treat customers in arrears with appropriate forbearance and consideration.
Explain any error or dispute and ask the verified firm to investigate. Do not assume unfamiliar contact proves either misconduct or liability.
Is this debt money that you owe?
Do you really owe this debt, or does it belong to someone else? This is the initial point you want to establish. Debt verification is essential – you don’t want to pay a debt that you don’t necessarily have to.
Request a balance breakdown, including payments, interest and charges, rather than assuming the amount has increased correctly.
Ask for the creditor’s name, account reference, balance breakdown and evidence that you are liable. For regulated consumer credit debts, a firm must pause recovery while it investigates a dispute on valid or potentially valid grounds. A request for information does not itself cancel the debt or extend a court deadline.
You can use our free letter template to ask for evidence that you are liable for debt.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Intrum Justitia Debt Collectors and the legalities
The Financial Conduct Authority (FCA) introduced guidelines that debt collectors must now adhere to. In summary, Intrum Debt Collectors have a responsibility to:
If you feel intimidated by Intrum Debt Collectors and they are failing to abide by these guidelines, you would have grounds for a complaint.
What Should You Check Before Paying?
Check liability, enforceability and affordability before payment. Get advice first if an old debt may be affected by limitation or prescription.
Protect essential living costs and priority debts. If proposing instalments or a reduced settlement, obtain written acceptance and clear terms before paying.
In many cases, Intrum will offer you a repayment plan first.
If you dispute the debt, explain why and ask for an itemised balance and evidence that you are liable. For recovery covered by FCA consumer-credit rules, a valid or potentially valid dispute must be investigated and recovery paused. A generic proof request does not cancel a debt, override an existing court order or extend a court deadline.
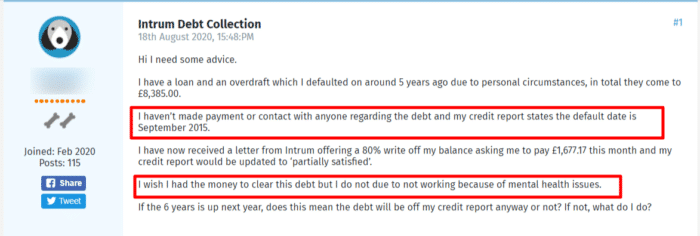
For regulated-credit collection, appropriate forbearance must be considered. There is no universal duty to offer a fixed number of repayment plans, and a formal solution needs a separate suitability assessment.
If you are in a similar position to the person in this case study, we recommend getting some advice from a debt charity.
They will be able to offer you advice and tell you what will be best if you can’t afford Intrum’s suggested payment plans.
We go through the different debt solutions available in the UK below.
» TAKE ACTION NOW: Fill out the short debt form
How Can You make a complaint?
If you think that Intrum Justitia has been unreasonable or behaved inappropriately, you can make a complaint.
You can also make a complaint if you feel that they have broken any of the Financial Conduct Authority’s (FCA) guidelines.
Make your first complaint to Intrum Justitia so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Know Your Rights
In situations of debt, it’s always important to know your rights so you don’t get taken advantage of. There are many things that debt collectors can’t do, and being aware of them can help you have an edge over the situation.
To learn more, please check out our related article on this and take a quick look at the table below.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Intrum Debt Collectors Contact Details
| Customer telephone | 01737 237 370 |
| Hours | Monday to Friday, 8.30am–6pm; Saturday, 9am–1pm |
| Postal contact | Intrum UK Limited PO Box 226 Huddersfield HD8 1FU |
| Online contact | Official customer contact page and portal |
| Complaints email | [email protected] |
References





