Debt Info
Catalogue Debt

JD Williams Debt – All You Need to Know

Scott Nelson MoneyNerd Janine Marsh MoneyNerd
By
Scott
Scott Nelson MoneyNerd

Scott Nelson

Founder of MoneyNerd

Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.

Learn more about Scott
&
Janine
Janine Marsh MoneyNerd

Janine Marsh

Former MoneyNerd Contributor

Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.

Learn more about Janine
· Jun 11th, 2024

Advertisement

Request a call from The Debt Advice Service

Total amount of debt?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
jd williams debt

MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.

This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.

Are you trying to understand whether you should repay your JD Williams catalogue debt and what actions to take if you can’t?

You’re not alone. Our website gets over 170,000 visitors each month, all seeking guidance on debt solutions.

In this easy-to-understand guide, we’ll share:

  •  Who JD Williams is
  •  The steps to take if you can’t pay
  •  What happens when you fall behind on JD Williams payments
  •  If paying the minimum amount each month is a good idea
  •  Different ways to pay off a JD Williams debt

We know that not being able to pay a catalogue debt can be concerning. It can be hard knowing what to do or who to talk to. But don’t worry. We’re here to help you understand your options and choose wisely.

Advertisement

Request a call from The Debt Advice Service

Tell us how much debt you have to continue to the enquiry form. Options depend on your circumstances.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

What happens when I fall behind with payments

First, contact their customer support and explain your situation. Next, seek professional advice from a debt charity if you fall behind with JD Williams payments.

You may also try to set up a paydown plan with the company, which allows you to repay the arrears at an affordable rate. They should be able to set up a fixed repayment plan for you, including the arrears.

When you miss payments or make a payment late, the consequences can be far-reaching. Their customer support will attempt to contact you several times. Don’t ignore their messages.

Plus, you’ll accumulate late fees when you don’t pay on time. This includes:

  • An administration fee of £12 when their customer support tries to contact you.
  • JD Williams could report you to credit reference agencies, making it harder for you to borrow, and get further credit. Of course, this only comes after you’ve ignored several reminders and missed your payments.
  • You may be asked to pay the total amount owed to JD Williams.
  • Your agreement could be terminated.
  • JD Williams may start legal proceedings to recover what you owe.
  • A debt collection agency could get involved to recover the debt which you’ll have to pay for

In short, when you ignore their messages and don’t pay on time or at all, things get harder to settle. The amount you originally owed would have increased substantially, and you could be left facing a debt collector.

Understanding JD Williams late payment fees and how it works can help you avoid paying back more than you should.

You may also end up with a County Court Judgement (CCJ) being issued against you. This allows JD Williams to employ various means (e.g. bailiffs, repossessions, etc) to enforce the debt.

A CCJ stays on your credit report for six years, which may make it difficult to obtain credit in the future.

If you think JD Williams has moved too quickly to issue a CCJ against you, you can complain to the Financial Ombudsman Service via the Online Dispute Resolution platform. This is an online tool for consumers to resolve disputes about their online purchases. It was set up by the European Commission.

Advertisement

How the introduction works

The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.

Options depend on your circumstances. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

How can I pay off my debt?

When you have a JD Williams debt and want to sort things out, I strongly suggest you do so. There are various options available, including:

1. Ask for an informal agreement

The main thing is to stay in contact with JD Williams and let them know about your situation. Their support team may offer you a solution to set up a paydown plan. And, if they do, make sure you can afford to pay the amounts and that you can do so on time!

2. Think about a consolidation loan

I must caution that you apply for a consolidation loan only when you have several debts on top of a JD Williams debt. With a consolidation loan, all the money you owe various creditors is covered in a manageable monthly payment.

Unfortunately, paying off what you owe may take longer when you take this option. In short, your debt increases over time. I suggest you ask for independent advice on dealing with catalogue debt before choosing this option.

3. Consider a balance transfer

Another option is to consider a balance transfer. There are lots of 0% credit card offers being promoted across the online shopping sphere. And they could help get you back on track.

For example, JD Williams charges 39.9% APR. By opting for a balance transfer, you reduce the interest you pay, even if you’ll eventually have to pay the amount you owe on the credit card. That’s one of the major drawbacks of catalogue credit balance transfers.

Also,  the interest rate can rise considerably once the 0% interest offer ends. So strive to pay off the balance whilst this offer is still in place to avoid racking up more debt.

What should I do if I can’t pay?

When you can’t pay a JD Williams debt, I suggest you stay in touch with the company. Don’t ignore any letters or messages you’re sent. Unfortunately, the problem will not go away. In fact, the situation could get worse, and the amount you owe will increase.

Next, contact a debt charity for free, impartial advice. For example, if you owe money to several creditors, consider contacting a debt management company like PayPlan. They offer free advice and could help you sort out the problem.

The main takeaway is to stay on top of the situation because the right debt solution could get you back on track with your finances.

Advertisement

About The Debt Advice Service

Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Continue to the enquiry form

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Can I just pay the minimum monthly amount?
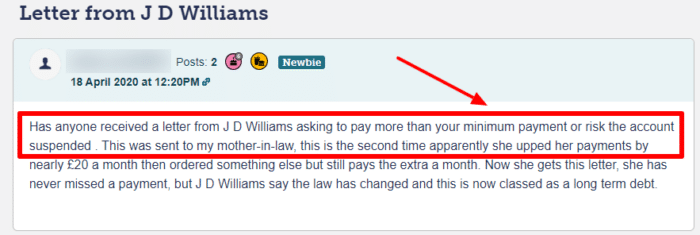
No, not really. It may sound like a good idea, but paying the minimum every month would not cover all the interest added to your account. You then fall into what is known as ‘persistent debt’.

This means that the monthly amount you pay only goes towards reducing the balance outstanding. It does not cover the interest, charges and fees that your debt accumulates.

Persistent debt can hurt your credit score.

JD Williams customer support should let you know about the situation when this happens. The company should offer advice on what you should do to get out of persistent debt. I suggest you pay more than the minimum monthly amount if you can.

Paying more and doing so regularly is the key to avoiding persistent debt with catalogue shopping.

JD Williams persistent debt
Source: MSE Forum.

Remember, if you make only minimum payment (4% of the balance outstanding) every month, you risk falling into persistent debt. JD Williams may suspend your account if you are in persistent debt and you do not enter a paydown plan.

Advertisement

Debt advice: Continue to the debt enquiry form

Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.

JD Williams Contact Details

Phone number: 0345 071 9018 (8am-7pm)
Contact us: Chat us
Email: Email JD Williams
Website: https://www.jdwilliams.co.uk/

Advertisement

Request a call from The Debt Advice Service

Tell us how much debt you have to continue to the enquiry form. Options depend on your circumstances.

How much debt do you have?

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.

Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.

Did you like this article?
Show your support ❤️
We're glad you liked the article! As a small team, your support means everything to us. If you could rate us on Google, it would be amazing. Thank you!
We are so sorry...

Is there something missing? We’re all ears and eager to improve. Send us a message and let us know how we can make our article more useful for you.

You can email us directly at [email protected] to share your feedback.

The authors
Scott Nelson MoneyNerd
Author
Scott founded MoneyNerd after his own experience with debt. He runs the website and oversees its general information about debt and other money matters. Scott does not provide personal debt advice or recommend debt solutions through MoneyNerd. If you make a debt enquiry, MoneyNerd may introduce you to The Debt Advice Service, which provides any personal debt advice.
Janine Marsh MoneyNerd
Debt Expert
Janine previously contributed articles and videos to MoneyNerd about everyday money, household costs, debt topics and parking matters. She has a background in broadcasting, including work with BBC Radio 5 Live and Bauer radio stations. Her published work provides general information, not personal debt advice.


