


Leaving the UK With Debt: Repayments and Legal Risks


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Moving abroad does not automatically cancel UK debts. Before leaving, check how to maintain affordable payments, receive notices and manage any existing court order or debt solution.
In this article, we’ll cover:
- What happens to your debts if you leave the UK.
- The role of foreign debt collection agencies.
- How bankruptcy can affect you.
- Ways you might be able to write off some of your debt.
- What to do if you decide to return to the UK.
Cross-border debt issues depend on the UK jurisdiction, destination country and type of debt. Get advice on your circumstances before relying on an assumption about foreign enforcement.
Stay with us to learn more about dealing with debt if you’re planning to leave the UK.
Can you leave the UK with debt?
The best way you can deal with any debts you still owe while you are abroad will depend entirely on your situation – just as it would if you were in the UK.
It may be possible to continue an existing repayment arrangement from abroad. Confirm this with the creditor or provider and explain any change in income or affordability.
Ask for the agreed amount, currency, due date and payment reference in writing.
The payment methods available depend on the account and provider; an international bank transfer is not the only possible method.
Check exchange rates, transfer fees and which account details to use. An IBAN may be needed for some transfers, but requirements vary.
Banking access and sanctions can restrict particular transfers. Ask your bank and creditor about a lawful available method; do not assume all international payments are prohibited.
Keep evidence of payments and a reliable way to receive correspondence.
Debts abroad
Ordinary unpaid consumer debt does not generally prevent you from travelling or moving abroad. Court orders, insolvency obligations and other legal restrictions need separate advice.
Credit-file retention depends on the entry. A default normally remains for six years from its original date, and a CCJ normally for six years from judgment; this does not mean every debt disappears six years after moving.
A UK credit report does not automatically become a credit report in another country. A lender may nevertheless ask about overseas commitments or use information it lawfully obtains; answer applications accurately.
Banking, credit and rental checks depend on the destination and provider. UK arrears do not make every foreign application impossible.
Benefit entitlement and employment rights follow their own rules. Having UK debts does not by itself remove every entitlement abroad.
Keep accurate contact and financial records so that you can respond to notices and manage your obligations.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
Foreign debt collection agencies
Leaving the UK does not itself extinguish an unpaid balance.
A creditor may use a collector with overseas partners or seek court recovery where jurisdiction and procedure allow.
An overseas collector does not automatically gain power to seize assets or freeze accounts. Such action requires the appropriate legal process and authority under the relevant country’s law.
Recognition and enforcement of a UK judgment abroad depend on the destination, applicable treaties or laws, and the circumstances of the judgment.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Bankruptcy
A creditor may be able to seek bankruptcy where the legal debt threshold, jurisdiction and other conditions are met. Moving abroad does not automatically remove UK insolvency jurisdiction.
Do not assume a new UK bankruptcy is automatically recognised throughout Europe. Recognition rules changed after Brexit and vary by country.
Some jurisdictions provide a process to recognise foreign insolvency proceedings, but conditions and consequences differ.
Foreign assets may be affected where the relevant law allows. Obtain cross-border insolvency advice before assuming they are protected or automatically recoverable.
Whether a creditor pursues overseas recovery depends on the account and commercial and legal factors; no outcome is guaranteed.
County Court Judgment
For many unsecured debts in England and Wales, the usual limitation period is six years from the relevant cause of action, not simply the last phone call. A payment, qualifying written acknowledgement or court proceedings can affect the position. Scotland usually has a five-year prescription period for many ordinary debts, with different rules and exceptions. Court judgments, secured debts and some tax debts require separate advice. Get free debt advice before paying or acknowledging an old debt; do not ignore court papers.
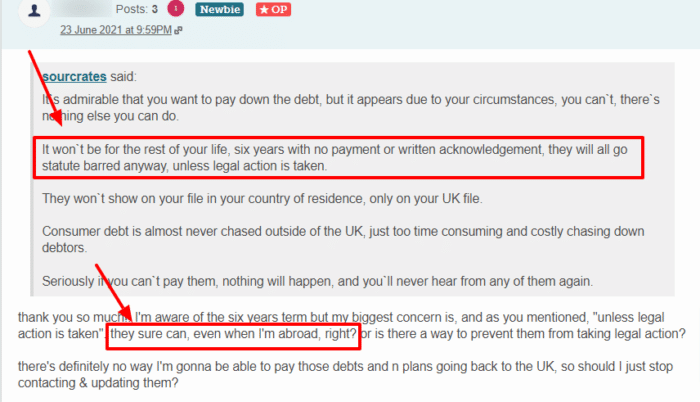
A creditor may be able to bring a UK claim against someone abroad if the jurisdiction and service requirements are met. This is not an unrestricted right in every case.
An unpaid CCJ does not automatically expire after six years. The available enforcement method and any need for permission must be checked.
Service at a last known address can be valid in some cases. Under the England and Wales rules, a claimant with reason to believe you no longer live there must take reasonable steps to establish a current address and follow the applicable service procedure.
Giving a foreign address does not mean proceedings can only begin in that country. UK jurisdiction and service outside the jurisdiction may still be available. Seek advice promptly on any claim.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
Coming back to the UK
Leaving the UK with debt will put you in a tricky position, especially if you are planning on returning at some point.
Keep creditors and any debt-solution supervisor informed of suitable contact details. A missed notice can lead to deadlines passing without your response.
Interest and lawful charges may continue, but not in every case. Ask how your arrangement and applicable forbearance duties affect the balance.
A claim started in time can prevent reliance on a later-expiring limitation period, and a judgment has separate enforcement rules. Respond promptly to genuine court papers.





