


MIL Collections: Checking a Debt, Payments and Complaints


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Have you received a letter from MIL Collections Debt Collectors and are unsure what to do? This is the right guide to help you navigate through the situation.
This guide explains how to check a MIL Collections demand, respond to a dispute and consider affordable repayment options.
In this article, we will explore:
- Who MIL Collections Debt Collectors are and who they work for.
- Why they are reaching out to you.
- If they can take your home.
- Whether you can write off some of your debt with MIL Collections.
- The options available if you can’t afford to pay your debt today.
If collection contact is worrying you, keep the correspondence and seek free debt advice before agreeing to an unaffordable payment.
Let’s look into how you can handle this situation with MIL Collections Debt Collectors.
Why Are Mil Collections Debt Collectors Chasing You?
» TAKE ACTION NOW: Fill out the short debt form
Get the Debt Collectors to Prove the Debt
An initial collection letter is not necessarily a formal Letter of Claim. Identify the document and follow any genuine pre-action or court deadline; MIL cannot itself issue a CCJ.
A creditor may bring a court claim. Taking control of goods needs a further lawful warrant or writ, and a forced sale of a home involves a separate process; neither follows automatically from an ordinary demand.
Check the stage of the matter and any deadline. Seek advice promptly if court papers or a genuine enforcement notice arrive.
A claim form starts court proceedings; it is not already a judgment. Follow the response route and deadline on the papers. Under the usual England-and-Wales procedure, a defence is due 14 days after service of the particulars, or 28 days if a timely acknowledgement of service is filed; exceptions and digital procedures can apply. See related guidance, related guidance.
The evidence depends on the account. A debt may arise without an original signed document, including under some utility arrangements; a qualifying Consumer Credit Act copy request has separate requirements.
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
Do not assume that the business has lost its evidence. Explain a genuine dispute accurately and keep copies of documents, payments and correspondence.
How to Write a Prove the Debt Letter?
You can adapt a prove-it template to your actual circumstances. It does not automatically cancel the balance, establish a defence or stop a legal deadline.
Prove the debt letter templates are widely available online.
But if you want to write your own letter, you should remember to include:
Keep a copy and evidence of sending. Continued contact is not automatically harassment; record unreasonable conduct and complain through the appropriate route.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Should You Pay or Ignore Them?
Collectors must handle information lawfully and avoid inappropriate disclosure to family, colleagues or neighbours. They may communicate with an authorised adviser or representative, and other lawful disclosures can be permitted. FCA consumer-credit rules restrict workplace visits without prior agreement and unreasonable pressure.
Can Mil Collections Take Your Home?
Mil Collections cannot:
An ordinary debt collector has no power to force entry or take goods. It may request a voluntary visit or payment, but you can refuse entry and ask it to leave. Bailiff enforcement requires separate lawful authority. Taking control of goods requires a lawfully authorised enforcement agent and the relevant warrant or writ, not merely a collection letter or ordinary visit. See related guidance.
A creditor can consider legal action even if you have engaged with the firm, so get any agreement to pause action confirmed and respond to court papers.
What if you can’t afford to pay?
Threats of CCJs can send you into panic mode if you cannot afford to pay the debt that Mil Collections are asking for. If they have proved the debt to you, there are solutions even if you are unemployed or a low earner.
#1: Agree on a Payment Plan
You may be able to agree an affordable payment plan. Calculate what remains after essential costs and priority debts before making an offer; acceptance is not guaranteed.
Never commit to an unreasonable and unaffordable payment plan because it can make the debt worse! Take a look at this example.
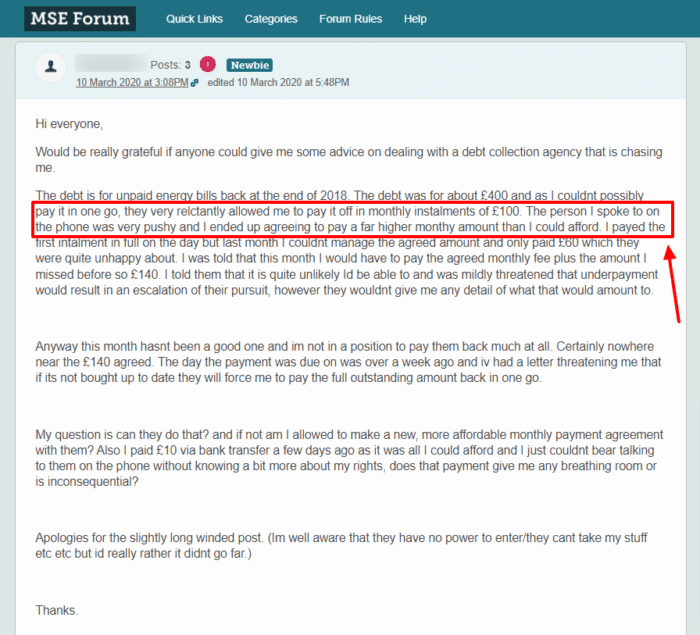
If you are in a similar situation and feel pressured when speaking to debt collectors or creditors on the phone, you should know that you can request written communication only.
Written communication can help you consider proposals and retain records. It does not create a formal Breathing Space moratorium or automatically suspend a deadline.
We have a number of free letter templates that you can use to guide you through the writing process.
#2: Consider a Debt Solution
If you can’t afford to pay for any of the payment plans that MIL Collections have suggested, you may need to consider a debt solution. We will go through your various options below.
There are several different debt solutions available in the UK, so we recommend speaking to a debt charity as soon as possible. Their advisors will be able to look at your finances in detail and help you work out which debt solution will work best for you.
Debt solutions can affect credit records, assets and other circumstances. Independent advice helps compare eligibility, costs, risks and alternatives.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
How Can You Make a Complaint?
Complain to MIL about inappropriate conduct. FCA rules and Ombudsman eligibility depend on the activity, so not every type of collection dispute follows the same regulatory route. See related guidance.
Make your first complaint to MIL Collections so that they have the chance to sort out the issue themselves.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
Know Your Rights
The best way to protect yourself against debt collectors is to know your rights and theirs. Debt collectors are entitled to do certain things, but there are others they can’t do. Please check out our related article on this and take a look at the summarized table below.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
MIL Collections Debt Collectors
References





