


Transcom Student Loan & eBay Debt – Should You Pay?


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Are you puzzled about a letter you’ve got from Transcom about student loans or eBay debt? Wondering if you should pay it?
Check the sender, original creditor, account type and deadline before making a payment or sharing personal information.
In this article, we will explain:
- Who Transcom Worldwide are.
- What to do if they claim you owe money.
- Understanding what a Statute-Barred Debt is.
- Ways to possibly write off some Transcom debt.
- What happens if you genuinely can’t afford to repay the debt.
Student finance, marketplace fees and ordinary consumer borrowing can have different rules. Identify the account before applying general debt advice.
We’ve been there, we understand, and are here to help you through this. Let’s get started on finding the best solution for you.
They Claim I Owe Money. What Should I Do?
The first thing you should do is to check that you actually owe Transcom the money that they are claiming that you owe. Transcom debt verification is important – you don’t want to pay for a debt that you don’t have to!
There are a number of reasons that you might not owe the money.
For many simple-contract debts in England and Wales, the limitation period is six years from the relevant cause of action, subject to payment, written acknowledgement and court-proceeding rules. Many Scottish obligations prescribe after five years under different rules. Debt type and history matter; age alone does not establish that recovery is barred.
Second, the debt could be owed by someone else. If that’s the case, Transcom should be chasing that person for repayment rather than you.
Third, you may have already repaid the debt. If you’ve paid back part of the money, the money that Transcom is claiming that you owe could be the wrong amount.
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
Send information only through a verified contact route and keep copies. A proof request does not need an invented allegation that the collector will forge your signature; follow any genuine identification requirement safely. See related guidance.
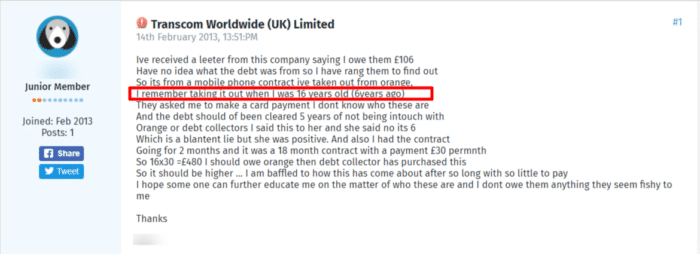
Unfortunately, just being unsure about the debt isn’t enough to not pay it, especially if you are provided proof or get your facts wrong! Take a look at this example.
If you get a letter from any debt collection company and aren’t sure if your debt is enforceable, we recommend speaking to a debt charity. They will look at your situation in detail and they can help correct any misunderstandings you may have!
Do not apply a simple five- or six-year rule to every student-loan balance. Income-contingent student loans, older mortgage-style loans and benefit or student-finance overpayments can have different repayment, cancellation and limitation rules.
» TAKE ACTION NOW: Fill out the short debt form
I Cannot Afford to Repay It. What Are My Options?
If you cannot afford the requested payment, prepare a budget covering essential expenses and priority debts and seek free advice.
Ask the creditor or authorised collector to consider an affordable plan. A proposed amount is not binding until accepted or ordered through the applicable procedure.
You may need to supply details of your monthly income and expenditure to show how much you can afford to repay each month. Once you have agreed to a monthly figure, you will pay that amount each month until the debt has been cleared or there is another repayment plan negotiation.
Make sure that you get confirmation of any repayment agreement in writing so there are no misunderstandings at a later date.
For suitable ordinary unsecured debts, a DMP may be an option. Statutory student-loan repayments generally require their own process and are not simply included like a credit-card balance.
A DMP provider may negotiate voluntary payments and distribute a single monthly contribution. Acceptance and an interest freeze are not guaranteed; free providers are available. See related guidance.
If you are considering a Debt Management Plan, it is important to check the terms and conditions. Some debt management companies charge a fee for providing the service.
What Can They Do if I Do Not Pay?
Contact may continue about an unresolved account, but it must be reasonable and lawful. Explain any dispute, vulnerability or contact preference and keep a record.
If they visit you, they are not allowed to enter your home unless you invite them in. In fact, you aren’t even obliged to answer the door.
An ordinary debt collector has no power to force entry or take goods. It may request a voluntary visit or payment, but you can refuse entry and ask it to leave. Bailiff enforcement requires separate lawful authority.
Do not feel pressured to make an immediate doorstep payment or agreement. Verify identity and liability, and ask for any proposal in writing so you can assess affordability.
If a visit or demand is inappropriate, record what happened and complain. You may refuse entry and request another reasonable contact method. See related guidance.
Although you’ll have to deal with the debt at some point, you’re well within your rights to tell them that you’re not prepared to talk to them.
Your Rights With Debt Collectors
We’ve prepared this table to help you better understand your rights when dealing with debt collectors. If you want to learn more about what they can and can’t do, please read our complete guide.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
An ordinary collector cannot seize property. An authorised enforcement agent needs a separate legal basis and must follow the rules for the debt and jurisdiction. See related guidance.
Transcom is allowed to contact you, but they are not allowed to harass you or threaten you.
If you feel that you have been the victim of these behaviours or unfair debt collection agency tactics, you can make a complaint.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
How Do I Make A Complaint?
Complain to Transcom about specific inappropriate conduct. The applicable regulator and escalation route depend on the underlying service; a student-loan or marketplace-fee complaint does not automatically fall within FCA consumer-credit rules. See related guidance.
Make your first complaint to Transcom so that they have the chance to sort out the issue themselves. If you feel that they have not taken your complaint seriously enough or have not addressed your issue properly, you can escalate matters.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Transcom WorldWide Contact Details
| Company Name: | Transcom Worldwide (UK) Limited |
| Website: | https://www.transcom.com/global/ |
| Address: | Limewood House, Limewood Way, Seacroft, Leeds, LS14 1AB |
| Contact route | Verify current details through Transcom’s official website or the original creditor, using your account reference. |
References





