


ZZPS parking debt collection: checking charges and appeals


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
If ZZPS contacts you about a parking charge, check the original issuer, alleged breach, balance and available response route before paying.
This guide explains how to check the account, challenge a disputed amount and identify the correct payment or appeal route.
In this article, we’ll guide you on:
- Who ZZPS are and why they are contacting you.
- Checking if the debt they claim is truly yours.
- The steps to take if you can’t afford to pay.
- The effects of ZZPS debt collection on your credit score.
- Ways to deal with ZZPS, including how to set up payment plans or even write off your debt.
If contact is threatening or misleading, keep evidence and use the appropriate complaint route. An individual complaint must be assessed on its own facts.
But don’t worry; you’re not alone. Let’s work through this together and help you understand your options.
Why are they contacting you?
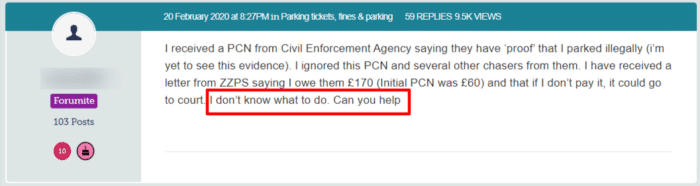
If you are feeling confused like this person, we recommend contacting a reputable source for advice. We recommend contacting a debt charity if needed – they will be able to offer you free and specific advice for dealing with ZZPS.
Typical Debt Collection Process
A ZZPS letter may arrive at different stages; it is not necessarily the first step. Check the history and any current deadline.
Here’s a simple table to help you better understand the debt collection timeline. For more information on how debt collectors may contact you, don’t forget to read our detailed guide.
| Possible stage | What can happen | What to do |
|---|---|---|
| Missed payments | The creditor or collector may contact you, apply contractual charges or issue required notices. There is no single timetable for every debt. | Check the debt and contact the creditor early. Prioritise essential bills and seek free debt advice. |
| Collection activity | Letters, calls or a proposed visit may follow. A collection agent has no power to seize your belongings. | Ask for identification and evidence of the debt. You do not have to let a debt collector into your home. |
| Letter of claim | A creditor may send a formal pre-action letter before making a claim. | Follow the response deadline and get advice; do not ignore it. |
| Court claim | In England and Wales, a creditor may apply for a county court judgment. A judgment and later enforcement are separate stages. | Respond to the claim by the court deadline, whether admitting it, disputing it or asking for time to pay. Attend if the court requires a hearing. |
| Enforcement after judgment | Where legally permitted, a creditor may seek enforcement such as an attachment of earnings, charging order or warrant of control. | Get advice promptly about the specific notice, available objections and affordable payment options. |
How should You deal with ZZPS debt collection?
Follow our ‘prove it’ guide with letter templates and get them to prove that you owe the money.
Check the charge before paying
» TAKE ACTION NOW: Fill out the short debt form
Appeal to the parking company
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
Is ZZPS debt collection the same as bailiffs?
Main Differences Between Debt Collectors and Bailiffs
Here’s a simple table that will help you better understand the main differences between debt collectors and bailiffs. If you want to learn more about your rights when dealing with debt collectors, make sure to check out our specialized guide.
| Issue | Debt collector | Bailiff or enforcement agent |
|---|---|---|
| Role | Requests payment for a creditor or debt purchaser. | Acts under a legally valid enforcement power and must follow its limits. |
| Entry | No power to force entry; you can refuse entry and ask them to leave. | Usually cannot force first entry to a home for council tax or an ordinary civil debt. Limited exceptions and re-entry rules apply. |
| Goods | Cannot seize your goods. | May take non-exempt goods belonging to the debtor where the legal conditions are met; essential items and some work equipment are protected. |
| Bank accounts | A judgment alone gives no access. | Taking money from an account normally requires a separate third-party debt order obtained by the creditor, not a doorstep bailiff power. |
| Contact | Must avoid harassment; regulated firms must contact at reasonable times. | Visits are normally between 6 am and 9 pm, subject to legal exceptions. |
| Vulnerability | Tell the firm what support or communication adjustments you need. | Tell the agent and creditor about vulnerability and seek advice about additional safeguards. |
| Disputes | Ask for evidence of the debt and complain about improper conduct. | Check identification, the enforcement authority and fees; get urgent advice about an invalid notice or proposed entry. |
Can they increase your debt?
If proceedings are issued, the court decides the disputed sum and any recoverable costs. Do not assume either that every added fee must be paid or that all additions can simply be ignored.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Can You Complain About ZZPS Debt Collectors?
Ordinary collectors cannot force entry or seize goods. They must not harass you, misrepresent their powers or improperly disclose your debt to other people.
If they violate these rules, you can complain.
If you think that ZZPS has behaved unreasonably and you want to make a complaint, you can have a look at their complaints procedure.
It is essential that you let ZZPS know about your problem before you go any further – they need to opportunity to sort it out themselves!
ZZPS’s published complaints policy directs unresolved complaints about its own service to the British Parking Association. Check the current policy and the role of the original operator; a conduct complaint is separate from a parking appeal. See related guidance, related guidance.
The receiving body’s rules determine what it can investigate or remedy. Referral does not guarantee cancellation or pause court deadlines.
ZZPS Contact Information
Contact the retailer
References





