


Civil National Business Centre Claim Form: How to Respond


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
A County Court money claim is a civil claim, not a criminal accusation. If you receive one, check the response deadline immediately. The Civil National Business Centre (CNBC) replaced the County Court Business Centre (CCBC) in 2023. This guide concerns claims in England and Wales.
In this article, we’ll cover:
- What a County Court money claim means.
- How to verify it and identify the response deadline.
- How to admit, partly admit or defend the claim.
- What an acknowledgement of service does.
- Where to get help before a default judgment is entered.
Follow the instructions for the particular claim, including its online service or response pack. General information cannot decide whether a claim is valid or what defence you should file.
Why have I received a form?
A claim form means a person or organisation, called the claimant, has started court proceedings against you. It does not mean the court has decided you owe the amount claimed.
The CNBC processes County Court work; it is not a debt collector or the claimant. Claims may concern loans, invoices or private parking charges. A private parking charge is different from a criminal court fine.
If unsure whether the claim is genuine, contact the court using the official court finder rather than relying only on details in the letter. Keep track of the response deadline while checking it.
I received a claim form. What should I do?
Never ignore a claim form. Always respond within the time limit to prevent matters from escalating.
Get advice promptly if the debt, amount or service of the claim is disputed. A request for evidence or a “prove it” letter does not pause the court deadline or replace a formal response.
Debt advice: Continue to the debt enquiry form
Advertisement. MoneyNerd is a commercial introducer, not a debt adviser. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. If you request an introduction, your details are shared with them so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you proceed with a debt solution through The Debt Advice Service. MoneyHelper offers free, impartial money guidance and help finding free debt advice.
What to do when you receive one
Respond to the claim form. Do NOT ignore it. You want to avoid the legal consequences of ignoring a claim form.
If you do not respond in time, the claimant may request a default judgment where the rules allow it. Further enforcement requires the appropriate legal steps; the CNBC does not pursue the debt for itself.
Plus, you could receive a CCJ, which stays on your credit record for up to six years. In short, a CCJ will impact your credit rating.
How the introduction works
The Debt Advice Service can discuss your circumstances and explain available options, including their benefits, costs and risks.
Options depend on your circumstances. You decide whether to proceed.
Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
What steps should I take?
Read the claim and particulars carefully, and keep the envelope or email as well as the documents. Check:
- The court, claim number, claimant and amount claimed.
- What facts and agreement the claimant relies on, and whether payments or charges are disputed.
- The date the claim and particulars are treated as served, and the response method and deadline.
- Whether you need to request missing documents or obtain advice about service, limitation or another defence.
- Whether the response pack or online access details are missing. Ask the court for assistance; a missing pack does not automatically cancel the claim.
How do I respond?
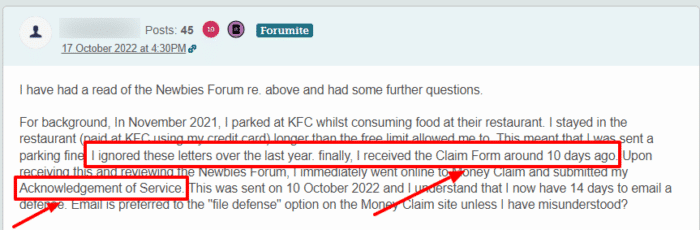
Use the response method stated in your claim. It may be an online process or a paper response pack. An acknowledgement of service is a separate step from admitting the debt or filing a defence.
Under the usual Part 7 rules, a defence is due 14 days after service of the particulars of claim, or 28 days after service if a valid acknowledgement of service is filed in time. Service rules can make this different from the date you opened the letter. Follow the specific deadline in your claim and confirm uncertainty with the court or an adviser.
Again, a reputable debt charity can help you with filing an Acknowledgment of Service and other legal documents to the court.
Do not wait for the claimant to answer an evidence request before dealing with the response deadline. Keep proof that your acknowledgement or response was submitted.
I owe the money. How do I pay?
To admit the whole claim, use the admission procedure specified in the response pack or online service. An acknowledgement of service is not an admission. If you cannot pay in full, give an accurate budget and make an affordable instalment offer through the correct procedure.
Follow the payment instructions in the claim or agreed settlement. Money is normally paid to the claimant or its authorised representative. Verify the recipient and keep evidence of payment; confirm how the court will be notified.
You have two options to pay back the debt to the claimant:
- Settle the debt in a lump sum payment.
- Ask for a repayment plan that allows you to pay it back in affordable instalments.
What if I want to challenge the debt?
If you dispute all or part of the claim, follow the defence or part-admission procedure. An acknowledgement stating an intention to defend buys the permitted extra time but is not itself your defence.
File a defence explaining the disputed issues by the applicable deadline. The case can then continue through court directions, mediation or a hearing. Filing a defence does not automatically defeat the claim or prevent further procedural steps.
If you think an old debt is statute-barred, obtain advice before admitting or paying it. A six-year-old debt is not automatically unenforceable: the cause of action, payments, written acknowledgements, type of debt and previous judgments matter. Raise any applicable limitation defence through the court process.
About The Debt Advice Service
Use the enquiry form to request a call about your circumstances and available options. You decide whether to proceed.

Advertisement. MoneyNerd introduces enquiries; we do not give debt advice or recommend solutions. The Debt Advice Service, a trading style of Pacific Financial Solutions Limited, offers free debt advice with no obligation. Complete the enquiry form to share your details and request a call.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service. For free, impartial guidance and help finding free debt advice, visit MoneyHelper.
What happens when I ignore it?
Ignoring a claim can lead to a default CCJ. Bailiffs do not arrive simply because a claim form was issued; enforcement generally requires a judgment or other authority and further steps.
An unpaid judgment can lead to additional costs and make obtaining credit harder. Responding on time allows your position to be considered before judgment.
You could also have to deal with the following:
- An attachment of earnings order where the eligibility conditions are met.
- A charging order or third-party debt order.
- A warrant or writ authorising enforcement agents.
- A separate bankruptcy petition where the statutory requirements are met.
Court fees, interest and permitted enforcement costs can increase the amount owed. Recoverable legal costs depend on the procedure and court orders; not every solicitor’s bill is automatically payable by you.
So the risk of ignoring a debt claim can be costly in the long run.
I received a CCJ – What happens next?
Read the judgment for the amount, payment deadline and instalments, if any. If you cannot comply, obtain advice promptly about a payment variation. If you dispute the judgment, ask about the applicable set-aside or appeal procedure; a new “prove it” letter is not enough.
A CCJ paid in full within one calendar month of the judgment date can be removed from the register. Payment later normally allows it to be marked satisfied, but the entry remains for six years from judgment. This is not a 30-day period starting when you receive the order.
What advice and help is there?
Free debt advice can help with budgeting and your options. If you need a legal defence or urgent procedural advice, explain that you have an active court claim and give the deadline. Organisations that may help include:
Asking for advice does not extend a court deadline. If you need extra time or clarification, use the relevant court procedure promptly and keep records of what you submit.
How to contact the court
| Current court contact details | Use the official Find a Court or Tribunal service and search for the Civil National Business Centre or the court named on your claim. |
|---|---|
| Responding to the claim | Follow the online service or postal instructions on the actual claim. Different services and teams handle different types of case. |
| Information to have ready | Your claim number, full name, claimant’s name and the documents or deadline you are asking about. |





