


Handling Debt Collector Harassment: Know Your Rights


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Debt collectors can contact you about a valid account, but must not use harassment, misleading threats or inappropriate pressure.
This guide explains how to recognise unreasonable conduct, keep evidence and use the appropriate complaint route.
In this guide, we will share:
- What is classed as harassment from debt collectors.
- How to stop nuisance calls when wrongly blamed for owing money.
- How to get help with debt.
- What to do if debt collectors come to your home.
- How to legally write off debt.
The correct response depends on the conduct and stage of the account. A complaint does not by itself cancel the debt or pause court deadlines.
Read on to learn more about how to handle debt collector harassment.
What Is Debt Collector Harassment?
Understanding your rights against debt collection is important so you know how to deal with a situation when it presents itself.
But identifying debt collector harassment could be challenging when you’re stressed out.
Whether conduct amounts to unlawful harassment depends on its pattern, seriousness and context. Excessive calls, threats or intimidation can also breach applicable collection rules.
This may be done by your creditors directly (the people you owe the money to such as a utility bill company or loan company).
These standards can matter whether contact comes from the original creditor, a collection agency or another representative.
Your Rights With Debt Collectors
We’ve created this quick table to help you better understand your rights when dealing with debt collectors and prevent harassment. If you’d like to learn more, make sure to check out our detailed guide.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
Is Collection Harassment Illegal?
Just like any other form of harassment, debt collector harassment is unlawful.
Recognizing abusive debt collection practices allows you to deal with situations positively.
You do not have to tolerate harassment. Some conduct may breach regulatory rules, civil law or criminal law; not every unwanted demand automatically establishes a criminal offence.
Assess the specific behaviour and evidence rather than assuming a business knowingly broke the law.
» TAKE ACTION NOW: Fill out the short debt form
Online harassment by debt collectors
Excessive or threatening emails and messages can form part of harassment. The number and content, circumstances and reasonable contact requests all matter. See related guidance.
Keep copies and dates of digital communications, including any requests to change contact arrangements.
Moreover, there have been reports of debt collectors using social media to contact people over alleged debts.
Complain if online contact is threatening, excessive or unfairly reveals debt information. A private digital message is not automatically unlawful merely because of the channel used.
Protections Under UK Law
The applicable rules depend on the debt and activity. FCA consumer-credit regulation does not cover every form of debt collection, though privacy and other legal protections can still apply. See related guidance.
A debt collector can lawfully contact you over an unpaid debt. But there are limits to what they can do. In short, their legal powers are the same as those of an original creditor.
The things a debt recovery company CANNOT do are listed below:
- Pretend they have the power to seize possessions when they do not
- Produce papers that appear to be issued by a court when they are not
- Use confusing legal jargon to put you on a back foot
- Force their way into your home
- Coerce you into taking out a loan to pay what you owe
- Unfairly reveal or threaten to reveal debt information to an unauthorised third party.
- Threaten or harass you
- Refuse to leave when you ask them to
Debt collectors that behave in this manner can be reported for breaching the law. You have the right to complain to a debt collector’s head office.
Use the firm’s complaints process first. Ombudsman jurisdiction depends on the activity; FCA reports do not resolve an individual complaint. See related guidance.
What Is Classed as Debt Collector Harassment?
Lots of things can constitute debt collector harassment, such as:
- Calls at unreasonable times, considering the person’s circumstances.
- Ignoring reasonable requests about when, where or how contact is made; there is no universal FCA 8am–9pm window.
- Calls contrary to reasonable workplace or vulnerability-related contact arrangements.
- Excessive calls or messages that put inappropriate pressure on the person.
- Nuisance calls where debt collectors don’t speak when you answer
- Threatening or unreasonable home visits, including false claims of power to seize goods.
- Workplace visits without prior agreement in FCA-regulated consumer-credit recovery, or inappropriate disclosure to colleagues.
- Unlawful debt collection activities
This is not a complete list of what can be classed as debt collector harassment.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What can you do to stop nuisance calls when falsely accused of owing money?
Ask for a reasonable contact method and explain any vulnerability. The firm should consider your circumstances, but a preference or debt solution does not automatically prevent every necessary legal notice or communication. See related guidance.
You are allowed to inform them of the ways you want to be contacted and at the times of the day you are willing to speak with them.
If after you have provided them with this information, they continue to disregard your preferences, it can be used as further evidence of debt collector harassment.
See this message posted on a popular forum about debt collector harassment.
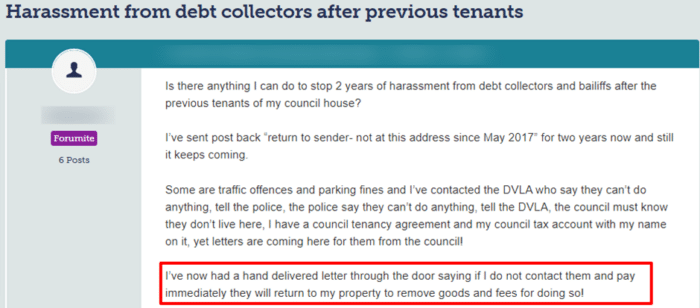
Source: Moneysavingexpert
What Can I Do if Debt Collectors Come to My Home?
Our financial expert, Janine, says: ‘I understand that having a debt collector at your door can be scary, especially when you are already under huge financial stress. It’s crucial that you stay calm and know your rights. They have no power to enter your home or take any of your possessions.’
An ordinary collector may request voluntary payment or entry but cannot force entry or seize goods.
An enforcement agent needs the relevant lawful authority and must follow the applicable rules. Police powers and statutory utility access are separate matters.
A judgment alone does not turn a creditor’s employee into a bailiff. Verify any warrant or writ and the person’s role before applying enforcement guidance.
You may refuse an ordinary collection visit and ask the visitor to leave. Continue to respond to genuine court papers or enforcement notices.
You might want to record them as evidence of debt collector harassment. Your approach to dealing with debt collectors at home must be positive.
The Impact of Debt and Harassment on Mental Health
Being in debt is bad enough on your mental well-being. But being harassed by a debt collector compounds things.
Mental health impact of debt collector harassment can be extreme and seeking help and support is a must.
You could start experiencing sleepless nights which in turn, affects your ability to work. Moreover, you could suffer from:
- Bouts of anxiety and stress
- Mood swings and feeling low
The disastrous effects of being harassed when in debt could even lead to suicidal thoughts.
If you’re feeling low and feel you’re being harassed, we suggest you seek help as soon as you can.
Debt counselling could be invaluable at a time you need it most. Plus, a counsellor could help you report the harassment to the right bodies.
Can They Tell My Family?
Collectors must handle information lawfully and avoid inappropriate disclosure to family, colleagues or neighbours. They may communicate with an authorised adviser or representative, and other lawful disclosures can be permitted.
Firms should take reasonable steps to avoid revealing collection activity to family, colleagues or neighbours. An authorised representative is different from an uninvolved third party.
Record inappropriate disclosures and complain to the firm. Depending on the issue, the ICO, an eligible Ombudsman or the relevant regulator may be appropriate. See related guidance.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Can My Debt be Wiped Because of Debt Collector Harassment?
Harassment does not automatically cancel a valid debt. Any redress or adjustment depends on the facts and the decision of the relevant body or court.
Regulators can take action within their powers, while an Ombudsman may require redress in an eligible case. Neither outcome should be assumed from a complaint alone.
Do not assume a complaint suspends repayment obligations or legal proceedings. Ask for any agreed hold in writing and follow court deadlines.
If a business closes or an account is transferred, that alone does not wipe out the balance. Verify the new owner and payment route.
How to Fight Back
Reporting debt collector harassment is something you may be worried about doing. But you won’t be alone if you do.
The process of making a debt collector harassment complaint can be split into three stages:
- Gather evidence of harassment
- Make a complaint to the creditor/debt collection company
- Make a complaint to governing bodies and others
Keep evidence you can safely obtain, but do not delay reporting threats or serious conduct while trying to assemble a complete file.
Useful evidence may include call logs, messages, letters, dated notes and witness accounts. You do not have to confront a visitor or obtain a video to make a complaint.
Send copies of relevant evidence with a clear account of what happened and the outcome you want. Keep your originals.
Ask them to stop and make specific requests of how you wish to be contacted in the future.
At this stage, it is hoped that any debt collector harassment will stop. But if it doesn’t you should proceed to step three as detailed below.
Complain to the Financial Ombudsman Service
Follow the escalation route applicable to the activity. A Financial Ombudsman complaint is available only where the matter falls within its remit. See related guidance.
Complain to the business first. If the activity falls within the Financial Ombudsman Service’s remit, you can normally escalate after a final response or eight weeks without one, usually within six months of the final response. The Ombudsman can require redress, such as compensation or correcting records; it does not fine firms or remove their authorisation.
You can also report relevant regulatory concerns to the FCA or a member trade body, but neither is a substitute for responding to court proceedings. See related guidance.
The FCA may be able to stop the debt collection agency from operating unlawfully.
The official complaints procedures for each can be found on their website. It is crucial to keep original and backup debt collector harassment evidence in case you need to complain to these groups.
Possible Outcome when Complaining to the Financial Ombudsman Service
The Financial Ombudsman Service has the power to award financial compensation to you if they rule in your favour against a debt collector.
If the FOS finds that a debt collector has not abided by the rules and laws by harassing you, they can instruct them to resolve the complaint.
In short, the FOS would ‘put you back to the position’ you were in if the issue hadn’t arisen. You could be awarded compensation for the distress you were caused.
It’s worth noting that FOS complaint outcomes can vary from case to case.
Checking for Other Debt Collectors
There are a lot of ways to get into debt. In fact, it’s not uncommon to owe money to several companies at once.
Perhaps you have a mortgage, a car loan, a couple credit cards and an item or two you bought on buy-now-pay-later schemes. It’s easy to lose track.
That’s why it’s important to regularly check your credit report and bank statements to make sure you haven’t missed anything.
A sold debt may appear under a new creditor name on your credit report, but not every debt or collector is reported to every credit reference agency.
Some of the debt collectors you’re most likely to come across are PRA Group, Lowell and Cabot Financial.
References





