


HMRC debt collection: checking a demand and payment options


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
Dealing with an unexpected letter from HMRC debt collectors can be a bit scary. But don’t worry, we’re here to help.
Check a demand against your tax account and verified HMRC contact details before paying or sharing information.
In this easy-to-read guide, we’ll explain:
- What HMRC debt is and how the collection process works.
- How to check if your HMRC debt is real.
- Ways to get help if you can’t afford to pay.
- What a Time to Pay Arrangement is.
- Other solutions for dealing with debt.
We understand that dealing with HMRC debt can be hard. We have lots of information to help you make the best choices.
Ready to learn more about how to handle your HMRC debt? Let’s get started.
What is HMRC?
How to Dispute
HMRC sends you a ‘decision letter’ letting you know whether you can appeal a tax decision.
It’s worth noting there’s a procedure to follow when appealing HMRC Debt.
You could appeal against:
- A tax bill which includes Income Tax, VAT, Corporation Tax
- Claims for tax relief
- A request for details or to check through your business records
- A penalty you received for late tax payments or late tax return submission
An appeal can be made by an accountant or someone else who manages your taxes. This can be helpful as understanding Tax Codes is important.
The appeal route, deadline and payment position depend on the decision. Do not assume that every appeal requires a fee or automatically postpones payment; representation may have costs, and postponement may need a separate request. See related guidance.
» TAKE ACTION NOW: Fill out the short debt form
Consequences of ignoring it
The consequences of ignoring an HMRC debt could lead to more stress and anxiety.
I’ve listed what may happen here:
- HMRC may use an applicable power to take control of goods or other enforcement procedure; this is not an automatic first step for every debt.
- An application for a County Court Judgement (CCJ) could be made against you
- A summons to appear in a magistrates’ court could be issued
- Bankruptcy proceedings could be started against you
- Money could be taken directly from your wages
- Money could be taken from your savings
What other debt solutions are there?
If you can’t afford to pay what’s owed, seek advice from a debt expert.
Tax arrears need specialist assessment. Some liabilities can be included in an appropriate formal debt solution, while exclusions, approval requirements and jurisdiction matter.
Formal solutions are legal processes which include:
- A Debt Relief Order (DRO)
- An Individual Voluntary Arrangement (IVA)
- Bankruptcy
An informal payment arrangement can spread a valid balance, subject to agreement. A new consolidation loan is a separate credit contract, not merely a non-binding arrangement with existing creditors.
An informal arrangement does not give the same statutory protection as insolvency. New borrowing remains subject to its own binding terms and may increase total costs.
Informal solutions are:
- A consolidation loan is new borrowing; compare the total cost and any security risk before considering it for tax arrears.
- A debt management plan (DMP)
- Paying each creditor individually but with payment plans
Is extra help available?
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
What is a Time to Pay Arrangement?
A Time to Pay arrangement spreads an agreed HMRC balance into instalments after an affordability assessment. It is not universally limited to twelve months. See related guidance.
The duration and terms depend on your circumstances and the debt. Interest or penalties may still apply; check the written arrangement and tell HMRC if you cannot keep to it.
Who can help with tax arrears?
A qualified tax adviser or accountant can help check liability, returns and appeals. A debt adviser can help assess affordability and debt options.
Self-employed people may also need business-debt advice. Check the adviser’s relevant expertise, fees and authority to deal with HMRC.
Different advisers have different roles:
- An independent financial adviser normally advises on financial products and planning; the title alone does not establish expertise in tax-debt disputes or insolvency. See related guidance.
- For a regulated product recommendation, check the adviser’s permissions and scope. For debt or tax work, seek the appropriate specialist rather than assuming any financial adviser covers it.
Case study
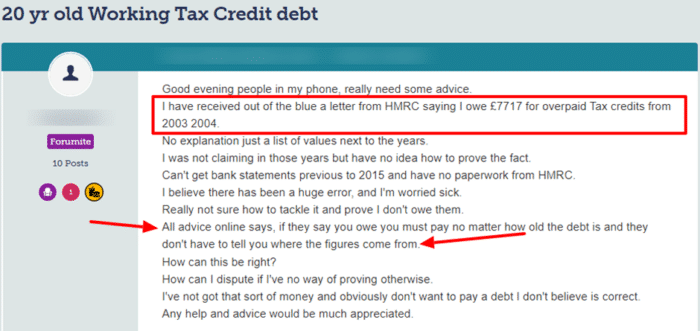
See the message a person posted on a popular online forum.
Source: Moneysavingexpert
Other Debt Collectors
You should check for more outstanding debts that you may have with other companies or debt collectors. Here are four steps you could take:
- Check your credit report for other defaults
- Check your email and post for reminders or overdue notices
- Check the court records for CCJs against you
- Check your bank statements for the names of other debt collectors
There are hundreds of debt collectors in the UK and each works with different companies to collect debts.
Some debt collection businesses act for creditors; others purchase debts. Check the letter and ask who owns the debt and how the balance was calculated.
If you see a name on your bank statement that you don’t recognise then you can search MoneyNerd to see if they’re a debt collector.
Take the first step towards tackling your debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
HMRC Contact Details
County Court proceedings





