


How long can debt collectors chase a debt? UK time limits explained


MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
MoneyNerd introduces enquiries to The Debt Advice Service and may receive a referral fee. For free, independent guidance and help finding a debt adviser, visit MoneyHelper.
This information and enquiry service is not a full financial assessment or a guarantee of suitability or debt write-off. Debt solutions are not suitable for everyone. Fees may apply, and your credit record and assets may be affected. Get advice on your circumstances before choosing a solution.
How long a debt can be pursued depends on the jurisdiction, debt type and legal history. A collector’s letter does not restart every limitation period, and a six-year-old debt is not automatically written off.
In this easy-to-read guide, we’ll help you understand:
- Where the debt might have come from.
- How to check if the debt is real (if it’s not, you don’t need to pay!).
- How to raise a dispute and respond to a legal deadline.
- Your choices to plan payments or even wipe off your debt.
Research shows that 64% of the people in the UK find dealing with debt collectors stressful1. We’ve felt the pressure, and we know it can be scary.
But don’t worry, we’re here to help you understand your options.
Can Your Creditor Chase Your Debt Forever?
For many simple-contract debts in England and Wales, the usual period to start a court claim is six years from when the creditor could sue. Different rules can apply to mortgage principal, interest, judgments and specialist debts. Scotland has separate prescription rules.
A qualifying payment or signed written acknowledgement before the relevant period expires can restart it. The effect of a particular communication must be checked rather than assumed.
Regular payments can keep restarting the relevant period for some debts. This is different from saying that time never runs while a payment plan exists.
A judgment does not disappear after six years. Enforcement rules and requirements for court permission may change with time, so obtain advice about an old judgment.
Plus, there are different rules for certain debts, for example, student loans.
» TAKE ACTION NOW: Fill out the short debt form
What is a Statute-Barred Debt and What Does it Mean for You?
Limitation can provide a defence to a court claim brought too late. In England and Wales this generally does not extinguish the underlying obligation; Scottish prescription can have a different effect.
Keep in mind that this does not mean that you can ignore your creditors and/or debt collectors for six years and expect your debts to be magically written off.
The starting point is when the relevant legal claim arose, subject to rules that can postpone or restart the period. It is not simply the date of the last contact.
For relevant debts, a payment or qualifying signed written acknowledgement can affect the period. A phone call or the creditor’s own letter does not, by itself, restart it.
A creditor continuing to send letters does not prevent the period running. A claim started within time can change the position, even if judgment is entered later.
The complete outline of how Statute-barred2 debts work is given in the Limitation Act 1980. Please keep in mind not to consider this act an easy way to write off your debts.
A valid debt may still be addressed through an affordable arrangement or an appropriate debt solution. Limitation is one legal issue, not the only form of help.
The Limitation Act 1980 primarily applies in England and Wales. Scotland and Northern Ireland have their own rules; seek advice for the actual jurisdiction. See related guidance.
Your Rights With Debt Collectors
Knowing your rights when dealing with debt collectors could make the situation less stressful.
That’s why we’ve created this simple table that explains what they’re allowed to do. For more information, make sure to check out our detailed guide.
| Debt collectors may | Limits and protections |
|---|---|
| Contact you to seek payment | For regulated consumer credit, contact must be at reasonable times and respect reasonable requests about when, where and how you are contacted. |
| Ask to discuss the debt at a home visit | A collector has no bailiff powers, cannot force entry or take goods, and should leave when asked. |
| Explain possible court action | They must not mislead you about their powers or threaten action they cannot lawfully take. |
| Discuss an affordable repayment or settlement | Get agreed terms in writing and obtain free advice if you dispute the debt or cannot afford payments. |
| A creditor may seek a separate court enforcement order | A CCJ alone does not give a collector access to your bank account. A third-party debt order requires a separate court process. |
| A creditor may assign a debt | Check who owns it and who is authorised to collect; do not disclose payment details to an unverified caller. |
| Make proportionate follow-up contact | Harassment is prohibited. Requests about contact must be considered; necessary legal notices may still be sent. |
For regulated consumer-credit collection, complain to the firm about breaches of the FCA rules and consider the Financial Ombudsman where eligible. The FCA receives regulatory intelligence but does not decide individual redress claims.
Understand your debt options
MoneyNerd can introduce you to The Debt Advice Service for free debt advice. MoneyNerd does not provide debt advice or recommend debt solutions.
The Debt Advice Service can explain your options, including their benefits, costs and risks. Options available depend on your circumstances. There’s no obligation to take a debt solution.
MoneyNerd does not provide debt advice or recommend debt solutions. The Debt Advice Service is a trading style of Pacific Financial Solutions Limited. If you request an introduction, we’ll share your details with their team so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd is a commercial introducer and may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
For free, impartial money guidance and help finding free debt advice, visit MoneyHelper.
How Do You Know If Your Debt is Statute-Barred?
These questions can help an adviser assess an ordinary contract debt. They are not a complete test for every liability:
- Has a court claim already been started, or a judgment or decree already been made?
- When could the creditor first sue, and have any payments affected the period? For a joint debt, the effect of another person’s payment needs specific advice.
- Has there been a qualifying signed written acknowledgement, and who made it? Not every letter or another joint debtor’s acknowledgement has the same effect.
An adviser must also check the jurisdiction, type of debt and any applicable exception before concluding that a time bar applies.
What Should You Do If You Know Your Debt is Unenforceable?
A debt can become time barred even if a collector kept writing. Contact alone is not the test.
Do not assume a creditor will never contact you again. Keep relevant documents and check any future demand or legal papers.
If court proceedings arrive, respond by the deadline and raise the appropriate defence; do not rely on silence.
We find it best to know how to handle debt collectors when they contact you after six years regarding your debt.
Here’s what you can do:
- Get a copy of your credit file.
- Write a letter to the creditor that is contacting you and inform them that the debt they are trying to pursue has become unenforceable. Be sure to use a service that confirms when your letter has been delivered so that you have proof that your creditor did indeed receive your letter.
- Explain the limitation dispute and ask for the dates and evidence the creditor relies on. In court, you must properly raise a defence and comply with directions; an informal assertion alone does not guarantee success. See related guidance.
Explain a dispute and request an itemised balance and evidence of liability. A valid or potentially valid dispute within FCA consumer-credit rules must be investigated with recovery paused, but a generic evidence request does not cancel a debt, override a court order or extend a court deadline.
Evidence should establish the basis and amount of liability. “100% proof” is not a separate universal legal standard, and an evidence request does not itself cancel a debt.
Thousands have already tackled their debt
Every day, our partner, The Debt Advice Service, helps people understand their options for dealing with debt. Their debt advice is free, with no obligation to proceed.
MoneyNerd introduces you to The Debt Advice Service. We do not provide debt advice or recommend debt solutions.

Natasha
Very helpful and informative thank you

If you submit the enquiry form, MoneyNerd will share your details with The Debt Advice Service so they can contact you.
Some debt solutions have fees and may negatively affect your credit rating. MoneyNerd may receive a fee if you go ahead with a debt solution through The Debt Advice Service.
The Debt Advice Service is a trading style of Pacific Financial Solutions Limited.
For free, impartial help and access to not-for-profit debt advice, visit MoneyHelper.
Does a Debt Being Statute-Barred Mean That It’s Written Off?
A debt being statute-barred means that if, for example, your creditor sues you in a court of law, you can defend yourself effectively.
For FCA-regulated collection, a firm must not continue demanding payment of a statute-barred debt after you say you will not pay because it is statute barred. Check that the rule applies to your debt.
Use the firm’s complaints process and any eligible ombudsman route if collection breaks the rules. A successful court claim against a collector is not automatic; obtain advice before starting proceedings.
You may be asking yourself “If I don’t have to pay the debt, isn’t that the same as the debt being written off?” Well, not exactly.
Credit reporting is a separate issue. A defaulted credit account normally drops off six years after its recorded default date; this does not itself determine whether the debt can be enforced.
Not every debt appears on a credit file. For reportable accounts, the relevant retention date depends on the record and status, not simply the debt’s age. See related guidance.
A CCJ normally stays on the register and credit file for six years from judgment. Paying the full judgment within one calendar month can allow the entry to be removed; paying later normally marks it satisfied rather than removing it. The debt does not automatically expire when the entry disappears.
It’s also worth noting that some debts won’t appear on a credit report, including certain utility debts.
Plus, certain types of debt, even if your debt is statute-barred, your creditor can still legally attempt to ask you to pay up using other actions that don’t involve a court order or judgement.
It can lead to a lot of debt issues that cause you stress and anxiety to say the least!
Is There Anything Your Creditors Can Do Once Your Debt Has Become Unenforceable?
Where the applicable limitation conditions are met, an ordinary debt in England and Wales may be time barred without being written off. Do not apply a universal six-year rule.
This means that there are certain cases in which your creditors can still pursue you and ask you to make payments towards your debt.
A limitation defence must be raised through the appropriate court process if a claim is issued.
A claim on a time-barred ordinary debt may be defended, but an ignored claim can still result in judgment until successfully challenged. Specialist statutory recovery powers require separate analysis.
This applies to certain cases such as the Department of Work and Pensions (DWP), local authority benefit overpayments and HMRC tax credit overpayments.
Some public debts have statutory deduction or other recovery powers outside an ordinary contract claim. The conditions and limits depend on the specific debt and benefit or earnings rules.
Understanding debt collection laws time limit
An existing judgment changes the analysis. Get advice on enforcement and any available challenge rather than treating it as an ordinary old invoice. See related guidance.
The relevant question is generally whether proceedings were started within the applicable period, not whether the CCJ was registered before six years elapsed. A later judgment is not automatically unenforceable.
You must also keep in mind that the Limitations Act 1980 does not cover all types of debts.
Some tax and other public debts are subject to special rules or exclusions. Do not assume either that all Crown debts expire after six years or that every debt owed to a public body is permanently enforceable.
Council tax, benefit overpayments and tax-credit overpayments have distinct liability and recovery rules. Check the particular order, notice and statutory power with an adviser. See related guidance.
Dealing with Debt Collectors: A Case Study
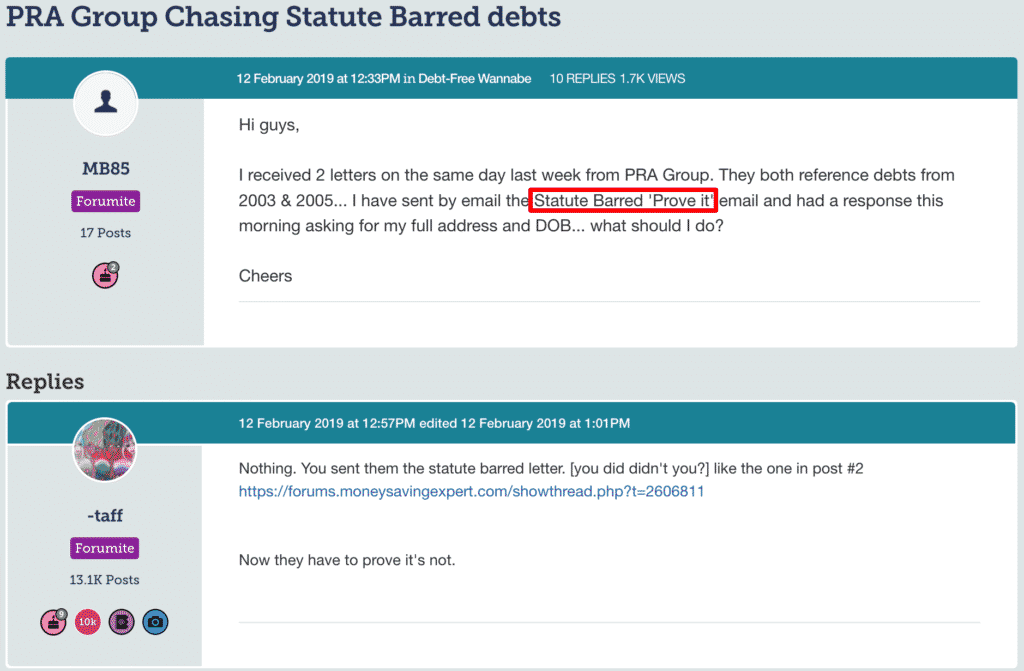
The case study below illustrates an example of an individual using the actions above to deal with statute-barred debt requests from a debt collector such as PRA group.
Available Options for Repaying Debts
Please bear in mind that this is not the end of the world.
A free debt adviser can compare an affordable repayment plan with formal debt solutions. IVAs and DROs have eligibility rules, fees or other consequences and do not cover every debt; Scotland has different options. See related guidance.
If you aren’t sure about the status of your debt, you can contact a debt charity for some free advice. Their advisors will be able to look at your situation in detail and give you a plan moving forward.
Never feel pressured to paying your creditors even a penny more than you can afford.
And make sure you get the right advice from a debt adviser before you commit to any sort of repayment plan.
Glossary of terms
Creditor – the business/organisation that money is owed to
Debtor – the person who owes money
CCJ – County Court Judgement
FCA – Financial Conduct Authority
FOS – Financial Ombudsman Service
References





